Statement in Response to Court Cost Award
Image File
Original HTML

May 4, 2026

The Métis National Council is disappointed with the Court’s decision on costs.

This case was brought forward in good faith, grounded in the MNC’s responsibility to uphold accountability and protect the collective interests of the Métis Nation. While we disagree with both the outcome and the characterization of the case, we respect the Court’s process.

We will not engage in inflammatory or personal rhetoric. Our focus remains on the work of serving Métis Citizens and advancing the shared priorities of Métis governments across the Homeland.

We were aware that this could be a possible outcome and have planned accordingly. The MNC remains stable, focused, and will continue to operate as usual.

“This decision does not change who we are or the work ahead of us,” said MNC President Victoria Pruden. “We will continue to move forward with our mandate as the national Métis organization, strengthening governance, promoting collaboration and unity, and advancing the priorities of Métis governments across the Homeland.”

The MNC remains committed to working with partners, including Canada, to advance reconciliation and deliver results for Métis Citizens.

Class (B2B/B2C)
Ignore
Ingest Status
Need Review
Dedupe hash
3e9a99bb0781b4b461dca498bcd2dfaa
Press Eligible
No
Press Eligible Reason
Irrelevant (need review): The statement primarily concerns a court decision and litigation costs.
Source Name
Métis National Council
Original Summary

May 4, 2026 The Métis National Council is disappointed with the Court’s decision on costs.  This case was brought forward in good faith, grounded in the MNC’s responsibility to uphold accountability and protect the collective interests of the Métis Nation. While we disagree with both the outcome and the characterization of the case, we respect the Court’s […]

Image URL
https://www.metisnation.ca/wp-content/uploads/2026/05/Statement-1.png
Content Hash (SHA-256, erste 32 hex)
88beb27ff85c40ab4ed3005fea723a0b
Métis Governments Advance Shared Housing Priorities at Inaugural Métis Policy Forum
Image File
Original HTML

Historic gathering strengthens collaboration to improve housing outcomes for Métis citizens and communities

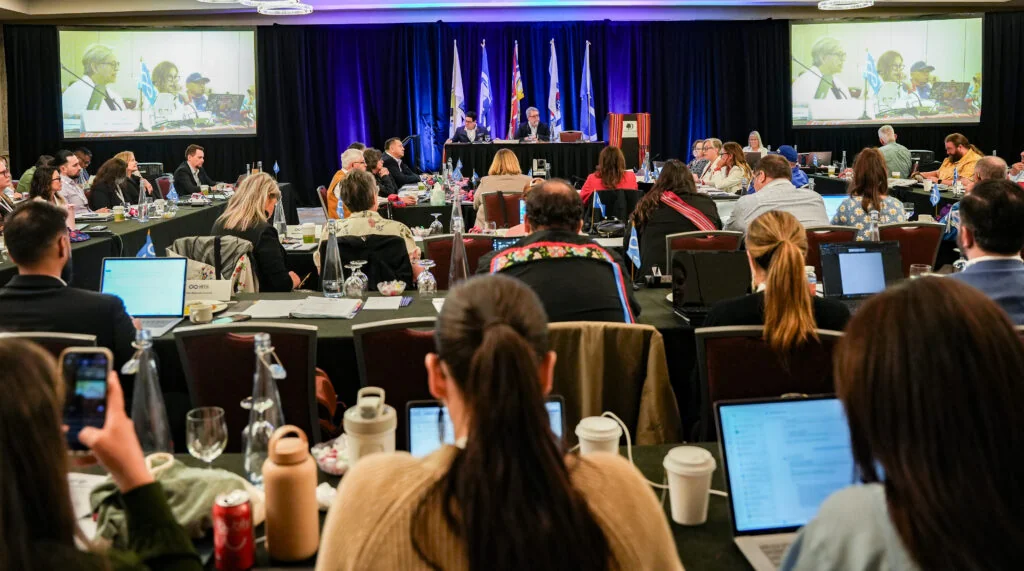
The inaugural Métis Policy Forum (MPF) concluded today, convening Métis governments from across the Homeland, alongside Métis youth, Elders, and veterans, to advance shared housing priorities and reinforce a renewed commitment to coordinated, technical collaboration that will drive improved housing outcomes for Métis communities.

The Métis Policy Forum was established to provide a non-political, collaborative space for Métis governments and organizations to come together on shared policy priorities while fully respecting the distinct rights, jurisdictions, and governance authorities of each participant.

Housing remains one of the most urgent priorities for Métis governments. Through leadership dialogue, technical working sessions, and knowledge‑sharing, participants examined common barriers, emerging federal initiatives, and opportunities to better align efforts so Métis housing priorities are reflected in national policy and funding decisions. The Forum also marked a clear commitment to ongoing technical collaboration, including renewed intergovernmental working groups to advance concrete, coordinated solutions.

Participants affirmed that renewal of the Canada–Métis Nation Housing and Homelessness Sub‑Accord is a pressing Métis Nation priority. Long‑term, predictable, distinctions‑based funding remains essential, including flexible program design, pre‑development support for smaller Métis governments, and investments that meet the realities of northern and rural communities. Participants emphasized that housing investments must be made along the entire housing continuum to meet the needs of Métis families, including maintaining and preserving existing housing stock to ensure long‑term affordability.

Strengthening partnerships with federal, provincial, and territorial governments, expanding capacity supports, and deepening evidence‑based technical collaboration with Canada will be critical to advancing effective, Métis‑led housing solutions.

The Métis National Council’s role in the Forum was limited to convening and providing logistical and administrative support. All policy discussions and outcomes were led by participating Métis governments and organizations.

The success of the inaugural Métis Policy Forum reaffirmed a shared commitment to continued collaboration where priorities align, grounded in respect for the autonomy and governance processes of each Métis government. The Métis National Council looks forward to supporting future Métis Policy Forums that foster collaboration and advance the priorities identified by participating governments for the benefit of Métis communities and citizens.

– 30 –

Since 1983, the Métis National Council has been the national and international voice of the Métis Nation within Canada. Through national research and policy development, the MNC advocates to advance the rights and interests of Métis Governments, including the implementation of the Métis Nation’s inherent right to self-determination and self-government. The MNC is committed to accountability and transparency within its operations, and to its relationships with its Governing Members and other partners.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
2579d1feab583d8e38d6caa7203cfe1d
Press Eligible
Yes
Press Eligible Reason
Métis governments discuss housing priorities, funding, and coordinated solutions.
Source Name
Métis National Council
Original Summary

Historic gathering strengthens collaboration to improve housing outcomes for Métis citizens and communities The inaugural Métis Policy Forum (MPF) concluded today, convening Métis governments from across the Homeland, alongside Métis youth, Elders, and veterans, to advance shared housing priorities and reinforce a renewed commitment to coordinated, technical collaboration that will drive improved housing outcomes for […]

Image URL
https://www.metisnation.ca/wp-content/uploads/2026/06/DSC07943-copy-2-1024x571.jpg
Content Hash (SHA-256, erste 32 hex)
2fcfa089cc562624273c2efaf31af002
Six Métis Experiences You Can Enjoy in Canada This Summer
Image File
Original HTML

By President Victoria Pruden

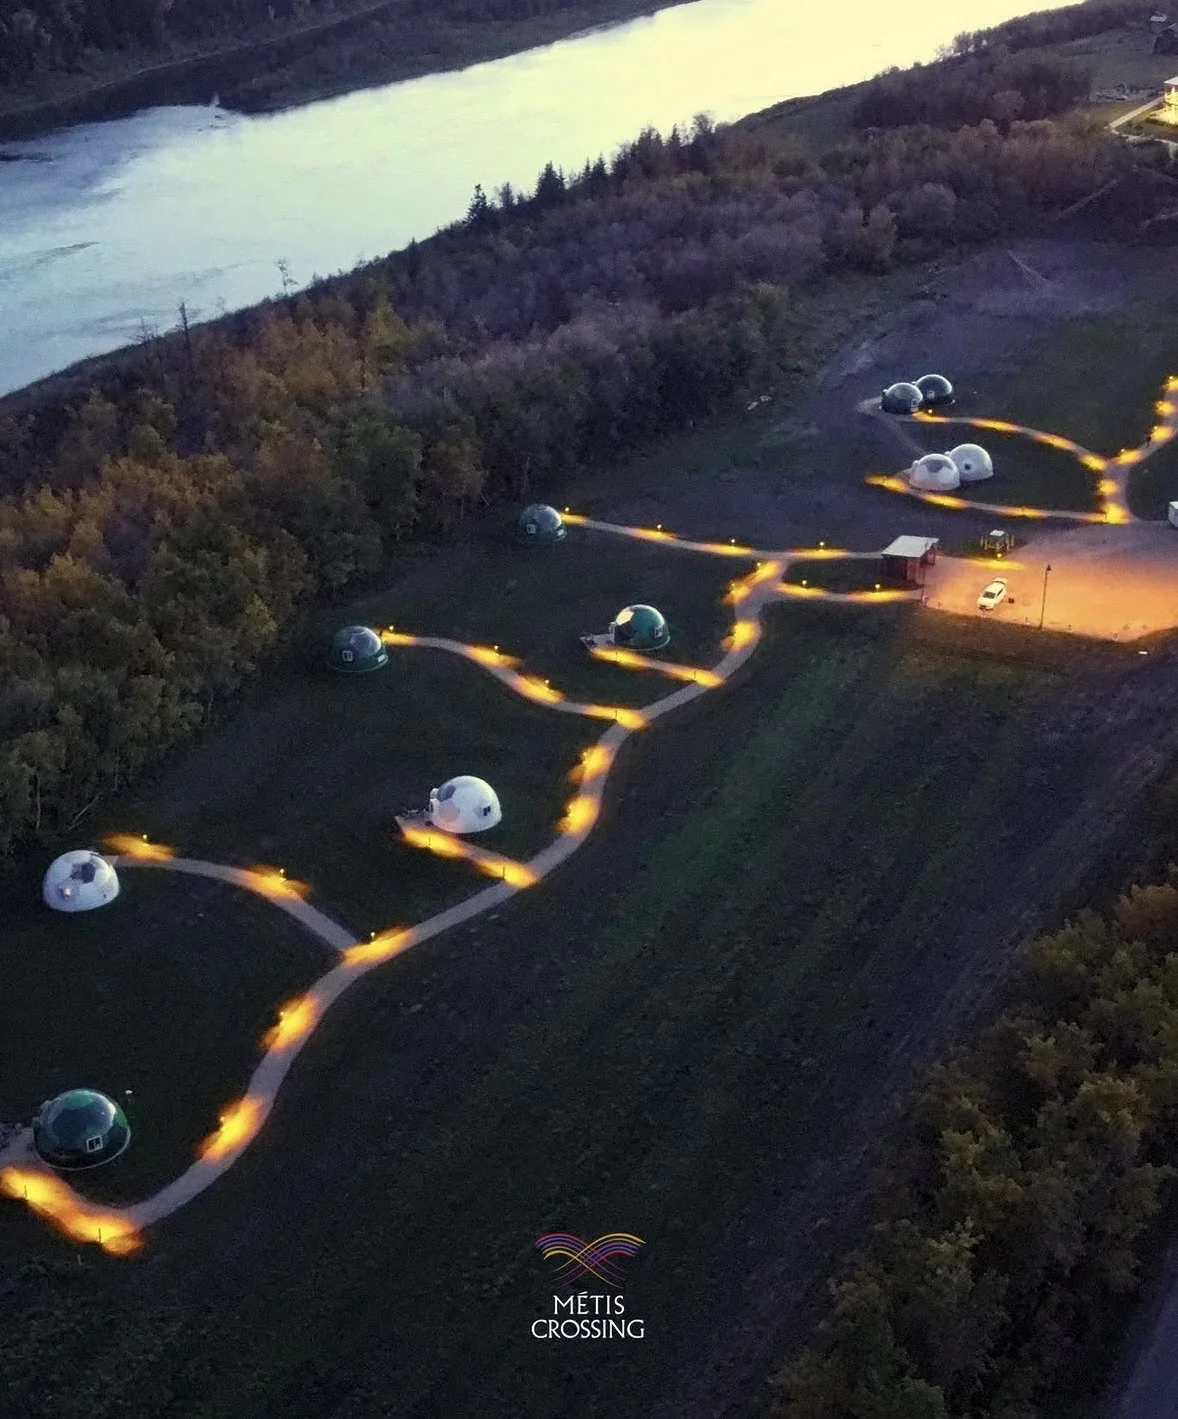
As Canadians shy away from travelling south of the border, many are looking for vacation ideas on Canadian soil. From farm-to-table dinners, to glamping in a trapper’s tent under the northern lights, Métis tourism runs a host of unique experiences across the Homeland.

There is no better time to explore and celebrate the Canadian outdoors than during Indigenous History Month.

Since the fur trade, Métis have been heavily involved in building the Canadian economy. Modern day Métis gatherings and businesses now offer fun opportunities for vacationers to experience and learn about Métis culture. Here are six Métis activities and vacation ideas for this summer.

1. Métis Crossing in Smoky Lake, Alberta

Imagine taking in the views of the North Saskatchewan River from your trapper’s tent, sky-watching dome, or boutique hotel room. This isn’t your typical cultural centre; it is a cultural destination steeped in history and connection. You can start your day with a hearty traditional breakfast of bannock, Saskatoon berry lemonade, and buffalo sausage before heading outside for activities like buffalo tours, traditional plant walks, voyageur canoeing, and archery. Métis Crossing provides authentic opportunities to delve into the unique way of life of the Métis through educational programs, interactive exhibits, and immersive experiences. The destination combines historical buildings—including a restored Métis farmstead—with contemporary buildings showcasing Métis craftsmanship.

2. Batoche National Historic Site in Batoche, Saskatchewan

For many Métis individuals and communities, visiting Batoche National Historic Site is a pilgrimage: a journey to honour our ancestors and the sacrifices made during the 1885 Resistance. It offers an opportunity to walk into history, but also to learn about Métis culture of the past and present. Experience the Visitor Centre and museum, the Batoche cemetery, or take part in daily guided tours and special days with cultural activities such as beading and embroidery. Batoche provides immersive, and accessible opportunities to engage with Métis history and culture.

Just down the road from the historic site, visitors can enjoy Back to Batoche Days (July 16–19, 2026) with live music, chariot, pony, and relay races, voyageur games, and many more activities.

3. The Patch by Prairie Berry in Glenlea, Manitoba

Prairie Berry is a strawberry farm located 10 minutes south of Winnipeg, Manitoba. Owners Matt and Jen Turenne offer a unique Farm-to-Table Dinner experience in the middle of their strawberry patch for 10 days. The five-course meal features fresh strawberries from the patch in every dish and other locally sourced ingredients. Savour each bite as you listen to live music or take a break between courses to pick your own strawberries in the patch.

4. Métis Cultural Walking & Big Canoe Tours in Sault Ste. Marie, Ontario

Exploring Ontario’s scenic waterfronts, historical landmarks, and hidden waterways is a fun way to learn about and better understand Métis history and contemporary way of life.

The Lake Superior Watershed Conservancy and the Huron-Superior Regional Métis Community have developed interpretive canoe and walking tours to connect visitors to Métis culture and provide a glimpse into a vibrant community life centered around fishing and waterways. These tours operate out of the Métis Heritage Centre, the first of its kind in Ontario, and emphasize the importance of environmental stewardship and the interconnectedness of culture, ecology, and community while providing a fun summer activity outside.

5. Locality Brewing in the Township of Langley, British Columbia

You can visit a scenic Métis-owned working farm and brewery called Locality Brewing. They offer a true “Field to Glass” experience—where the barley and hops are grown, malted, and brewed on site. The brewery sources local, sustainable ingredients and follows Métis land-based traditions. From Wednesday through Sunday, visitors can enjoy bison burgers, bison poutine, and vegetarian options from Stampede Burgers, a Métis-owned food truck. With farm tours, a pond walk featuring edible plants and their Michif names and pronunciations, yoga, live music, and cold beers, it’s a place where every experience connects guests to the land, the harvest, and the farmers behind it.

6. Aurora Village on the Ingraham Trail near Yellowknife, Northwest Territories

Rooted in the Métis and Dene traditions of Fort Resolution, Aurora Village is more than just a Yellowknife viewing spot for the northern lights: it’s a place where stories, food, and landscapes come together. Guests can gather in warm teepees, learn about northern ways of life, enjoy northern fare from a late-night menu, and witness the Aurora Borealis from custom-built heated seats designed by Aboriginal elders. Enjoy hiking, snowshoeing, dog sledding, and ice fishing and experience the history and hospitality of Indigenous communities in the north.

Here are just a few ways Canadians can spend time outdoors this summer while learning about Métis culture, history, and traditions during Indigenous History Month.

Batoche National Historic Site:

Class (B2B/B2C)
B2C
Ingest Status
Rewritten
Dedupe hash
d441156553435e7f9655ebe84ad8db25
Press Eligible
Yes
Press Eligible Reason
QA FAIL (need review): The target introduces the specific organizational title 'Métis National Council President' for Victoria Pruden, which is not explicitly stated anywhere in the source. The source only identifies her as 'President Victoria Pruden.'
Source Name
Métis National Council
Original Summary

By President Victoria Pruden As Canadians shy away from travelling south of the border, many are looking for vacation ideas on Canadian soil. From farm-to-table dinners, to glamping in a trapper’s tent under the northern lights, Métis tourism runs a host of unique experiences across the Homeland. There is no better time to explore and […]

Image URL
https://www.metisnation.ca/wp-content/uploads/2026/06/IMG_2865.jpg
Content Hash (SHA-256, erste 32 hex)
30d88023c7177d49b37820f792482619
Métis Nation Calls for a Team Canada Approach to Protect Canada’s Economy Amid U.S. Tariffs’
Image File
Original HTML

MNC urges Ottawa to include Métis workers, businesses and governments in Canada’s tariff response and economic strategy, highlighting the Métis Nation’s role in strengthening domestic supply chains, trade and nation-building.

The Métis National Council (MNC) supports a strong Team Canada approach as Canada responds to U.S. tariffs and works to protect Canadian workers, businesses and communities.

Nearly 250 years ago, Métis first played a foundational role, through their work, businesses and dedication, in contributing to and shaping the distinct and proud identity that Canada and Canadians cherish today. Métis citizens and their businesses continue to be important players in Canada’s economy and are as determined today as their ancestors were in the time of the fur trade to ensure that all Canadians succeed and share in the great riches that this land can provide for all of us.

MNC’s 2025 Status of the Métis Economy Report found that the Métis economy generated approximately $21 billion in GDP in 2015, while Métis businesses generated $25.4 billion in revenue in 2020, illustrating the continued role the Métis Nation plays in shaping and growing Canada’s economy, not just as bystanders but as leaders.

“The Métis Nation is not simply asking to be protected from the impacts of this trade dispute,” said MNC President Victoria Pruden. “We are ready to be part of Canada’s response. A Team Canada approach must include the Métis Nation.”

As Canada strengthens domestic supply chains, advances nation-building projects, expands Buy Canadian and federal procurement initiatives, develops critical minerals and energy infrastructure, and diversifies its international trade relationships, Métis participation must be built into Canada’s economic strategy.

The impact of the new tariffs and ongoing economic uncertainty will require a response from the Government of Canada, and the MNC is calling on the Government of Canada to ensure Métis workers and businesses can effectively access tariff-response measures and work directly with Métis governments to expand opportunities in procurement, workforce development, investment and trade diversification.

Métis economic participation is not separate from Canada’s economic strategy. It is part of Canada’s competitive advantage. The Métis Nation has been trading, building and creating economic partnerships across North America for generations. As Canada confronts this consequential moment, the Métis Nation is ready to bring that experience, entrepreneurial spirit, and determination to Team Canada.

– 30 –

Since 1983, the Métis National Council has been the national and international voice of the Métis Nation within Canada. Through national research and policy development, the MNC advocates to advance the rights and interests of Métis Governments, including the implementation of the Métis Nation’s inherent right to self-determination and self-government. The MNC is committed to accountability and transparency within its operations, and to its relationships with its Governing Members and other partners.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
71771262f1e0896d113fb6b85cf66500
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: HIGH. Flags: ['finance', 'numbers']. Stichprobe: False
Source Name
Métis National Council
Original Summary

MNC urges Ottawa to include Métis workers, businesses and governments in Canada’s tariff response and economic strategy, highlighting the Métis Nation’s role in strengthening domestic supply chains, trade and nation-building. The Métis National Council (MNC) supports a strong Team Canada approach as Canada responds to U.S. tariffs and works to protect Canadian workers, businesses and […]

Image URL
https://secure.gravatar.com/avatar/dd60576344172e717119b48600b353acdee8c57863dc8c764df32b8586e7e8ff?s=96&d=mm&r=g
Content Hash (SHA-256, erste 32 hex)
930bf197b76e22f1978bb82a06d70981
What Is a 1031 Exchange Loan and How Does It Work?
Image File
Original HTML

What Is a 1031 Exchange Loan and How Does It Work?

Key Takeaways

- A 1031 Exchange Loan is financing used to buy the replacement property in a Section 1031 tax‑deferred exchange when sale proceeds alone aren enough or aren available within IRS deadlines.

- It works by pairing with a qualified intermediary: the sale funds are held by the intermediary, you identify replacement property within 45 days, then the lender evaluates and funds the purchase so the exchange closes within the 180‑day total period.

- Financing matters because exchange deadlines are strict and transactions often face delays (seller timing, lender docs, market competition); without a loan, you risk losing the deal or triggering capital gains taxes.

- Hard‑money or private lenders often suit 1031 exchanges better than traditional banks, since they can fund faster, simplify underwriting, and align with tight exchange timelines.

- Investors use 1031 loans to scale up (e.g., into larger multifamily, commercial, or niche assets like parking), diversify, and preserve deferred taxes in the portfolio, accelerating long‑term growth while staying compliant with IRS rules.

Real estate investing is often about timing. The right property may become available unexpectedly, market conditions can change quickly, and opportunities to grow a portfolio rarely wait for perfect circumstances. For investors utilizing a 1031 exchange, timing becomes even more critical because strict IRS deadlines govern the entire process. This is where a 1031 Exchange Loan can play a crucial role.

A 1031 exchange offers investors the opportunity to defer capital gains taxes when selling one investment property and purchasing another qualifying property. While the tax advantages are substantial, completing an exchange successfully requires careful planning, coordination, and often, access to financing.

In this guide, we’ll explore what a 1031 Exchange Loan is, how it works, when investors typically use one, and why financing can be an essential component of a successful exchange strategy.

Ready to discuss your next exchange opportunity? Visit the Contact page to learn more about our commercial lending solutions and speak with our team about financing your next investment property acquisition.

Understanding the Basics of a 1031 Exchange

Before discussing financing, it’s important to understand the purpose and structure of a 1031 exchange.

A 1031 exchange refers to Section 1031 of the Internal Revenue Code, which allows investors to defer capital gains taxes when exchanging one investment property for another qualifying investment property. Rather than paying taxes immediately after selling an asset, investors can reinvest the proceeds into another property and continue building wealth through real estate.

For many investors, this strategy serves as a powerful tool for portfolio growth. Instead of losing a portion of their equity to taxes after each sale, they can leverage that capital to acquire larger, more profitable, or better-positioned properties.

What Is a 1031 Exchange Loan?

A 1031 Exchange Loan is a financing solution used to help investors purchase a replacement property as part of a tax-deferred exchange transaction.

While every transaction is unique, the purpose of the loan remains the same: to provide capital when exchange proceeds alone are insufficient or unavailable within the required timeframe.

Many investors assume they can simply sell one property and use the proceeds to buy another. In reality, commercial real estate transactions often involve complications that make financing necessary.

Want to Learn More About 1031 Exchange Financing? Understanding your financing options can help you make timely and strategic real estate investment decisions. Explore how hard money loans can provide the speed and flexibility needed to complete a successful 1031 exchange.

Why Financing Matters in a 1031 Exchange

One of the biggest misconceptions about 1031 exchanges is that they are solely tax-related transactions. While tax deferral is certainly a major benefit, financing often plays an equally important role.

Real estate transactions rarely unfold exactly as planned. A seller may delay closing. A lender may require additional documentation. Market competition may create pressure to move quickly.

Without access to financing, investors can find themselves unable to acquire a replacement property within the required timeframe.

How Does a 1031 Exchange Loan Work?

Although every transaction is different, the process generally follows a similar structure. The exchange begins when an investor sells an investment property. Rather than receiving the proceeds directly, the funds are held by a qualified intermediary in accordance with IRS requirements.

The investor then identifies one or more replacement properties within the 45-day identification period. Once a suitable property has been selected, financing can be arranged to facilitate the acquisition. The lender evaluates the property and transaction, determines loan terms, and provides funding necessary to complete the purchase.

The goal is not simply to obtain financing but to ensure that financing aligns with the timing requirements of the exchange.

Why Traditional Bank Financing Can Create Challenges

Traditional banks play an important role in commercial real estate lending, but they are not always the ideal solution for a 1031 exchange transaction.

Conventional lending processes can involve extensive underwriting, multiple approval stages, and lengthy documentation requirements. While these procedures are designed to manage risk, they can create delays that are problematic when exchange deadlines are approaching.

For example, a lender may require additional financial statements, property reports, or committee approvals before issuing final approval. These steps can extend the timeline beyond what the investor can comfortably accommodate.

Common Property Types Financed Through a 1031 Exchange

One of the advantages of a 1031 exchange is the wide range of qualifying investment properties available to investors.

Many investors use exchanges to move into larger apartment communities and income-producing residential assets. In these situations, multi-family loans are often used to facilitate the acquisition of larger properties that generate stronger cash flow and long-term appreciation potential.

Others pursue multi-family home financing opportunities to expand their rental portfolios and improve investment performance.

Commercial real estate investors frequently exchange into retail centers, office buildings, industrial facilities, and mixed-use developments. These assets often provide diversification and opportunities for increased income.

The flexibility of the exchange structure allows investors to align their acquisitions with broader portfolio goals while taking advantage of changing market conditions.

Benefits of Using a 1031 Exchange Loan

A 1031 Exchange Loan provides more than simple access to capital. It can create opportunities that may not otherwise be available.

One significant advantage is the ability to preserve tax-deferral benefits. Exchange deadlines are strict, and financing can help ensure transactions are completed within the required timeframe.

Financing can also increase purchasing power. Rather than being limited to available equity, investors can leverage financing to acquire larger assets or properties with stronger growth potential.

Speed is another major benefit. In competitive markets, investors often need to act quickly to secure desirable properties. Access to financing can help them compete more effectively and avoid losing opportunities to other buyers.

Perhaps most importantly, financing creates flexibility. Real estate investing is rarely predictable, and having access to capital allows investors to adapt to changing circumstances without compromising long-term objectives.

How 1031 Exchange Financing Supports Portfolio Growth

For many investors, a 1031 exchange is not simply a way to defer taxes. It is a strategic tool for building a stronger real estate portfolio.

Through 1031 exchange financing, investors can move from smaller assets into larger commercial properties, diversify across asset classes, and pursue investments that generate greater income and appreciation potential.

Over time, these exchanges can create a powerful compounding effect. Deferred taxes remain invested, equity continues to grow, and investors gain access to opportunities that may have been difficult to achieve otherwise.

The ability to reinvest capital while leveraging financing can accelerate portfolio growth and support long-term wealth-building objectives.

Looking for Real Estate Investment Opportunities? Explore how Wilshire Quinn provides investors with access to real estate-backed investment opportunities designed to deliver potential income and portfolio diversification. Learn more

Conclusion

A 1031 Exchange Loan can be an essential resource for investors navigating the complexities of a tax-deferred exchange. While the benefits of a 1031 exchange are well known, completing the transaction often depends on having access to timely and reliable financing.

Whether you’re exchanging into a multifamily property, commercial asset, or specialized investment, understanding how financing fits into the process can help you make informed decisions and position your portfolio for future growth.

Frequently Asked Questions

1. What is a 1031 Exchange Loan?

A 1031 Exchange Loan is financing used to purchase a replacement property in a tax-deferred 1031 exchange. It provides capital when exchange proceeds alone are insufficient or unavailable within IRS deadlines. This loan helps investors meet strict timelines, preserve tax deferral, and acquire larger or more profitable properties without losing equity to taxes.

2. How does a 1031 Exchange Loan work?

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
f99fccbe74d9b14598ba6a049668bc95
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['finance', 'numbers']. Stichprobe: False
Source Name
Wilshire Quinn Capital, Inc.
Original Summary

<p>What Is a 1031 Exchange Loan and How Does It Work? Key Takeaways A 1031 Exchange Loan is financing used to buy the replacement property in a Section 1031 tax‑deferred exchange when sale proceeds alone aren enough or aren available within IRS deadlines. It works by pairing with a qualified intermediary: the sale funds are [...]</p> <p>The post <a href="https://wilshirequinn.com/1031-exchange-loans-explained/">What Is a 1031 Exchange Loan and How Does It Work?</a> appeared first on <a href="https://wilshirequinn.com">Wilshire Quinn Capital</a>.</p>

Image URL
https://wilshirequinn.com/wp-content/uploads/2026/07/steptodown.com710338.jpg
Content Hash (SHA-256, erste 32 hex)
49f47cd281cfe3323c66218a3caf9be3
Direct Private Lender vs. Traditional Bank: Why Speed Matters in Real Estate Financing
Image File
Original HTML

Direct Private Lender vs. Traditional Bank: Why Speed Matters in Real Estate Financing

In real estate, timing can significantly impact the success of a transaction. Whether an investor is acquiring a property, refinancing an asset, or pursuing a value-add strategy, having the right financing partner can make the difference between moving forward and missing an opportunity.

Traditional banks remain an important source of real estate financing, particularly for long-term loans and stabilized properties that fit conventional lending criteria. However, many investors encounter situations where a shorter timeline, a transitional property, or a unique investment strategy requires a different type of financing solution. This is where direct private lenders can provide an alternative.

Contact Us About Your Financing Needs: Have a time-sensitive acquisition, refinance, or unique real estate investment opportunity? Contact our team to discuss your financing options.

Understanding the Difference Between Direct Private Lenders and Traditional Banks

Traditional banks and direct private lenders both provide real estate financing, but their lending models are often designed for different purposes.

Banks typically focus on long-term financing and operate within established lending frameworks designed to manage risk across a broad range of borrowers and industries. This approach provides borrowers with access to competitive rates and traditional loan products.

Direct private lenders, on the other hand, specialize in short-term bridge financing and provide capital for time-sensitive real estate opportunities. Their lending platforms are designed around speed, flexibility, and efficient execution.

Learn More About Direct Private Lending: Discover more about how direct private lenders provide faster, more flexible financing than traditional banks for time-sensitive real estate opportunities and investment projects.

Why Direct Private Lenders Can Move Faster

The ability of direct private lenders to move quickly comes from the structure and focus of their lending model:

- Streamlined Decision-Making – While traditional bank loans often involve multiple layers of review as part of a broader institutional process, a direct private lender provides a more streamlined approach, with the same team evaluating the transaction, making lending decisions, and moving the loan through closing.

- Flexible Transaction Evaluation – Traditional banks rely on standardized qualification criteria designed for consistency across a wide range of loan products. Direct private lenders often evaluate transactions based on the specific characteristics of the property, the overall opportunity, and the exit strategy. This more flexible approach can allow lenders to consider transactions that may not fit within the rigid parameters of traditional financing, while keeping the evaluation process focused and efficient.

Get a Faster Financing Solution. See how Wilshire Quinn Capital’s direct private lending approach can help streamline your path to funding.

When a Direct Private Lender May Be the Right Fit

A direct private lender may be a strong financing option when:

- Speed is critical: An investor needs to meet a short closing timeline or compete in a competitive acquisition process.

- The property is transitional: The asset requires stabilization, renovations, lease-up, or operational improvements before qualifying for permanent financing.

- A value-add strategy is planned: The borrower intends to improve the property and increase its long-term value.

Wilshire Quinn Capital’s Approach to Direct Lending

Wilshire Quinn Capital is a direct portfolio lender specializing in short-term bridge loans for commercial and investment residential real estate.

By maintaining an in-house underwriting process focused on the value and equity position of the property, Wilshire Quinn Capital is able to evaluate opportunities efficiently while maintaining a disciplined approach to lending. This structure allows us to determine interest within 24 hours and fund in as little as 5–7 business days.

Looking for a Direct Asset-Based Lending Solution? Read more here: Wilshire Quinn Capital’s property-focused underwriting can help you secure short-term bridge financing quickly and efficiently.

Choosing the Right Financing Partner

The best financing solution depends on the property, the investment strategy, and the timeline involved.

For borrowers pursuing long-term stabilized assets, traditional bank financing may be the right fit. For investors who need speed, flexibility, and certainty of execution, a direct private lender can provide an alternative path to closing.

Understanding the differences between these financing options allows investors to choose the approach that best supports their goals.

With more than 14 years of experience providing asset-based bridge loans, Wilshire Quinn Capital helps investors move quickly when opportunities arise. Contact us today to learn more.

FAQs

1. What is the main difference between a direct private lender and a traditional bank?

Traditional banks focus on long-term, low-rate financing for stabilized assets and follow rigid, standardized underwriting. Direct private lenders specialize in short-term, asset-based bridge loans, prioritizing speed, flexibility, and deal-specific evaluation over strict borrower criteria, making them ideal for time-sensitive or transitional real estate opportunities.

2. How much faster can a direct private lender fund compared to a bank?

Banks often take 30–90 days due to layered reviews and compliance checks. Direct private lenders can issue indicative terms within 24–48 hours and fund in 5–10 business days (sometimes faster), because decisions are made in-house without committee approvals, enabling investors to meet tight closing deadlines.

3. When should I choose a private lender over a traditional bank?

Choose a private lender when speed is critical, the property is transitional (renovations, lease-up), your deal doesn’t fit bank guidelines, or you need a short-term bridge to stabilization. Use banks for long-term, low-cost financing on stabilized assets when you have time for conventional underwriting and documentation requirements.

4. Why are private lenders able to move faster than banks?

Private lenders use streamlined, in-house underwriting focused on the property’s value and exit strategy, avoiding multi-department reviews and heavy compliance layers. This asset-based, flexible evaluation allows quick decisions (often within 24–48 hours) and faster funding, whereas banks rely on standardized criteria and slower institutional processes.

5. Do private lenders only lend based on the property, not the borrower?

Private lenders emphasize asset-based underwriting—property value, equity, and exit strategy, more than perfect borrower financials. While they still assess risk, they can accommodate complex ownership, limited documentation, or transitional assets that banks may reject, provided there is sufficient collateral and a credible repayment plan.

6. Are private lender loans more expensive than bank loans?

Yes. Private loans typically carry higher interest rates and fees than banks, reflecting shorter terms, faster funding, and greater flexibility. They’re designed as short-term bridge capital; the premium pays for speed, certainty, and the ability to finance transitional or non-standard deals that conventional lenders won’t support.

7. What types of real estate deals are best for private lenders?

Time-sensitive acquisitions, refi emergencies, value-add projects, renovations, lease-up scenarios, and transitional commercial or multifamily assets. Private lenders excel when you need quick capital to secure a deal, complete improvements, or bridge to permanent financing once the property stabilizes and qualifies for conventional loans.

8. How do private lenders evaluate risk differently than banks?

Private lenders conduct fast, deep due diligence focused on collateral value, loan-to-value, and exit strategy, often approving within 48 hours. Banks use slower, automated systems and strict compliance checks across income, credit, and documentation. Private lenders mitigate risk via equity cushions and short terms rather than rigid borrower qualifications.

9. Can private lenders fund deals banks reject?

Often yes. Private lenders can finance non-warrantable properties, mixed-use assets, complex ownership structures, or borrowers with limited documentation if the collateral and exit are strong. This flexibility makes them valuable for deals outside mainstream bank frameworks, though at a higher cost and shorter term than conventional financing.

10. What is the typical loan term for a private lender?

Private loans are usually short-term, commonly 6 months to 3 years, designed as bridge financing until the property stabilizes or the investor refinances/sells. This contrasts with banks, which offer long-term amortizing loans (10–30 years) for stabilized assets with lower rates but slower, more rigid underwriting processes.

11. How quickly can I get an initial decision from a private lender?

Many direct private lenders provide an initial indication of interest within 24 hours and a term sheet within 24–48 hours after receiving a brief deal summary. This rapid feedback helps investors gauge feasibility and timeline before committing to full underwriting, unlike banks that may take weeks for preliminary responses.

12. What documentation do private lenders require?

Documentation is often lighter than banks: property details, current loan info, estimated value, rent roll or occupancy status, basic entity docs, and your exit strategy. Some deals are low-doc, relying more on collateral and equity. This streamlined process accelerates approval and funding for time-sensitive real estate transactions.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
47e90aedf92b30adfe7bbc74843f70da
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['finance', 'numbers']. Stichprobe: False
Source Name
Wilshire Quinn Capital, Inc.
Original Summary

<p>Direct Private Lender vs. Traditional Bank: Why Speed Matters in Real Estate Financing In real estate, timing can significantly impact the success of a transaction. Whether an investor is acquiring a property, refinancing an asset, or pursuing a value-add strategy, having the right financing partner can make the difference between moving forward and missing an [...]</p> <p>The post <a href="https://wilshirequinn.com/direct-private-lender-vs-traditional-bank-rea… Private Lender vs. Traditional Bank: Why Speed Matters in Real Estate Financing</a> appeared first on <a href="https://wilshirequinn.com">Wilshire Quinn Capital</a>.</p>

Image URL
https://wilshirequinn.com/wp-content/uploads/2026/09/steptodown.com293080.jpg
Content Hash (SHA-256, erste 32 hex)
d127c8000854c37bfa0f74be1571bb8c
Financing a Multifamily Acquisition: What Investors Need to Know
Image File
Original HTML

Financing a Multifamily Acquisition: What Investors Need to Know

Multifamily assets continue to draw strong investor demand, thanks to their income potential and scalability. However, securing financing quickly enough to compete for the best opportunities requires understanding how acquisition financing works and knowing when a direct private lender may be a better fit than a conventional bank.

Learn More About Multifamily Acquisition Financing: Explore how multifamily acquisition loans work, what financing options are available, and when direct private lending can help investors move quickly on competitive real estate opportunities.

The Multifamily Acquisition Landscape

Multifamily properties, ranging from small apartment buildings to larger complexes, are financed differently depending on their condition, occupancy, and an investor’s overall strategy. Financing options generally fall into a few categories:

- Agency loans (Fannie Mae/Freddie Mac): Designed for stabilized properties, offering competitive interest rates and long-term financing, often up to 30 years. However, approvals typically take 45–90 days and involve standardized underwriting and qualification requirements.

- Traditional bank loans: May offer flexibility for certain borrowers but often require extensive documentation, committee approvals, and strong borrower qualifications. The approval process typically spans 45-60 days.

- Direct private lender bridge loans: Short-term financing, typically 12-month terms, designed for investors who need speed and flexibility. Underwriting is asset-based, making funding possible in as little as 5–7 business days.

Contact Us About Multifamily Financing: Have a multifamily acquisition in mind? Contact our team to discuss your financing needs and explore flexible options for moving forward.

When a Direct Private Lender Makes Sense for Acquisition Financing

A direct private lender is often the right fit for a multifamily acquisition when:

- Speed is the priority , a seller wants a fast, certain close, or the investor is competing against other offers

- The property isn’t fully stabilized , occupancy or income doesn’t yet meet agency or bank standards

- A value-add plan is in place , the investor intends to renovate and reposition the property post-closing

- Flexibility is needed – The transaction involves unique circumstances that may not fit conventional lending guidelines.

Learn How to Qualify for a Multifamily Loan. Understand the key requirements lenders consider, from property and borrower qualifications to financial documentation, and explore financing strategies that can help you prepare for your next multifamily investment.

How the Process Works with Wilshire Quinn Capital

Wilshire Quinn Capital underwrites multifamily acquisition loans primarily based on the property’s value and equity position. Because decisions are made in-house with our own capital, qualified transactions can fund in as little as 5–7 business days. This is a significant advantage over the 45- to 60-day timelines common with agency and conventional bank financing.

A typical process includes:

- Loan submission: Provide property details, requested loan amount, purchase contract, and completed loan application.

- Letter of Intent: Once initial interest is determined, we issue an LOI, outlining the loan amount, rate, and terms.

- Documentation: Provide required items from the needs list on the LOI, including entity, insurance, and financial documentation.

- Due diligence: We order the desktop appraisal and open title and escrow. Once due diligence is complete, loan documents are prepared for execution.

- Closing and funding: Loan documents are signed and funds disbursed.

Positioning Yourself to Move Fast

In multifamily investing, the right opportunity may not wait for the financing process to catch up. Understanding your financing options before you make an offer puts you in a stronger position to act when timing matters. With a direct private lender, investors can move quickly, make competitive offers, and pursue opportunities that may not fit a traditional financing timeline.

Evaluating a multifamily acquisition? Contact Wilshire Quinn Capital to discuss financing options tailored to your transaction.

FAQs

1. What is multifamily acquisition financing?

Multifamily acquisition financing provides capital to purchase apartment buildings, from small complexes to large communities. Options include agency loans (Fannie/Freddie) for stabilized assets, traditional bank loans for qualified borrowers, and direct private lender bridge loans for speed and flexibility on transitional or time-sensitive deals.

2. How fast can a direct private lender fund a multifamily acquisition?

Direct private lenders can issue an LOI within 24–48 hours and fund in 5–7 business days after appraisal and document collection. This contrasts with agency or bank loans, which typically take 45–90 days due to layered underwriting, committee approvals, and extensive documentation requirements.

3. When should I use a private lender instead of a bank for acquisition?

Use a private lender when speed is critical, the property isn’t fully stabilized, you have a value-add plan, or the deal doesn’t fit conventional guidelines. Banks suit long-term, low-cost financing on stabilized assets when you have time for standard underwriting and can meet strict borrower and property criteria.

4. What types of multifamily properties qualify for private acquisition loans?

Private lenders finance small to large multifamily assets (often 5–50+ units) with sufficient equity and a clear exit strategy. They commonly fund transitional properties—those needing renovations, lease-up, or operational improvements—that banks or agencies may reject due to insufficient occupancy or financial seasoning.

5. How much equity or down payment is typically required?

Many private deals target 60–75% loan-to-value, meaning you contribute 25–40% equity. Higher equity improves pricing and approval odds, especially for non-stabilized assets. Exact requirements vary by lender, property condition, and the strength of your business plan and exit strategy for refinancing or sale.

6. What are typical loan terms and interest rates for private acquisitions?

Private acquisition loans are short-term bridges, commonly 6–12 months (sometimes up to 24–36 months), with higher interest rates and fees than banks. The premium pays for speed, flexibility, and asset-based underwriting, with the plan to refinance into lower-cost, long-term financing once the property stabilizes.

7. Can I use a private loan for a value-add or renovation strategy?

Yes. Private lenders often fund value-add acquisitions where you plan renovations, unit upgrades, or operational improvements post-closing. They underwrite based on current value and your business plan, then you refinance conventionally once the property achieves stabilized occupancy and income performance targets.

8. What documentation do I need to start the process?

Typically: property details, purchase contract, requested loan amount, basic entity docs, insurance, and a completed loan application. Some lenders provide an LOI quickly, then request additional financials during due diligence. This streamlined start accelerates approval versus banks requiring extensive upfront documentation.

9. How does underwriting differ from agency or bank loans?

Private lenders use asset-based underwriting focused on property value, equity, and exit strategy, not just borrower credit or income. They can accommodate transitional assets, complex ownership, or limited documentation if collateral and repayment plans are strong, whereas banks rely on standardized criteria and lengthy committee reviews.

10. Can private lenders fund competitive or off-market acquisitions?

Absolutely. In competitive markets, sellers favor buyers with fast, certain closings. Private lenders can issue terms in 24–48 hours and fund in days, giving you an edge over bank-dependent buyers. This speed and certainty can be the difference between winning a deal or losing it to a quicker, more flexible competitor.

[/fusion_text][/fusion_builder_column][/fusion_builder_row][/fusion_builder_container]

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
7fab79696fe529c1dfc244a4a01d8991
Press Eligible
Yes
Press Eligible Reason
QA FAIL (need review): The TARGET incorrectly states that agency and bank financing both take 45–90 days, but the SOURCE specifies 45–90 days for agency loans and 45–60 days for traditional bank loans. This is a partial factual error that needs correction.
Source Name
Wilshire Quinn Capital, Inc.
Original Summary

<p>Financing a Multifamily Acquisition: What Investors Need to Know Multifamily assets continue to draw strong investor demand, thanks to their income potential and scalability. However, securing financing quickly enough to compete for the best opportunities requires understanding how acquisition financing works and knowing when a direct private lender may be a better fit than a [...]</p> <p>The post <a href="https://wilshirequinn.com/financing-multifamily-acquisition/">Financing a Multifamily Acquisition: What Investors Need to Know</a> appeared first on <a href="https://wilshirequinn.com">Wilshire Quinn Capital</a>.</p>

Image URL
https://wilshirequinn.com/wp-content/uploads/2026/09/steptodown.com273044-1.jpg
Content Hash (SHA-256, erste 32 hex)
9edca0ee53d649c4a9f7f20850272569
Multifamily Refinancing: When to Consider a Private Lender
Image File
Original HTML

Multifamily Refinancing: When to Consider a Private Lender

Refinancing a multifamily property is a common step in an investor’s ownership timeline, whether to pull out equity, address a maturing loan, or reposition financing after a renovation. While banks and other conventional financing sources are often the first stop for multifamily refinancing, a private, direct lender is the better fit in some scenarios.

Need Flexible Multifamily Refinancing? Contact Wilshire Quinn Capital to discuss your property, financing goals, and available private lending options.

When Conventional Multifamily Refinancing Falls Short

Agency and bank refinancing programs typically require stabilized occupancy, seasoned financials, and a lengthy underwriting process. That works well for a fully leased, stabilized property, but it can leave gaps in several common situations:

- The property recently underwent renovations and hasn’t fully stabilized yet

- Occupancy or rents are still ramping up

- A loan is maturing, and there isn’t time to complete a lengthy agency process

- The ownership entity or property has a complicating factor that doesn’t fit standard guidelines

How Private Lender Refinancing Works

Wilshire Quinn Capital evaluates multifamily refinance requests primarily based on the property’s current value and equity position, rather than requiring the extensive seasoning and documentation agency lenders typically demand. That asset-based approach allows qualified refinances to fund in as little as 5–7 business days.

Common Reasons Multifamily Owners Refinance with a Private Lender

- Addressing a maturing loan, avoiding a balloon payment when there isn’t time for a conventional refinance

- Cash-out for reinvestment, accessing built-up equity to fund the next acquisition or property improvement

- Bridging to stabilization, short-term refinancing while occupancy and rents continue to ramp up toward agency-eligible levels

- Consolidating debt, replacing multiple financing pieces with a single, streamlined loan

Need Flexible Multifamily Refinancing? Learn more options with Wilshire Quinn Capital to access equity, manage maturing debt, or bridge to stabilization.

What to Expect

After a completed loan application is submitted, Wilshire Quinn Capital typically confirms interest in the scenario within 24 hours. If there’s interest, a term sheet follows shortly after, and once it’s issued, title and escrow open right away. From there, a desktop appraisal is ordered, which usually takes 2–3 days to complete. While that’s underway, the property owner works through the items outlined on the term sheet’s needs list, entity documents, insurance, and other supporting materials. Once everything is collected, loan documents are issued and signed, and the loan is funded

Looking for faster multifamily financing? Explore Wilshire Quinn Capital’s private lending options and submit your loan request today.

Move Faster on Your Next Multifamily Refinance

Multifamily owners don’t have to choose between speed and a lender who understands the asset class. Wilshire Quinn Capital combines fast, in-house decision-making with real underwriting experience on multifamily properties, so you get a clear answer in 24 hours, a defined path to closing, and funding in as little as 5–7 business days.

Ready to explore your options? Reach out to Wilshire Quinn Capital today to get a preliminary quote on your multifamily refinance- no lengthy application process, just a fast, straightforward conversation about your property and your goals.

FAQs

1. When should I consider a private lender for refinancing?

Use a private lender when you need fast funding, your property isn’t stabilized, a loan is maturing soon, or your deal doesn’t fit conventional guidelines. Private lenders underwrite based on asset value and equity, allowing quicker decisions and flexible terms compared to banks or agency programs that require long seasoning and extensive documentation.

2. How quickly can a private multifamily refinance close?

Many private lenders respond within 24 hours and can fund in 5–7 business days after a desktop appraisal and document collection, far faster than typical bank or agency timelines. This speed helps owners avoid balloon payments, seize reinvestment opportunities, or bridge to stabilization without waiting weeks for conventional underwriting and approval processes.

3. What multifamily property types qualify?

Small to mid‑size multifamily assets (often 5–50+ units) with sufficient equity and a clear exit plan. Underwriting emphasizes current value, occupancy trajectory, and sponsor strategy over perfect financials. Private lenders can also consider transitional, renovated, or partially leased properties that conventional programs may reject due to insufficient seasoning or occupancy levels.

4. How much equity is required to refinance privately?

Many private deals target 60–75% loan‑to‑value, meaning you keep 25–40% equity. More equity improves pricing and approval chances, especially for non‑stabilized or transitional properties. Lenders may adjust LTV based on property condition, lease‑up progress, and the strength of your business plan and exit strategy for refinancing into conventional debt.

5. What interest rates and terms are typical?

Private loans usually carry higher rates and fees than banks but offer short terms (often 6–36 months) and flexible structures designed as bridge financing to longer‑term conventional debt. The trade‑off is speed and flexibility: you pay more temporarily to solve timing, stabilization, or documentation issues before refinancing into lower‑cost agency or bank financing.

6. Can I do a cash‑out refinance with a private lender?

Yes. Cash‑out is common to access equity for reinvestment, improvements, or debt consolidation. The amount depends on appraised value, existing debt, and the lender’s maximum LTV. Private lenders can often structure cash‑out deals quickly, even when the property is still renovating or leasing up, provided there is enough equity and a credible exit plan.

7. What if my property is still renovating or leasing up?

That’s an ideal scenario for private refinancing. Lenders can fund based on current value and your plan, then you refinance conventionally once occupancy and rents stabilize. This “bridge to stabilization” approach lets owners avoid balloon payments, complete value‑add work, and position the asset for lower‑cost, long‑term financing once it meets conventional occupancy and financial seasoning requirements.

8. Do private lenders require full financials and tax returns?

Documentation is often lighter. Expect entity docs, insurance, rent roll or occupancy info, and basic property details. Some deals are low‑doc, relying more on collateral and equity. This makes private refinancing attractive when owners lack lengthy tax histories, have complex income, or need to close quickly without assembling the extensive paperwork conventional lenders typically require.

9. What is the typical process and timeline?

Submit a brief request; get a response in ~24 hours. After a term sheet, title opens, a desktop appraisal takes 2–3 days, you provide required items, then docs are signed and funded quickly. The streamlined workflow minimizes delays, allowing owners to meet tight deadlines, avoid default, or capitalize on time‑sensitive investment opportunities without prolonged underwriting.

10. Can I refinance an existing bridge or private loan?

Yes. Borrowers often refinance into another private loan if more time is needed, or into a conventional loan once stabilized. Lenders review collateral value, exit strategy, and serviceability. This flexibility helps owners extend their runway during lease‑up or renovations, then transition to lower‑cost permanent financing when the property meets conventional program requirements and performance targets.

11. What are the main advantages over banks or agency lenders?

Faster decisions and funding, flexible criteria on property condition and borrower profile, asset‑based underwriting focused on equity, and customizable terms tailored to your timeline and goals. Private lenders can accommodate transitional assets, complex ownership structures, or urgent maturities that conventional programs cannot, making them valuable for time‑sensitive or non‑standard multifamily refinancing situations.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
5eb7306f11f9b66111cbe5f6721b6287
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['numbers']. Stichprobe: False
Source Name
Wilshire Quinn Capital, Inc.
Original Summary

<p>Multifamily Refinancing: When to Consider a Private Lender  Refinancing a multifamily property is a common step in an investor's ownership timeline,  whether to pull out equity, address a maturing loan, or reposition financing after a renovation. While banks and other conventional financing sources are often the first stop for multifamily refinancing, a private, direct lender [...]</p> <p>The post <a href="https://wilshirequinn.com/multifamily-refinancing-private-lender/">Mult… Refinancing: When to Consider a Private Lender</a> appeared first on <a href="https://wilshirequinn.com">Wilshire Quinn Capital</a>.</p>

Image URL
https://wilshirequinn.com/wp-content/uploads/2026/09/steptodown.com588119.jpg
Content Hash (SHA-256, erste 32 hex)
798d24f17d88bbc8cc005b40f4ebd8a1
How to Get a Hard Money Loan in California
Image File
Original HTML

How to Get a Hard Money Loan in California

If you’re a real estate investor who needs financing quickly, understanding how to get a hard money loan in California can open up opportunities that may be difficult to finance through a traditional bank.

Hard money loans are commonly used for investment real estate purchases, refinances, cash-out transactions, renovations, and other situations where speed and flexibility are important. Unlike conventional financing, hard money lenders tend to focus more heavily on the property and available equity rather than relying primarily on the borrower’s credit score and debt-to-income ratio.

At Wilshire Quinn Capital, we are a direct portfolio lender providing short-term real estate financing in California and nationwide. Here’s what investors should know before applying for a hard money loan in California.

What Is a Hard Money Loan?

A hard money loan is a short-term loan secured by real estate. These loans are generally provided by private or portfolio lenders rather than traditional banks.

The biggest difference is the underwriting process.

Traditional lenders commonly place significant emphasis on credit history, income, debt-to-income ratios, and other personal financial factors. With asset-based lending, the property’s value and the equity securing the loan play a much larger role.

This can make hard money financing useful when an investor needs to move quickly, is purchasing a property that requires substantial renovations, or has a financing scenario that doesn’t fit conventional lending guidelines.

You can learn more in our guide to what hard money is and how it works.

How to Get a Hard Money Loan in California

Although every lender has its own underwriting guidelines, obtaining a hard money loan generally starts with the property itself.

Here are several of the most important factors to consider.

1. Find a California Hard Money Lender

Your first step is choosing a lender experienced with the type of real estate you’re financing.

Look beyond the advertised interest rate. Investors should also consider:

- Whether the company is a direct lender or broker

- Property types the lender finances

- Loan amounts

- Loan-to-value requirements

- Loan terms

- Origination fees

- Geographic lending areas

- Typical closing times

- Experience with California real estate

Wilshire Quinn is a direct portfolio lender, not a loan broker, with California offices in San Diego, Los Angeles, and San Francisco.

Learn more about working with a California hard money lender.

2. Determine How Much Equity You Have

One of the most important considerations in hard money lending is loan-to-value (LTV).

LTV compares the requested loan amount with the property’s value. Because the real estate serves as collateral for the loan, lenders generally want sufficient equity protecting the transaction.

For example, Wilshire Quinn’s current lending program provides financing of up to 60% LTV. For rehabilitation loans, financing may reach up to 60% of the after-repair value (ARV), subject to additional purchase-price limitations and underwriting requirements.

The exact amount available will depend on the property, transaction, borrower, and overall loan scenario.

3. Know What Type of Property You’re Financing

Hard money financing can potentially be used for many different types of investment real estate.

Wilshire Quinn considers properties including:

- Multifamily properties

- Non-owner-occupied single-family investment properties

- Condominiums

- Retail centers

- Office buildings

- Industrial and warehouse properties

- Hotels and motels

- Healthcare and assisted living facilities

- Mixed-use and special-purpose properties

- Parking garages and lots

Investors can review additional options on our lending options page.

The property’s location, condition, intended use, value, and income potential can all affect how a lender evaluates a transaction.

4. Have a Clear Purpose for the Loan

A lender will also want to understand what you’re trying to accomplish. California real estate investors may seek hard money financing for a:

- Purchase: Quickly acquiring an investment property when conventional financing isn’t practical.

- Refinance: Replacing an existing loan with short-term financing.

- Cash-out refinance: Accessing equity in an investment property for another investment, renovation, or business purpose.

- Rehabilitation project: Purchasing or improving a property that needs significant renovations before it can be stabilized or sold.

- 1031 exchange: Obtaining financing to help complete a time-sensitive real estate transaction associated with an exchange.

- Clearly defining the purpose of your financing helps the lender evaluate whether your scenario fits its lending guidelines.

Before moving forward with a hard money loan, it’s important to understand all the associated costs, including lender points and origination fees. Learn more how lender points affect your total borrowing costs and what to consider when comparing financing options.

5. Prepare Your Exit Strategy

Hard money loans are typically designed as short-term financing, so borrowers should have a realistic plan for repaying the loan.

This is commonly called an exit strategy.

Depending on the investment, an exit strategy might include refinancing through a conventional lender after stabilizing the property, selling a renovated property, selling another asset, or obtaining longer-term financing.

For example, an investor might use a hard money loan to purchase and renovate an apartment property. Once renovations are complete and occupancy improves, the investor could refinance into longer-term financing.

A well-defined exit strategy can be an important part of evaluating whether short-term financing makes sense for a particular investment.

6. Submit Your Property and Loan Information

Once you’ve identified a lender, you’ll need to provide information about your proposed transaction. Depending on the situation, a lender may ask about the:

- Property address

- Property type

- Estimated property value

- Purchase price

- Requested loan amount

- Existing loan balance

- Purpose of the loan

- Renovation plans

- Borrower information

- Proposed exit strategy

Wilshire Quinn allows borrowers to submit a hard money loan request online. Because hard money underwriting focuses heavily on the underlying real estate, the approval process can often move faster than conventional bank financing.

7. Review the Loan Terms Carefully

Before accepting financing, understand the complete cost and structure of the loan.

Important factors include the interest rate, origination points, closing costs, loan term, monthly payment structure, LTV, and any other applicable fees or requirements.

Wilshire Quinn’s current bridge lending parameters include loans from $500,000 to $20 million, terms generally ranging from 3 to 18 months, interest-only payments, and rates currently listed between 9% and 12%. Origination fees generally range from 1 to 5 points, depending on factors such as property, location, LTV, creditworthiness, loan amount, and term.

Loan programs and terms can change, and every transaction is evaluated individually, so borrowers should request current terms for their specific scenario.

How Fast Can You Get a Hard Money Loan in California?

Speed is one of the primary reasons investors consider hard money financing.

A traditional real estate loan can involve extensive underwriting and documentation. That timeline can create problems when an investor needs to close quickly on a competitive property.

Wilshire Quinn currently offers pre-approval in approximately 24 hours and typically funds qualifying transactions in five to seven days.

Actual closing times depend on the property, documentation, valuation, title, transaction complexity, and other underwriting considerations.

For investors competing for California real estate, having access to a lender capable of making decisions quickly can be an important advantage.

Hard money loans can offer real estate investors a faster, more flexible financing option when traditional lending timelines don’t align with their investment goals. Understanding why borrowers choose hard money lenders can help you determine whether this type of financing fits your next deal. Discover why borrowers utilize hard money lenders.

Do You Need Good Credit for a Hard Money Loan?

Not necessarily.

Credit can still be considered, but hard money and bridge lenders generally place greater emphasis on the property’s value and available equity than conventional banks.

This is why hard money financing may be worth exploring for investors whose credit profile, income documentation, or property doesn’t fit conventional underwriting standards.

However, having weaker credit doesn’t automatically mean a borrower will qualify. The entire transaction—including property value, equity, loan amount, exit strategy, and borrower profile—still needs to meet the lender’s underwriting requirements.

How Much Do You Need to Put Down on a Hard Money Loan?

There isn’t one universal down payment requirement for every California hard money loan. Instead, lenders commonly evaluate transactions based on LTV and the amount of equity protecting the loan.

For purchases, this means the borrower may need to contribute a substantial portion of the property’s purchase price. Refinances work differently because existing equity in the property may provide the required collateral.

The exact equity requirement will depend on your lender and transaction.

Understanding your down payment and equity requirements is an important step when planning a hard money loan, especially for time-sensitive real estate investments. Learn more about fast 1031 exchange financing with hard money loans.

What Are the Benefits of a Hard Money Loan?

Hard money financing isn’t the right solution for every real estate transaction, but it can provide several advantages for investors.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
e1786a7ed6fed71c6ed6a683f0c941fb
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: HIGH. Flags: ['finance', 'numbers']. Stichprobe: False
Source Name
Wilshire Quinn Capital, Inc.
Original Summary

<p>  How to Get a Hard Money Loan in California If you’re a real estate investor who needs financing quickly, understanding how to get a hard money loan in California can open up opportunities that may be difficult to finance through a traditional bank. Hard money loans are commonly used for investment real estate purchases, [...]</p> <p>The post <a href="https://wilshirequinn.com/how-to-get-a-hard-money-loan-california/">How to Get a Hard Money Loan in California</a> appeared first on <a href="https://wilshirequinn.com">Wilshire Quinn Capital</a>.</p>

Image URL
https://wilshirequinn.com/wp-content/uploads/2026/10/imgi_14_loan-rates-concept-interest-percentages-charged-by-banks-or-lenders-on-borrowed-money-they.jpg
Content Hash (SHA-256, erste 32 hex)
332f59a8c36c81ffd897045867397c17
Hard Money Loans for Real Estate Investors: A Complete Guide
Image File
Original HTML

Hard Money Loans for Real Estate Investors: A Complete Guide

Real estate investment opportunities don’t always wait for traditional bank financing. Whether you’re purchasing a property to renovate and resell, acquiring an investment property that needs significant repairs, or trying to close on a promising deal quickly, access to capital can make a major difference.

Hard money loans for real estate investors provide short-term financing secured primarily by real estate. Unlike conventional mortgages, which typically involve extensive reviews of income, employment, credit history, and debt-to-income ratios, hard money lenders tend to place greater emphasis on the property, the investment opportunity, and the borrower’s exit strategy.

For experienced and new investors alike, understanding how hard money financing works can help determine whether it is the right tool for a particular real estate project.

Ready to Fund Your Next Real Estate Investment? Connect with us to discuss your real estate investment goals and explore potential financing solutions tailored to your project.

What Are Hard Money Loans for Real Estate Investors?

Hard money loans are short-term, real estate-backed loans commonly used to purchase, renovate, or reposition investment properties.

The property itself serves as collateral for the loan. Because lenders are evaluating an investment rather than primarily financing a borrower’s residence, underwriting can be more focused on factors such as:

- Property value

- Purchase price

- Renovation budget

- After-repair value (ARV)

- Investor experience

- Available cash reserves

- Loan-to-value (LTV)

- Loan-to-cost (LTC)

- Proposed exit strategy

This asset-focused approach can make hard money financing particularly useful when a traditional mortgage doesn’t fit the property’s condition, project timeline, or investment strategy.

How Do Hard Money Loans Work?

The process typically begins when an investor identifies a real estate opportunity and submits information about the property and proposed project to a lender.

The lender evaluates the deal and determines whether it meets its lending criteria. Depending on the project, the lender may consider the property’s current value as well as its expected value after renovations are completed.

If approved, the investor receives financing according to the lender’s terms. For renovation projects, acquisition funds may be provided at closing while rehabilitation funds may be released through draws as work progresses.

Because hard money loans are generally designed as temporary financing, investors should know how they plan to repay the loan before closing.

Common exit strategies include:

- Selling the renovated property

- Refinancing into a conventional mortgage

- Refinancing into a long-term rental loan

- Refinancing into a DSCR loan

- Selling another asset to repay the balance

A well-planned exit strategy is one of the most important components of successful short-term real estate financing.

Need Short-Term Financing for Your Next Real Estate Project? Hard money loans can help real estate investors finance property acquisitions, renovations, and time-sensitive deals. Explore how hard money loans work and learn about potential financing solutions for your next project.

Why Do Real Estate Investors Use Hard Money Loans?

The biggest attraction is often speed and flexibility.

Traditional real estate financing can involve lengthy underwriting and strict borrower and property requirements. Real estate investors frequently operate in situations where waiting several weeks for financing could mean losing an attractive property.

Hard money financing can provide an alternative for investors who need to move quickly.

Faster Closings

Speed can be especially valuable when purchasing distressed properties, competing against cash buyers, or buying properties where the seller wants a quick closing.

Some private and hard money lenders can potentially close loans considerably faster than conventional mortgage lenders.

Financing Properties That Need Renovation

A property requiring substantial repairs may not qualify for certain traditional mortgage programs.

Hard money lenders are accustomed to evaluating properties that require renovations, making this type of financing popular among fix-and-flip investors.

Flexible Underwriting

Hard money lenders typically focus heavily on the real estate transaction itself.

Credit, liquidity, and investor experience can still matter, but lenders may also consider the property’s value, projected ARV, renovation plan, and expected profitability.

Short-Term Financing

Investors may not need a 15- or 30-year mortgage.

If the plan is to purchase a property, renovate it, and sell it within several months, short-term financing may better match the investment strategy.

Explore Flexible Financing for Your Real Estate Investments! Looking for financing that aligns with your investment timeline? Learn more about how these loans work, what lenders consider, and whether this financing approach fits your investment strategy.

Hard Money Loans for Fix-and-Flip Investors

Fix-and-flip projects are one of the most common uses for hard money financing.

An investor purchases an undervalued or distressed property, completes improvements, and attempts to resell it for a profit.

Financing may potentially cover portions of both the acquisition and renovation costs, depending on the lender and deal.

For example, imagine an investor purchases a property for $250,000 and expects to spend $75,000 renovating it.

The total project cost would be:

$250,000 purchase + $75,000 renovation = $325,000

If comparable renovated properties indicate an expected value of $450,000, the projected after-repair value (ARV) would be $450,000.

The lender could use the purchase price, renovation budget, ARV, LTC, and other factors when determining how much it is willing to finance.

What Is After-Repair Value (ARV)?

After-repair value, commonly called ARV, is an estimate of what a property could be worth after planned renovations are completed.

ARV is particularly important for fix-and-flip financing because lenders need to understand the potential value of their collateral after improvements.

Investors may estimate ARV by analyzing recently sold comparable properties with similar characteristics, including:

- Location

- Square footage

- Bedrooms and bathrooms

- Lot size

- Property condition

- Renovation quality

- Age and style of the home

Overestimating ARV can significantly affect a project’s profitability, so investors should use realistic comparable sales and conservative assumptions.

Understand ARV and Prepare for Your Hard Money Loan! Read more about how property value, renovation plans, and comparable sales can influence your financing options and help you prepare for the hard money loan qualification process.

Understanding Loan-to-Value (LTV)

Loan-to-value compares the loan amount with the value of the property.

The basic calculation is:

LTV = Loan Amount ÷ Property Value × 100

For example, if a property is valued at $400,000 and the loan amount is $280,000:

$280,000 ÷ $400,000 = 70% LTV

Lenders use LTV to evaluate how much exposure they have relative to the value of the collateral.

Understanding Loan-to-Cost (LTC)

Loan-to-cost compares the amount being financed with the project’s total cost.

The calculation is:

LTC = Loan Amount ÷ Total Project Cost × 100

Suppose an investor’s acquisition and renovation costs total $300,000 and a lender provides $240,000.

The LTC would be:

$240,000 ÷ $300,000 = 80% LTC

Understanding both LTC and LTV can help investors compare financing offers more effectively.

Can You Get 100% Financing With a Hard Money Loan?

In certain circumstances, some lenders may offer financing covering a very high percentage of a project’s costs.

However, 100% financing should not be assumed.

Eligibility can depend on several factors, including the strength of the deal, investor experience, purchase price, renovation budget, ARV, credit profile, and available reserves.

Even when a lender finances 100% of certain acquisition or renovation expenses, investors may still need money for closing costs, lender fees, interest, insurance, taxes, unexpected repairs, and other expenses.

Investors should evaluate the complete cost of financing rather than focusing only on the percentage of the purchase price being financed.

Understand Hard Money Loan Requirements Before You Invest! Wondering whether a hard money loan can cover your real estate project’s costs? Learn about the key factors lenders consider, including property value, renovation budgets, investor experience, and available reserves.

How Much Do Hard Money Loans Cost?

Hard money loans generally cost more than traditional mortgage financing.

Because lenders are providing short-term financing for investment projects that may involve additional risk, borrowers can encounter higher interest rates and fees.

Potential expenses include:

- Interest

- Origination points

- Underwriting fees

- Appraisal or valuation expenses

- Closing costs

- Inspection fees

- Construction draw fees

- Extension fees

- Other lender or third-party charges

Some hard money loans use interest-only payments, which can help investors manage cash flow during a renovation. However, the outstanding principal must still be repaid according to the loan terms.

Investors should calculate financing costs when determining the potential ROI of a project.

Hard Money Loans vs. Traditional Bank Loans

The primary difference comes down to the purpose, underwriting process, speed, and cost of financing.

Traditional mortgages generally offer lower interest rates and longer repayment periods. However, they often require more extensive documentation and may have stricter property-condition requirements.

Hard money loans generally provide:

Faster underwriting: Deals may be evaluated more quickly.

Shorter terms: Financing is intended for temporary investment needs.
Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
572ae1bdc5a6ae871cfb6070da07fb28
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: HIGH. Flags: ['finance', 'numbers']. Stichprobe: False
Source Name
Wilshire Quinn Capital, Inc.
Original Summary

<p>Hard Money Loans for Real Estate Investors: A Complete Guide Real estate investment opportunities don't always wait for traditional bank financing. Whether you're purchasing a property to renovate and resell, acquiring an investment property that needs significant repairs, or trying to close on a promising deal quickly, access to capital can make a major difference. [...]</p> <p>The post <a href="https://wilshirequinn.com/hard-money-loans-for-real-estate/">Hard Money Loans for Real Estate Investors: A Complete Guide</a> appeared first on <a href="https://wilshirequinn.com">Wilshire Quinn Capital</a>.</p>

Image URL
https://wilshirequinn.com/wp-content/uploads/2026/06/steptodown.com487350.jpg
Content Hash (SHA-256, erste 32 hex)
42fbc62495ac6cd89e2c510171920176