Parking Garage Financing: A Guide for Commercial Real Estate Investors
Image File
Original HTML

Parking Garage Financing: A Guide for Commercial Real Estate Investors

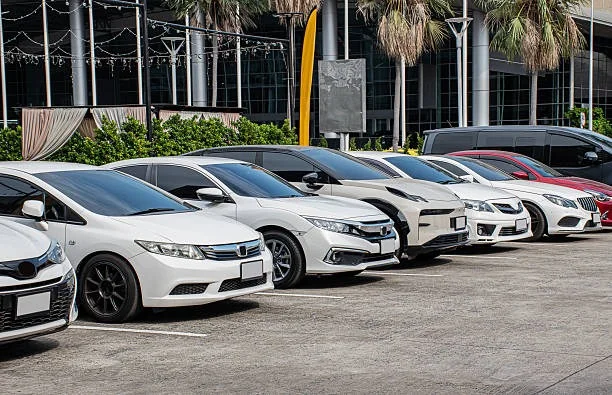
Parking garages can be valuable commercial real estate assets, particularly in downtown districts, mixed-use developments, medical centers, airports, entertainment districts, universities, and other areas where parking demand is high.

Purchasing, constructing, renovating, or refinancing a parking structure can also require significant capital. Parking garage financing can provide commercial property owners, developers, and real estate investors with funding for these specialized properties.

Depending on the transaction, financing options may include commercial real estate loans, construction financing, bridge loans, and private money loans.

What Is a Parking Garage?

Parking garage financing is commercial real estate financing used to purchase, construct, renovate, or refinance a parking garage, parking structure, or qualifying parking facility.

Unlike financing for a residential garage, commercial parking garage loans typically involve an investment or income-producing property. Lenders may therefore consider the property’s value, location, revenue, borrower experience, loan-to-value ratio, and the borrower’s overall investment strategy.

Parking garage financing may be used for:

- Purchasing an existing parking garage

- Constructing a new parking structure

- Renovating an existing garage

- Refinancing a parking facility

- Acquiring parking associated with a larger commercial development

- Funding improvements before obtaining permanent financing

- Completing a time-sensitive commercial real estate acquisition

The appropriate financing structure will depend on the property, borrower, requested loan amount, and intended use of the funds.

Whether you’re purchasing an existing parking facility, renovating a parking structure, or refinancing a commercial property, choosing the right financing option is essential to your investment strategy. Explore the available financing considerations and learn what to evaluate before moving forward.

How Does Parking Garage Financing Work?

The financing process typically begins with a lender evaluating the property and proposed transaction.

Traditional commercial lenders may focus heavily on historical operating income, borrower credit, financial statements, debt-service coverage, and the property’s current performance.

Private commercial real estate lenders may approach underwriting differently. While borrower qualifications remain important, greater emphasis may be placed on the underlying real estate, borrower equity, property value, loan-to-value ratio, and exit strategy.

This can make private financing an option when an investor needs to close quickly or a transaction does not fit conventional bank lending requirements.

What Can Parking Garage Loans Be Used For?

Parking Garage Acquisition

Commercial real estate investors may use parking garage financing to acquire an existing parking facility.

Parking garages can generate revenue from several sources, including:

- Hourly parking

- Daily parking

- Monthly parking passes

- Reserved parking

- Event parking

- Commercial agreements

- Contracts with nearby businesses

A lender may consider the property’s current revenue, operating expenses, location, condition, value, and potential future performance.

Parking Garage Construction Financing

Constructing a parking structure can involve significant development expenses.

Costs may include land preparation, engineering, concrete, structural components, labor, permitting, lighting, elevators, security systems, payment technology, drainage, access controls, and other infrastructure.

Construction financing may provide funding as different phases of a project are completed.

Because new construction can carry additional risk, lenders may evaluate the development team’s experience, construction budget, permits, timeline, projected property value, surrounding development, and intended use of the garage.

Parking Garage Renovation Financing

Older parking structures may require improvements to remain safe, functional, and competitive.

Parking garage financing may potentially help fund:

- Concrete repairs

- Structural improvements

- Lighting upgrades

- Security systems

- Access control systems

- Parking payment technology

- Drainage improvements

- Elevator repairs

- New signage

- Restriping

- Parking space reconfiguration

- General property improvements

Renovation financing can also be part of a value-add investment strategy designed to improve the property’s operations, income, or overall value.

Parking Garage Refinancing

Owners may seek financing to refinance an existing parking garage loan.

Refinancing can potentially help an owner replace maturing debt, restructure an existing loan, obtain additional capital, or transition from short-term financing into a longer-term loan.

For investors using bridge financing, refinancing may also serve as an exit strategy after improvements have been completed or the property’s operations have stabilized.

Parking Garage Bridge Loans

A commercial bridge loan is short-term financing designed to provide capital until a borrower obtains longer-term financing or completes another planned exit.

Parking garage bridge loans may be useful when:

- A property must close quickly

- Existing financing is approaching maturity

- The garage requires renovations

- The property is not yet stabilized

- Conventional financing would take too long

- An investor plans to refinance after improving the property

- A time-sensitive acquisition opportunity becomes available

For competitive commercial real estate transactions, the ability to secure financing within the required timeframe can be particularly important.

Private Money Loans for Parking Garages

Private money loans may provide an alternative to conventional commercial financing.

Instead of relying exclusively on traditional underwriting requirements, private lenders may place greater emphasis on the collateral and equity involved in the transaction.

Factors commonly considered can include:

- Property value

- Requested loan amount

- Loan-to-value ratio

- Borrower experience

- Property condition

- Location

- Existing revenue

- Projected revenue

- Construction or renovation costs

- Borrower equity

- Exit strategy

Every commercial real estate transaction is different, so borrowers should discuss the details of their parking property directly with a lender.

Private money loans may offer a flexible financing option for investors purchasing, refinancing, or improving commercial parking facilities. Explore Wilshire Quinn’s lending options to learn more about financing solutions for your commercial real estate investment.

What Do Lenders Look for When Financing a Parking Garage?

Property Value and Loan-to-Value Ratio

Because the commercial property typically serves as collateral, its value can play an important role in underwriting.

The loan-to-value ratio (LTV) compares the amount being borrowed with the value of the property.

For example, if a parking garage is valued at $5 million and an investor requests a $3 million loan, the LTV would be 60%.

Generally, lower leverage provides the lender with a larger equity cushion.

Location and Parking Demand

Location can have a significant effect on the performance and value of a parking facility.

Parking demand may be influenced by proximity to:

- Office buildings

- Hospitals

- Hotels

- Airports

- Universities

- Sports venues

- Entertainment districts

- Shopping centers

- Apartment developments

- Public transportation

- Downtown business districts

A garage near several consistent sources of parking demand may have substantially different economics from a parking facility in a less active location.

Parking Garage Revenue

For an operating parking facility, lenders may evaluate historical and current revenue.

Income can potentially come from hourly parking, daily parking, monthly contracts, reserved spaces, event parking, valet operations, advertising, and commercial agreements.

Operating expenses are equally important. Property taxes, insurance, maintenance, management, security, staffing, repairs, and technology expenses can all affect net operating income.

Understanding how financing speed can affect an investment decision is essential when evaluating commercial real estate opportunities. Learn why speed matters in private money lending and how timely financing can support time-sensitive real estate transactions.

Borrower Experience

Commercial real estate experience may be particularly important when a transaction involves new construction or substantial renovations.

Lenders may consider the borrower’s experience with commercial properties, real estate development, parking facilities, or similar investment projects.

Exit Strategy

An exit strategy explains how a borrower intends to repay short-term financing.

Potential exit strategies may include:

- Refinancing into permanent financing

- Selling the property

- Completing renovations and refinancing

- Stabilizing property operations before obtaining conventional financing

A clear and realistic exit strategy can be especially important when seeking bridge or private money financing.

How to Get a Parking Garage Loan

Before approaching a lender, investors should determine how much financing they need and gather information about the property and proposed transaction.

Borrowers may need to provide:

- Property address and type

- Purchase price, if applicable

- Requested loan amount

- Current or projected property value

- Existing debt

- Historical or current operating income

- Renovation or construction budget

- Borrower experience

- Intended use of loan proceeds

- Proposed exit strategy

The lender can then review the transaction to determine whether it meets its lending criteria.

Parking Garage Financing vs. Residential Garage Financing

Commercial parking garage financing should not be confused with financing used to construct or renovate a garage at a residential property.
Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
91c4f551602e7abfcea831307144cec5
Press Eligible
Yes
Press Eligible Reason
QA FAIL (need review): Target incorrectly states 'The guide cites five use cases' for bridge loans; the source lists six use cases. This is a factual/counting error.
Source Name
Wilshire Quinn Capital, Inc.
Original Summary

<p>Parking Garage Financing: A Guide for Commercial Real Estate Investors Parking garages can be valuable commercial real estate assets, particularly in downtown districts, mixed-use developments, medical centers, airports, entertainment districts, universities, and other areas where parking demand is high. Purchasing, constructing, renovating, or refinancing a parking structure can also require significant capital. Parking garage financing [...]</p> <p>The post <a href="https://wilshirequinn.com/parking-garage-financing/">Parking Garage Financing: A Guide for Commercial Real Estate Investors</a> appeared first on <a href="https://wilshirequinn.com">Wilshire Quinn Capital</a>.</p>

Image URL
https://wilshirequinn.com/wp-content/uploads/2026/10/imgi_23_many-car-parked-in-a-row.jpg
Content Hash (SHA-256, erste 32 hex)
fc80062f35f01f5fec7c51047e3e64b6
How to Find Private Money Lenders for Real Estate
Image File
Original HTML

How to Find Private Money Lenders for Real Estate

If you are purchasing an investment property, refinancing an existing property, or need capital for a time-sensitive real estate opportunity, knowing how to find private money lenders can give you access to financing outside traditional banks.

Private money lending can be especially valuable for real estate investors who need faster decisions, flexible loan structures, or financing for properties that may not fit conventional lending guidelines. Instead of focusing exclusively on the same requirements as traditional banks, private lenders may place greater emphasis on the property, available equity, loan-to-value ratio, and overall strength of the transaction.

Looking for the Right Private Money Lender for Your Next Real Estate Deal? Connect with us to discuss your investment goals and explore potential financing solutions for your next real estate project.

But where do you actually find a reputable private lender?

In this guide, we explain how to find private money lenders for real estate, what to look for when comparing lenders, and how investors can prepare before requesting financing.=

What Is a Private Money Lender?

A private money lender provides financing outside the traditional banking system. Depending on the lender, capital may come from an individual investor, a group of investors, or a private lending company that specializes in real estate loans.

Private real estate loans are commonly used for transactions such as:

- Investment property purchases

- Commercial real estate

- Multifamily properties

- Bridge financing

- Property rehabilitation

- Refinancing

- Cash-out refinancing

- Partnership or ownership buyouts

- Time-sensitive acquisitions

Because private lenders can have different underwriting requirements than conventional banks, they may be able to evaluate transactions that require greater flexibility or faster execution.

How to Find Private Money Lenders

There isn’t one single place to find every private lender. The best approach is usually to combine online research, professional referrals, networking, and direct conversations with established private lending companies.

Here are several ways to begin your search.

1. Search for Private Money Lenders Online

One of the easiest ways to start is through online research.

Investors frequently search terms such as private money lenders, private lenders for real estate, commercial private money lenders, and private money lenders near me.

Don’t choose a lender simply because it appears at the top of a search result. Visit the lender’s website and determine what types of properties and transactions it finances.

Look for information about the lender’s:

- Loan programs

- Property types

- Geographic lending area

- Loan amounts

- Lending experience

- Closing process

- Contact information

An established lender should make it relatively easy to understand the types of transactions it considers.

2. Work With a Direct Private Lender

Understanding whether you are dealing with a direct lender or a broker can be important.

A broker typically attempts to place your loan with another funding source. A direct private lender uses its own lending platform or capital resources to evaluate and fund qualifying transactions.

Working directly with a lender can potentially simplify communication because you are speaking with the organization responsible for evaluating the financing request.

Wilshire Quinn Capital is a direct portfolio lender specializing in real estate-backed financing. The company evaluates investment opportunities across multiple property types and can provide financing solutions for transactions that require speed and flexibility.

3. Ask Real Estate Professionals for Referrals

Your existing real estate network can also be an excellent source of private lender recommendations.

Consider speaking with:

- Commercial real estate brokers

- Real estate agents

- Property investors

- Property managers

- Attorneys

- CPAs

- Escrow professionals

- Contractors

- Other real estate professionals

Professionals who regularly work with investors often encounter private lenders during acquisitions, refinances, renovations, and other transactions.

A referral can help narrow your search, but you should still independently evaluate the lender and its proposed terms.

4. Attend Real Estate Investment Events

Networking remains an effective method for finding private capital.

Real estate investment associations, industry conferences, local investor meetings, and commercial real estate events provide opportunities to meet lenders and borrowers who have experience with private financing.

Rather than simply asking, “Who will lend me money?” focus on developing relationships.

Explain the types of properties you invest in, the markets you target, and the financing situations you typically encounter. Building a professional network can create financing opportunities for both your current transaction and future investments.

Discover Flexible Financing Options for Your Real Estate Investments! Learn how private money loans work, what to consider when evaluating loan terms, and how to prepare for your next investment.

5. Use Professional Networking Platforms

Online professional networks can expand your search beyond local events.

Platforms such as LinkedIn can help investors identify private lending companies, commercial lenders, mortgage professionals, real estate investors, and other people involved in real estate finance.

Real estate investment communities and professional groups can also be useful for obtaining referrals and learning about lenders that other investors have worked with.

However, always perform your own due diligence before providing financial information or entering into a lending agreement.

6. Ask Other Real Estate Investors

Experienced real estate investors have often worked with multiple financing sources.

If you know investors purchasing commercial, multifamily, rental, or other investment properties, ask which lenders they have successfully worked with.

Useful questions include:

Did the lender close when promised?

Were the loan terms clearly communicated?

Was the lender responsive throughout the transaction?

Would you use the lender again?

The answers can reveal much more about the lender than simply comparing advertised interest rates.

7. Look for Lenders Experienced With Your Property Type

Not every private lender finances every type of property.

A lender specializing in single-family fix-and-flip properties, for example, may not be the best option for a borrower seeking financing for a large commercial or multifamily acquisition.

Before submitting a loan request, determine whether the lender has experience financing your particular type of transaction.

At Wilshire Quinn Capital, financing may be available for qualifying real estate transactions involving residential investment, multifamily, office, retail, mixed-use, and other commercial properties.

Find the Right Private Lending Solution for Your Property Investment! Whether you’re investing in residential, multifamily, or commercial real estate, explore how Wilshire Quinn Capital’s private lending solutions may help support your investment goals.

How to Choose a Private Money Lender

Learning how to find private money lenders is only the first step. You also need to determine which lender is appropriate for your transaction.

Avoid evaluating a private loan based solely on the advertised interest rate.

Consider the complete financing structure, including the lender’s experience, fees, loan term, closing requirements, repayment structure, prepayment provisions, and ability to execute within your required timeline.

Experience

Find out how long the lender has been operating and whether it regularly finances transactions similar to yours.

An experienced lender should understand common challenges associated with real estate acquisitions, refinancing, investment properties, and commercial transactions.

Speed

Private financing is often used when timing matters.

Ask the lender how quickly it can evaluate your request and whether it has the resources to meet your closing deadline.

Transparency

A reputable lender should clearly explain the major terms and costs associated with the proposed loan.

Make sure you understand the interest rate, points, fees, loan term, collateral requirements, and repayment conditions before proceeding.

Ability to Fund

A financing proposal has little value if the lender cannot execute.

Ask about the lender’s funding process and determine whether it is actually responsible for providing the capital or intends to place the loan elsewhere.

What Do Private Money Lenders Look For?

Private lenders have their own underwriting criteria, but real estate-focused lenders commonly evaluate the strength of the underlying transaction.

Factors may include:

Property value: What is the current value of the real estate securing the loan?

Equity: How much equity does the borrower have in the property?

Loan-to-value ratio: How large is the requested loan relative to the property’s value?

Property type: Is the property consistent with the lender’s lending criteria?

Exit strategy: How does the borrower expect to repay the loan?

Borrower experience: Does the borrower have experience completing similar transactions?

Transaction timeline: How quickly does the financing need to close?

Providing accurate information from the beginning can help a lender evaluate the opportunity more efficiently.

Understand What Private Money Lenders Look for Before Applying! Knowing how lenders evaluate property value, equity, loan-to-value ratios, and exit strategies can help you prepare for your next real estate financing request. Learn how private money loans work and what to expect when seeking funding for your investment property.

What Should You Prepare Before Contacting a Private Lender?

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
1269453f8f73d7e57441945a562f9cba
Press Eligible
Yes
Press Eligible Reason
Informational article about real estate financing and private lending, with promotional content for a lending company.
Source Name
Wilshire Quinn Capital, Inc.
Original Summary

<p>How to Find Private Money Lenders for Real Estate If you are purchasing an investment property, refinancing an existing property, or need capital for a time-sensitive real estate opportunity, knowing how to find private money lenders can give you access to financing outside traditional banks. Private money lending can be especially valuable for real estate [...]</p> <p>The post <a href="https://wilshirequinn.com/how-to-find-private-money-lenders/">How to Find Private Money Lenders for Real Estate</a> appeared first on <a href="https://wilshirequinn.com">Wilshire Quinn Capital</a>.</p>

Image URL
https://wilshirequinn.com/wp-content/uploads/2026/10/imgi_50_save-money-for-home-cost.jpg
Content Hash (SHA-256, erste 32 hex)
d315a7fbfad2e9a63b1743d4cd159eff
How to Get a Hard Money Loan in San Francisco
Original HTML

Parking Garage Financing: A Guide for Commercial Real Estate Investors

Parking garages can be valuable commercial real estate assets, particularly in downtown districts, mixed-use developments, medical centers, airports, entertainment districts, universities, and other areas where parking demand is high.

Purchasing, constructing, renovating, or refinancing a parking structure can also require significant capital. Parking garage financing can provide commercial property owners, developers, and real estate investors with funding for these specialized properties.

Depending on the transaction, financing options may include commercial real estate loans, construction financing, bridge loans, and private money loans.

What Is Parking Garage Financing?

Parking garage financing is commercial real estate financing used to purchase, construct, renovate, or refinance a parking garage, parking structure, or qualifying parking facility.

Unlike financing for a residential garage, commercial parking garage loans typically involve an investment or income-producing property. Lenders may therefore consider the property’s value, location, revenue, borrower experience, loan-to-value ratio, and the borrower’s overall investment strategy.

Parking garage financing may be used for:

- Purchasing an existing parking garage

- Constructing a new parking structure

- Renovating an existing garage

- Refinancing a parking facility

- Acquiring parking associated with a larger commercial development

- Funding improvements before obtaining permanent financing

- Completing a time-sensitive commercial real estate acquisition

The appropriate financing structure will depend on the property, borrower, requested loan amount, and intended use of the funds.

Whether you’re purchasing an existing parking facility, renovating a parking structure, or refinancing a commercial property, choosing the right financing option is essential to your investment strategy. Explore the available financing considerations and learn what to evaluate before moving forward.

How Does Parking Garage Financing Work?

The financing process typically begins with a lender evaluating the property and proposed transaction.

Traditional commercial lenders may focus heavily on historical operating income, borrower credit, financial statements, debt-service coverage, and the property’s current performance.

Private commercial real estate lenders may approach underwriting differently. While borrower qualifications remain important, greater emphasis may be placed on the underlying real estate, borrower equity, property value, loan-to-value ratio, and exit strategy.

This can make private financing an option when an investor needs to close quickly or a transaction does not fit conventional bank lending requirements.

What Can Parking Garage Loans Be Used For?

Parking Garage Acquisition

Commercial real estate investors may use parking garage financing to acquire an existing parking facility.

Parking garages can generate revenue from several sources, including:

- Hourly parking

- Daily parking

- Monthly parking passes

- Reserved parking

- Event parking

- Commercial agreements

- Contracts with nearby businesses

A lender may consider the property’s current revenue, operating expenses, location, condition, value, and potential future performance.

Parking Garage Construction Financing

Constructing a parking structure can involve significant development expenses.

Costs may include land preparation, engineering, concrete, structural components, labor, permitting, lighting, elevators, security systems, payment technology, drainage, access controls, and other infrastructure.

Construction financing may provide funding as different phases of a project are completed.

Because new construction can carry additional risk, lenders may evaluate the development team’s experience, construction budget, permits, timeline, projected property value, surrounding development, and intended use of the garage.

Parking Garage Renovation Financing

Older parking structures may require improvements to remain safe, functional, and competitive.

Parking garage financing may potentially help fund:

- Concrete repairs

- Structural improvements

- Lighting upgrades

- Security systems

- Access control systems

- Parking payment technology

- Drainage improvements

- Elevator repairs

- New signage

- Restriping

- Parking space reconfiguration

- General property improvements

Renovation financing can also be part of a value-add investment strategy designed to improve the property’s operations, income, or overall value.

Parking Garage Refinancing

Owners may seek financing to refinance an existing parking garage loan.

Refinancing can potentially help an owner replace maturing debt, restructure an existing loan, obtain additional capital, or transition from short-term financing into a longer-term loan.

For investors using bridge financing, refinancing may also serve as an exit strategy after improvements have been completed or the property’s operations have stabilized.

Parking Garage Bridge Loans

A commercial bridge loan is short-term financing designed to provide capital until a borrower obtains longer-term financing or completes another planned exit.

Parking garage bridge loans may be useful when:

- A property must close quickly

- Existing financing is approaching maturity

- The garage requires renovations

- The property is not yet stabilized

- Conventional financing would take too long

- An investor plans to refinance after improving the property

- A time-sensitive acquisition opportunity becomes available

For competitive commercial real estate transactions, the ability to secure financing within the required timeframe can be particularly important.

Private Money Loans for Parking Garages

Private money loans may provide an alternative to conventional commercial financing.

Instead of relying exclusively on traditional underwriting requirements, private lenders may place greater emphasis on the collateral and equity involved in the transaction.

Factors commonly considered can include:

- Property value

- Requested loan amount

- Loan-to-value ratio

- Borrower experience

- Property condition

- Location

- Existing revenue

- Projected revenue

- Construction or renovation costs

- Borrower equity

- Exit strategy

Every commercial real estate transaction is different, so borrowers should discuss the details of their parking property directly with a lender.

Private money loans may offer a flexible financing option for investors purchasing, refinancing, or improving commercial parking facilities. Explore Wilshire Quinn’s lending options to learn more about financing solutions for your commercial real estate investment.

What Do Lenders Look for When Financing a Parking Garage?

Property Value and Loan-to-Value Ratio

Because the commercial property typically serves as collateral, its value can play an important role in underwriting.

The loan-to-value ratio (LTV) compares the amount being borrowed with the value of the property.

For example, if a parking garage is valued at $5 million and an investor requests a $3 million loan, the LTV would be 60%.

Generally, lower leverage provides the lender with a larger equity cushion.

Location and Parking Demand

Location can have a significant effect on the performance and value of a parking facility.

Parking demand may be influenced by proximity to:

- Office buildings

- Hospitals

- Hotels

- Airports

- Universities

- Sports venues

- Entertainment districts

- Shopping centers

- Apartment developments

- Public transportation

- Downtown business districts

A garage near several consistent sources of parking demand may have substantially different economics from a parking facility in a less active location.

Parking Garage Revenue

For an operating parking facility, lenders may evaluate historical and current revenue.

Income can potentially come from hourly parking, daily parking, monthly contracts, reserved spaces, event parking, valet operations, advertising, and commercial agreements.

Operating expenses are equally important. Property taxes, insurance, maintenance, management, security, staffing, repairs, and technology expenses can all affect net operating income.

Understanding how financing speed can affect an investment decision is essential when evaluating commercial real estate opportunities. Learn why speed matters in private money lending and how timely financing can support time-sensitive real estate transactions.

Borrower Experience

Commercial real estate experience may be particularly important when a transaction involves new construction or substantial renovations.

Lenders may consider the borrower’s experience with commercial properties, real estate development, parking facilities, or similar investment projects.

Exit Strategy

An exit strategy explains how a borrower intends to repay short-term financing.

Potential exit strategies may include:

- Refinancing into permanent financing

- Selling the property

- Completing renovations and refinancing

- Stabilizing property operations before obtaining conventional financing

A clear and realistic exit strategy can be especially important when seeking bridge or private money financing.

How to Get a Parking Garage Loan

Before approaching a lender, investors should determine how much financing they need and gather information about the property and proposed transaction.

Borrowers may need to provide:

- Property address and type

- Purchase price, if applicable

- Requested loan amount

- Current or projected property value

- Existing debt

- Historical or current operating income

- Renovation or construction budget

- Borrower experience

- Intended use of loan proceeds

- Proposed exit strategy

The lender can then review the transaction to determine whether it meets its lending criteria.

Parking Garage Financing vs.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
261332387fdb26a7ace4b2d1356fe871
Press Eligible
Yes
Press Eligible Reason
QA FAIL (need review): The target contains an unsupported factual claim: 'Five loan types cover acquisition, construction, renovation and refinancing.' The source lists only four financing options (commercial real estate loans, construction financing, bridge loans, and private money loans) and never mentions 'five.'
Source Name
Wilshire Quinn Capital, Inc.
Original Summary

<p>Parking Garage Financing: A Guide for Commercial Real Estate Investors Parking garages can be valuable commercial real estate assets, particularly in downtown districts, mixed-use developments, medical centers, airports, entertainment districts, universities, and other areas where parking demand is high. Purchasing, constructing, renovating, or refinancing a parking structure can also require significant capital. Parking garage [...]</p> <p>The post <a href="https://wilshirequinn.com/how-to-get-a-hard-money-loan-in-san-francisco… to Get a Hard Money Loan in San Francisco</a> appeared first on <a href="https://wilshirequinn.com">Wilshire Quinn Capital</a>.</p>

Content Hash (SHA-256, erste 32 hex)
c3b6cc9d67a8028ea25bc1664d4dd861
Beyond CMS-0057-F compliance: How payers can reduce prior authorization friction before the 2027 deadline
Image File
Original HTML

As health payers in the US prepare to comply with the CMS-0057-F (CMS Interoperability and Prior Authorization Final Rule) by January 2027, the administrative friction may remain for both payers and providers well after implementation.

While the regulation focuses on transparency of PA requirements, including coverage discovery, procedure-specific policy guidelines, and data transfer between providers and payers, it addresses only part of the problem. Another limitation is that, for now, the compliance requirement applies only to specific categories of CMS-regulated payers, rather than to all health plans. In addition, adoption is not mandatory for all providers, except for certain providers eligible for the Merit-based Incentive Payment System (MIPS).

The readiness gap is already visible

The provider and payer communities are not fully prepared for the upcoming deadline, according to WEDI’s 3rd Interoperability and Prior Authorization Survey.1 WEDI’s findings show that provider confidence in meeting the 2027 deadline has fallen to 25%, while the providers’ intent to implement also declined to 33% in February 2026 from 44% in October 2025.

From the payer’s perspective, the survey shows that 10% of payers haven’t even started interoperability-specific work. Moreover, only 16% of payers are currently around 100% complete ahead of the January 2027 deadline.

The top three challenges facing payers are implementation and compliance costs, operational readiness, and execution gaps.

Even after implementation, the administrative burden associated with PA decision-making is likely to persist on the payer side. This is especially true for complex cases, which often require evaluation of multiple clinical documents and additional evidence-based follow-ups. These interactions typically occur through multiple channels, leading to delays and incomplete responses from providers. As a result, this ongoing friction can continue to drive dissatisfaction among both providers and members.

Three dimensions for improving prior authorization

Capgemini sees three mutually reinforcing dimensions for prior authorization transformation: interoperability, automation, and collaboration. Together, they can help transform prior authorization from an administrative checkpoint into a more timely, transparent, and clinically informed exchange.

1. Interoperability: Payers should view CMS-0057-F compliance as the foundation for broader prior authorization rather than the final destination. Coverage discovery, documentation requirements, request submission, status tracking, requests for additional information, and decisions should connect seamlessly with the systems where payer and provider teams already work.

2. Automate administrative review: Responsible AI can streamline prior authorization intake by identifying administrative gaps early and communicating them to providers before the request moves further into review. Document AI and computer vision can analyze incoming materials, identify the requested service, extract diagnoses and clinical observations, detect missing pages, and map supporting evidence to FHIR resources or payer data models.

Evidence-based AI review: Responsible AI can strengthen prior authorization reviews by evaluating clinical documentation against applicable medical policies and coverage criteria. AI agents can generate evidence-based recommendations supported by a clear rationale, documented findings, and an auditable trail of how each recommendation was developed.

Eligible procedures that meet predefined, payer-approved criteria may be automatically approved, allowing clinicians to focus on complex cases that require medical judgment, while retaining oversight and final decision-making authority.

PHI and PII protection should be built into the workflow, including data minimization, de-identification, or tokenization where feasible, access controls, audit logging, and safeguards to ensure information is protected before it is processed by a generative AI model.

3. Payer-provider collaboration: When a prior authorization request does not initially meet authorization requirements, payers should engage providers early rather than defaulting immediately to a denial. Structured collaboration between payers and providers can help clarify clinical intent, resolve documentation gaps, and support more accurate authorization decisions. This active dialogue can also help identify the most appropriate pathway to care.

Such collaboration helps clarify missing clinical information, identify supporting documentation, and, when appropriate, explore alternative evidence-based treatment pathways through specialist-led clinical consultation. A modification-over-denial approach helps providers align requests with clinical guidelines while allowing payers to maintain standards for medical necessity, quality, and cost-management.

This elevates prior authorization from a purely administrative process to a clinically informed exchange in which patient-specific provider insights are considered alongside evidence-based guidelines and payer policies.

What payer leaders should do now

As health plans prepare for the 2026 and 2027 CMS-0057-F milestones, the focus should extend beyond implementation activities. Actions taken now can help establish the operational, clinical, and governance foundations needed for long-term success.

Right now, payer leaders should:

Create one roadmap across the 2026 operational requirements and 2027 API requirements

Define the target operating model, including decision rights, exception paths, clinical oversight, and third-party responsibilities

Digitize and govern medical policies so requirements, evidence, and denial reasons are applied consistently

Prioritize provider journeys from discovery through follow-up

Measure outcomes beyond go-live, including cycle time, administrative touchpoints, avoidable denials, provider experience, and member access.

Turning a mandate into measurable results

The payers that lead in this next phase will not be those that simply expose the required APIs, but the organizations that turn interoperability into operational intelligence, responsible automation, and stronger clinical collaboration.

Capgemini can help health payers assess their CMS-0057-F readiness. This includes modernizing interoperability architecture, redesigning utilization management workflows, and applying responsible AI to reduce administrative burden. Clinical oversight and regulatory confidence remain built into the process. The next step is to define how the mandate can serve as the foundation for a practical, sequenced transformation roadmap with measurable business outcomes.

Start with a readiness-to-transformation roadmap

Ready to move from CMS-0057-F compliance planning to prior authorization transformation? Contact Capgemini for a readiness assessment and executive roadmap workshop. Together, we can define a practical transformation path spanning interoperability, operating model modernization, responsible AI, and provider experience.

Troy has nearly two decades of experience transforming the operating capabilities of businesses in the healthcare ecosystem. As the Global Industry Lead for Healthcare, he uses his expertise to develop insights and solutions that weave together business models, technology, data, and operations. As a thought leader he works with payers, providers, retail health, technology firms, startups, and PE/VC firms.

I agree to Capgemini collecting and processing my personal data to allow me to receive information on Capgemini services. For further information, please see our Privacy Notice. .

Page title

Expert title

Page URL

Slide to submit

Use right arrow keys to slide, or drag right with your finger. When you reach 100 percent, the form is submitted. If you use a screen reader or VoiceOver, double-tap this button to submit the form.

Slide to submit

Thank you for your submission. We will be in touch with you soon!

We are sorry, the form submission failed. Please try again.

Sanjay Pawar

Global Insurance Industry, Health Insurance Portfolio Lead

Sanjay Pawar leads Capgemini’s global Health Insurance Portfolio, driving strategy and coordinating across Capgemini services to deliver thought leadership and GTM offerings in the health insurance domain. Sanjay brings over 20 years of expertise in crafting and delivering business-technology solutions.

I agree to Capgemini collecting and processing my personal data to allow me to receive information on Capgemini services. For further information, please see our Privacy Notice. .

Page title

Expert title

Page URL

Slide to submit

Use right arrow keys to slide, or drag right with your finger. When you reach 100 percent, the form is submitted. If you use a screen reader or VoiceOver, double-tap this button to submit the form.

Slide to submit

Thank you for your submission. We will be in touch with you soon!

We are sorry, the form submission failed. Please try again.

Siva K G

Global Insurance Industry, Health Insurance Domain Expert

Siva has around two decades of experience across the healthcare payer value chain and brings deep expertise in product management, consulting, and capability development. He drives Capgemini’s strategy, thought leadership, and go-to-market initiatives for the healthcare payer sector.

I agree to Capgemini collecting and processing my personal data to allow me to receive information on Capgemini services. For further information, please see our Privacy Notice. .

Page title

Expert title

Page URL

Slide to submit

Use right arrow keys to slide, or drag right with your finger. When you reach 100 percent, the form is submitted. If you use a screen reader or VoiceOver, double-tap this button to submit the form.

Slide to submit

Thank you for your submission. We will be in touch with you soon!

We are sorry, the form submission failed. Please try again.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
9f04f86325e67b8900cdcf9219c1bc3d
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['numbers']. Stichprobe: False
Source Name
Capgemini Newsroom
Original Summary

<p>Beyond CMS-0057-F compliance: How payers can reduce prior authorization friction before the 2027 deadline</p>
<p>The post <a href="https://www.capgemini.com/insights/expert-perspectives/beyond-cms-0057-… CMS-0057-F compliance: How payers can reduce prior authorization friction before the 2027 deadline</a> appeared first on <a href="https://www.capgemini.com">Capgemini</a>.</p&gt;

Image URL
https://www.capgemini.com/wp-content/uploads/2026/09/Health_Blog_capcom_banner_2880by1800.jpg
Source Node
Content Hash (SHA-256, erste 32 hex)
4a6130a016d023723720c9e5dd9ffbbb
Scale AI with trusted data
Image File
Original HTML

Organizations have invested heavily in artificial intelligence, generative AI and, increasingly, AI agents. Early results have demonstrated what’s possible; from accelerating analysis and content creation to automating complex workflows and improving customer experiences.

For many organizations, these successes remain confined to pilots, individual functions, or tightly controlled use cases.

The question around AI is no longer ‘Does it work?‘. It has new evolved into a new, more urgent, one: ‘Why is it so difficult to scale AI across the enterprise?’

The answer often has less to do with the sophistication of the model, and more to do with the information surrounding it. AI needs timely, trusted, and contextualized data to produce reliable outcomes. However, if that foundation is fragmented, outdated, or poorly understood, even the most advanced AI solution will struggle to deliver meaningful business value.

Capgemini has consistently observed three data challenges that stand between AI experimentation and enterprise-wide impact across financial services and other highly regulated industries.

1. Data fragmentation: AI cannot use what it cannot reach

Most organizations don’t yet have one single, unified source of business information. Instead, critical data is distributed across operational systems, cloud platforms, data warehouses, departmental applications, and organizational silos. Each system may serve an important purpose, yet collectively they can create a fragmented view of the enterprise.

Consider an AI agent designed to support a financial services customer: to provide relevant guidance, the agent may need access to account information, transaction history, service interactions, product eligibility, risk indicators, and regulatory requirements. If those inputs reside in disconnected environments, the agent is essentially operating blind.

The result is an AI experience that may be fast, but is not necessarily well informed.

To really scale AI, organizations must connect data across these boundaries while maintaining the security, privacy, and governance standards their businesses demand.

2. Data stagnation: Yesterday’s information cannot drive real-time action

Too often data is available without being truly usable.

Valuable operational information can be trapped in systems of record or moved through traditional batch processes. By the time it reaches an analytics or AI platform, it may have been copied multiple times and delayed or separated from the business context that gave it meaning.

That delay causes issues. An AI system making recommendations based on yesterday’s information may miss a change in customer behavior, an emerging operational issue, or a new risk signal today. When decisions need to happen in the moment, stale data becomes a business liability.

Organizations need a more fluid connection between where data is created, and the platforms where intelligence is applied. Bringing AI closer to current operational data can enable faster decisions, more relevant interactions, and automation that responds to what’s happening now, versus the last data refresh.

3. Semantic fragmentation: The same word can mean different things

Connecting data is only part of the challenge. Organizations must also agree on what that data means.

Customers, products, or risk events may be defined differently across business units. The same KPI may be calculated in several different ways, depending on the team, platform, or report using it.

People often navigate these inconsistencies through experience and institutional knowledge, yet AI cannot do so reliably without a shared semantic foundation.

When business definitions conflict, AI-generated insights become harder to validate and difficult to trust. Teams waste time debating numbers, while automation risks applying the wrong interpretations at scale.

A consistent business language provides AI with the context necessary to reason more effectively, and makes outputs easier for employees, customers, regulators, and other stakeholders to understand.

The next frontier: AI grounded in the business

The future of enterprise AI will depend on an organization’s ability to connect three essential elements:

Trusted enterprise data

Business context and semantics

Intelligent agents and automation

The organizations leading the next era of AI will not necessarily be those with the most models. They’ll be the ones that make AI work securely and responsibly with the data that actually runs their business.

And achieving this requires more than isolated technology implementation. It calls for a coordinated approach to data architecture, cloud modernization, governance, security, operating models, and AI adoption. Together, these capabilities can turn promising experiments into a trusted part of everyday operations.

Capgemini has the capability to help organizations manage this process, combining deep industry knowledge, data and cloud expertise, and an understanding of enterprise transformation to create AI foundations built for scale.

Connect with Capgemini

Whether your organization is working to scale AI, modernize legacy platforms, activate operational data, or prepare agent-driven business processes – the path forward begins with a trusted data foundation.

Connect with Capgemini to discuss how your organization can turn enterprise data into intelligent, responsible, and scalable action.

Authors

Renjith Sreekumar

Head of Oracle Cloud & AI CoE, Financial Services

Renjith Sreekumar is a technology and transformation leader helping Financial Services organizations build AI-ready enterprises through data modernization, intelligent operations, cloud transformation, and agentic AI.

I agree to Capgemini collecting and processing my personal data to allow me to receive information on Capgemini services. For further information, please see our Privacy Notice. .

Page title

Expert title

Page URL

Slide to submit

Use right arrow keys to slide, or drag right with your finger. When you reach 100 percent, the form is submitted. If you use a screen reader or VoiceOver, double-tap this button to submit the form.

Slide to submit

Thank you for your submission. We will be in touch with you soon!

We are sorry, the form submission failed. Please try again.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
94cf9bfd4fb4b0762e33bc130f15286a
Press Eligible
Yes
Press Eligible Reason
Enterprise AI and trusted data strategy for businesses, with substantive technology insights.
Source Name
Capgemini Newsroom
Original Summary

<p>Scaling AI requires more than powerful models. Discover how trusted data, real-time access, and shared business context help organizations move from AI pilots to secure, enterprise-wide impact.</p>
<p>The post <a href="https://www.capgemini.com/insights/expert-perspectives/scale-ai-with-tr… AI with trusted data</a> appeared first on <a href="https://www.capgemini.com">Capgemini</a>.</p&gt;

Image URL
https://www.capgemini.com/wp-content/uploads/2026/10/ai_infrastructure-AdobeStock_478334581_Telenor.jpg
Source Node
Content Hash (SHA-256, erste 32 hex)
001a126e75c03ee15851fcbf01669a6e
To reach sustainable AI, businesses must speak a common language
Image File
Original HTML

As AI models become more complex, their environmental, resource, and economic impacts are growing. Organizations are aiming to meet the moment with standardized frameworks and coalition-building.

Generative AI has rapidly shown the ability to improve business operations, delivering greater productivity and performance. But as companies reap the benefits of these new tools, many are confronting another reality: AI’s steep environmental cost.

Powering AI at scale requires an enormous amount of electricity, with large Gen AI models consuming up to 4,600 times more energy than traditional models. And the demand for more power and AI compute is only rising. In a high-adoption scenario with many companies deploying complex AI models, such as agentic AI, electricity use is projected to rise by a factor of 24.4.1 This would lead to higher carbon emissions, strains on resources like water, and negative community impacts. Temperatures in neighborhoods around data centers are generally higher by 2°C than equivalent neighborhoods without this infrastructure.

For businesses adopting AI, this prompts a key question: how can I deploy AI at scale, while mitigating its environmental impact?

Driving value through internal collaboration

Companies must seek to align on AI across their internal teams, as perspectives can vary widely across company functions and AI-related decisions are often made in silos. Consequently, organizations may optimize their AI use for certain objectives, while unintentionally making it harder to achieve others.

To scale AI sustainably, organizations need clear communication and a common shared framework based on standardized metrics covering environmental, resource, and economic impacts and objectives. Creating this shared language enables effective decision-making across all aspects of a business.

Take transport and logistics. AI is being increasingly used in this sector to optimize operations, but its value depends on where, when, and how it is deployed, as competing priorities must be balanced. Business teams may focus on reducing delivery times and lowering fuels costs, while sustainability teams want to cut emissions, and technology teams prioritize model performance. To optimize these different objectives, a common measurement framework can help quantify value by considering costs, resource use, environmental impact, and increased efficiency.

Creating industry-wide alignment

While action at company level is vital to managing the relationship between business value, resource consumption, cost, and environmental impact, industry-wide standards are also critical. Isolated measures that address hardware efficiency, model efficiency, or grid improvements alone cannot mitigate Gen AI’s impact. Achieving this will require coordination across the AI value chain, from power generation to operational efficiency, to the product lifecycle.

Governments and businesses are already stepping in to minimize AI impact and align AI development with net-zero goals. The International Telecommunication Union (ITU) recently published guidelines for assessing the environmental impact of AI systems (ITU-T L.1801) and other efforts are underway. One French-led initiative, the Coalition for Sustainable AI, brings together the UN Environment Programme, ITU, Capgemini, and many other companies and organizations to address AI’s impact. Coalition members are committed to reaching the UN Sustainable Development Goals and UN Agenda 30, leveraging AI tools to support climate action and environmental protection.

Clément Desroches et al., “Exploring the sustainable scaling of AI dilemma: A projective study of corporations’ AI environmental impacts,” Capgemini Invent, https://arxiv.org/pdf/2501.14334

Jérôme Coignard is CTO of frog France, leading a team of creative technologists that turn ideas into scalable solutions through technology, data, and AI. With over 25 years of experience, he helps organizations drive innovation, reinvent business models, and unlock growth through emerging technologies. He is also a strong advocate for Sustainable AI, helping organizations scale AI responsibly while balancing innovation with sustainability.

Shalini Rajeev

Director, Sustainability CoE, Capgemini

Shalini leads the Sustainable Gen AI stream within the Sustainability CoE, driving innovation and sustainable business value for clients. With over 24 years of experience spanning strategic consulting, delivery leadership, pre-sales and solutioning, sustainability, and generative AI, she helps organizations accelerate transformation and maximize value from emerging technologies.

Vincent de Montalivet

Senior Director – Sustainability Transformation, Data & AI Portfolio, Capgemini

Vincent leads the Global Sustainability Practice for Data & AI Portfolio along with North America Sustainability GTM.

With a background in Sustainability Strategy, Engineering and Architecture, Vincent has been instrumental in driving sustainability digitalization efforts and transformation

programs within major organizations across industries while ensuring tangible business outcomes.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
f4fe1b96aa44ced17241c1d7bac2db9b
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['numbers']. Stichprobe: False
Source Name
Capgemini Newsroom
Original Summary

<p>As AI models become more complex, their environmental, resource, and economic impacts are growing. Organizations are aiming to meet the moment with standardized frameworks and coalition-building.</p>
<p>The post <a href="https://www.capgemini.com/insights/expert-perspectives/to-reach-sustain… reach sustainable AI, businesses must speak a common language </a> appeared first on <a href="https://www.capgemini.com">Capgemini</a>.</p&gt;

Image URL
https://www.capgemini.com/wp-content/uploads/2026/09/Webpreview-Sustainable-AI-blog2.jpg
Source Node
Content Hash (SHA-256, erste 32 hex)
596bd7c0cdd55ff1b8b0e12ada3c8bf6
How AI is reshaping holiday shopping in 2026
Image File
Original HTML

Most retailers follow a familiar holiday playbook. In 2026, with AI playing a meaningful role on both sides of the shopping equation for the first time, they may need to rewrite it, especially since consumers seem to be moving faster than retailers.

New research reveals that 65% of consumers plan to use AI for at least one part of their holiday shopping in 2026, but only 8% of retailers say they’re ready to deliver.

So what will it take to win the season?

Retailers need to master both sides of the equation: shaping demand and responding to it. The perfect recommendation means little if the product is unavailable or fulfillment is too slow. At the same time, even the best-run operation cannot capture a sale if the brand never enters the shopper’s consideration set.

Connecting those two sides is where the opportunity lies — and this year, the stakes are particularly high. As consumers rely more heavily on AI, the habits, brand preferences and expectations established now could shape how consumers, and the AI assistants acting on their behalf, shop for years to come.

Shaping demand: AI recommendations are becoming the new gift guides

“What should I buy Dad for Christmas?” is increasingly a question for an AI assistant rather than a sibling. With a bit of back-and-forth, that shopping assistant can often deliver a better answer by evaluating a wider set of options, cross-referencing sources such as consumer reviews and expert roundups, and applying personal preferences and constraints. AI shopping assistants can help consumers discover gift ideas, compare products, and identify the best-fit option based on factors such as the recipient, occasion, budget, brand preferences, size, and availability.

Using AI in this way changes what it means for brands to be discoverable. Recent research shows that a full 74% of shoppers use AI for product discovery, but less than 3% of the citations used by LLMs were brand-owned pages.

For brands and retailers, this shift raises the stakes for how they show up in the digital ecosystem beyond their own website. It also opens the door for smaller, less familiar brands with a strong digital presence and greater visibility in AI recommendations.

While optimizing an owned website for AI product discovery remains a necessary first step, it is no longer sufficient. Winning in AI discovery requires brands to build a consistent and credible presence across the broader digital ecosystem, ensuring AI systems can find, interpret, and trust information from sources such as publishers, buying guides, consumer reviews, and online communities. This broader approach, often referred to as generative engine optimization (GEO), focuses on improving the clarity, consistency, and credibility of the information AI systems use when generating recommendations.

The practical starting point is to map the AI discovery journey just as brands once mapped the search journey. Identify the questions consumers are likely to ask, test whether the brand appears for different needs and personas, examine which competitors are being recommended instead, and trace the sources shaping those answers. Then brands can work to close the gaps, strengthening product information on their own sites while earning credible reviews, editorial coverage, and authentic conversation in the third-party environments AI relies upon.

Gift-giving is emotional. LLMs are rational.

When it comes to gift-giving, we often say, “It’s the thought that counts.” But as shoppers increasingly turn to AI for help, it’s the feeling behind the thought that may be tougher to replicate.

Designed to weigh objective criteria like price, quality, and availability to find the “best” choice, AI models often fall short when it comes to the symbolism, and connection that accompany a gift. For example, Lipton tea may be the best everyday choice when Mom goes to the grocery store, but perhaps not the ideal gift for her. A highly rated digital kitchen scale may be a lovely gift for an avid baker, but come off as an inadvertent swipe for someone on a diet.

For brands, this puts a premium on two things AI cannot determine from product specifications alone: shopper intent and brand identity. Intention means giving AI enough context to understand not just what a shopper is looking for, but who they are buying for and why. Brand identity provides the emotional layer, the associations, values and meaning that make one choice feel more personal or appropriate than another.

Brands with a strong identity have an opportunity to not only land on the short list of AI recommendations, but also “win the override” when they don’t. Unlike traditional measures of satisfaction or loyalty, the Conscious Override Rate (COR) measures how often shoppers deliberately choose a preferred brand over an AI’s top recommendation, reflecting the strength of brand loyalty and preference beyond algorithmic influence.

That makes this holiday season particularly consequential. As shoppers use AI for product discovery at meaningful scale for the first time, brands are competing not simply for this year’s purchase, but also influencing long-term preference.

Meeting demand: The experience is only as good as the operation behind it.

AI can help retailers create a better path from discovery to purchase, but winning the recommendation is only half the battle. A highly relevant recommendation means little if the product is unavailable, the delivery promise is unreliable or unexpected fulfillment costs appear at checkout.

AI can play an important role in removing these points of friction. But while consumers are willing to use AI, they aren’t necessarily looking for an “AI experience.” They want AI to be felt, not seen—working behind the scenes to make shopping easier and more relevant.

That starts before the purchase. AI-powered demand planning can help anticipate not only what consumers will buy, but where and when demand will materialize. The bigger opportunity is to connect those signals of customer intent directly to operational decisions—from forecasting and allocation to replenishment and last-mile capacity.

Fulfillment then turns inventory into experience. Once a shopper is ready to buy, AI helps retailers determine which location should fulfill the order, through which channel and at what speed and cost. That requires connecting inventory visibility with warehouse, store, transportation and last-mile capacity through an intelligent control tower.

And the journey does not end at the doorstep. Holiday shopping inevitably becomes holiday returns, making reverse logistics another critical capability. Retailers can leverage AI to coordinate returns or troubleshoot questions; on the operation side, intelligent solutions can also be used to automate tasks like inspecting merchandise and restocking.

The bottom line: It takes two to win.

This holiday season, AI may be rewriting the playbook. But winning still comes down to one equation: create the demand, then be ready to deliver.

Webinar

Beyond the basket

How top grocers link foot traffic, execution and loyalty

Mark Ruston is Capgemini’s Global Retail Lead with 22+ years in consulting and transformation. He helps Tier 1 retailers and CPGs bridge strategy and execution, driving growth and measurable outcomes. With global experience and deep supply chain expertise, Mark champions AI to boost productivity and reduce waste — positioning operations as a key driver of consumer experience.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
c6092e5b79fdc6fc7408cd2102784fd3
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['numbers']. Stichprobe: False
Source Name
Capgemini Newsroom
Original Summary

<p>Explore how AI is changing holiday shopping in 2026, from product discovery and gift recommendations to demand forecasting, fulfillment and returns.</p>
<p>The post <a href="https://www.capgemini.com/insights/expert-perspectives/how-ai-is-reshap… AI is reshaping holiday shopping in 2026</a> appeared first on <a href="https://www.capgemini.com">Capgemini</a>.</p&gt;

Image URL
https://www.capgemini.com/wp-content/uploads/2026/10/Holiday_Shopping_2026_WP.jpg
Source Node
Content Hash (SHA-256, erste 32 hex)
4d62c9b27bd4b95c1fa4e76ccbaf24c4
How to bring greater confidence to PLM investments
Image File
Original HTML

A data-driven approach to capturing ROI from investments and realizing value with Siemens Teamcenter

Organizations invest millions in product lifecycle management platforms, engineering tools, and digital transformation initiatives. Yet one challenge remains common across industries: how do you objectively measure whether those investments are delivering value?

For many enterprises, investment decisions are still influenced by varying assumptions, inconsistent business cases, and limited visibility into realized outcomes. The result is uncertainty around prioritization, difficulty comparing initiatives, and limited confidence that funding is directed toward the highest-value opportunities. As organizations continue to invest in PLM platforms such as Siemens Teamcenter and broader digital enterprise capabilities, the challenge often shifts from identifying improvement opportunities to objectively quantifying and comparing their business value. While these initiatives can improve collaboration, process efficiency, data quality, and product lifecycle visibility, organizations frequently lack a consistent methodology to evaluate expected benefits and validate realized outcomes across competing investments.

To address this challenge, Capgemini collaborated with the client on a new approach to investment prioritization and value realization: the “Return on Investment Business Value Framework”, or “ROI-BVF”.

The challenge: making investment decisions more objective

Product development organizations continuously evaluate opportunities to improve engineering efficiency, accelerate innovation, and modernize technology platforms. However, establishing a direct connection between investment decisions and measurable business outcomes is often difficult. For organizations managing large PLM environments such as Teamcenter, these challenges become even more complex. Investment decisions extend beyond whether to invest and often involve determining where to invest across platform upgrades, new capabilities, process improvements, and Siemens Xcelerator solutions. Leaders must evaluate options such as Teamcenter, Teamcenter X, and other complementary capabilities, each with different business impacts, implementation efforts, and expected returns, making objective value assessment critical for effective prioritization.

Many organizations face similar obstacles:

Limited visibility into how investments translate into business outcomes

Difficulty comparing initiatives using a consistent framework

Funding decisions based on subjective inputs rather than fact-based analysis

Challenges validating whether expected benefits were actually achieved after implementation

Without a standard way to assess value, organizations risk allocating resources based on assumptions rather than measurable impact.

Introducing ROI-BVF: a structured approach to measuring value

ROI-BVF – Return-on-Investment-Business Value Framework – provides a consistent methodology for quantifying business value and translating operational improvements into financial outcomes. The framework creates a common language for evaluating investments, comparing opportunities, and validating value realization. ROI-BVF was designed not only to calculate ROI, but to establish a common language between business and technology stakeholders. By creating a consistent methodology for measuring value, organizations can make more objective investment decisions, align on expected outcomes, and track realized benefits over time.

The framework focuses on both tangible and intangible value dimensions.

Tangible value includes:

Time savings

Cost reduction

Capacity release

Intangible value includes:

Increased transparency

Greater decision confidence

Improved user experience

Together, these dimensions enable organizations to make more consistent and data-driven investment decisions while creating a repeatable model that can scale across portfolios and programs. ROI-BVF provides a common methodology for evaluating value across a broad range of Siemens-enabled transformation initiatives, from Teamcenter deployments and engineering change management improvements to digital thread, quality management, requirements management, and workflow automation capabilities.

Connecting operational work to measurable ROI

A key differentiator of the ROI-BVF methodology is its ability to create a credible link between day-to-day work and financial outcomes.

The approach begins by establishing a detailed baseline of how work is performed today. Roles are mapped to core activities, effort levels are quantified, and operational data is collected to understand how time is spent across the product development lifecycle.

From there, improvement initiatives are connected to specific roles and activities. Expected efficiency gains are validated with subject matter experts and translated into measurable business impact. Finally, labor costs and resource utilization metrics are applied to convert those improvements into financial value.

This process enables transparent, comparable, and decision-ready insights that can support funding decisions before implementation and validate realized value after delivery. Additionally, this same baseline allows clients to compare Siemens product options against one another on a like-for-like basis – for example, whether migrating from core Teamcenter to Teamcenter X delivers enough incremental value to justify the change.

Supporting Lean Portfolio Management

ROI-BVF is designed to strengthen portfolio governance by introducing data-driven business cases during the analysis phase of Lean Portfolio Management.

By providing a consistent framework for evaluating initiatives, organizations can:

Build structured business cases

Quantify expected value using a common methodology

Compare initiatives objectively

Improve prioritization decisions across portfolios

This helps organizations move more confidently from idea generation to funding decisions while improving overall investment discipline.

Creating resilience in a changing environment

Large transformation programs rarely remain static. Business priorities shift, technologies evolve, and project scopes change over time.

ROI-BVF addresses this reality by maintaining a stable measurement baseline. Even when programs pivot, organizations can continue measuring value consistently by mapping changes back to the same role and task-based foundation.

This creates traceability, supports auditability, and ensures that ROI calculations remain credible throughout the lifecycle of an initiative.

A scalable model that can extend across programs and business domains

The result is greater confidence that resources are being directed toward the opportunities that deliver the greatest business impact.

Looking ahead

As organizations continue adopting Siemens Xcelerator solutions such as Teamcenter, Polarion, Mendix, and broader digital enterprise capabilities, the ability to objectively quantify value becomes increasingly important. With Capgemini, our heavy machinery client is able to combine operational insights with financial outcomes, and ROI-BVF provides a practical path toward more transparent investment decisions and stronger value realization.

Overall, the framework represents more than a new measurement tool – it establishes a foundation for making product development investments more measurable, comparable, and actionable across the enterprise.

*ROI BVF is a methodology and framework established by Capgemini Invent North America. For more information, please reach out to us.

Author

Mahsa Najafabadi

Senior Engineer Consultant, Capgemini Invent

Mahsa Najafabadi is a Consultant at Capgemini specializing in PLM‑driven digital transformation and enterprise value realization. With a Systems Engineering background and over eight years of cross‑industry and consulting experience within complex product organizations, she partners with PLM and engineering leaders to quantify ROI, strategically align PLM investments, and deliver measurable business outcomes through Business Value Frameworks.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
194788ae8b0ce983d25da36c61cb226b
Press Eligible
Yes
Press Eligible Reason
Enterprise-focused article on a framework for measuring ROI from PLM and digital transformation investments.
Source Name
Capgemini Newsroom
Original Summary

<p>Discover how Capgemini’s ROI-BVF framework helps organizations objectively measure the value of PLM investments, prioritize initiatives, and link operational improvements in Siemens Teamcenter to measurable business outcomes.</p>
<p>The post <a href="https://www.capgemini.com/insights/expert-perspectives/how-to-bring-gre… to bring greater confidence to PLM investments</a> appeared first on <a href="https://www.capgemini.com">Capgemini</a>.</p&gt;

Image URL
https://www.capgemini.com/wp-content/uploads/2026/05/Siemens-DotCom_Banner_2880X1800-Option1-1.jpg
Source Node
Content Hash (SHA-256, erste 32 hex)
3f2ad3b4e7465bddf571d62a592cac8b
Understanding the Cyber Resilience Act: From regulatory compliance to product cyber resilience
Image File
Original HTML

The Cyber Resilience Act (CRA) is becoming a defining pillar of the European cybersecurity regulatory landscape, alongside NIS 2, DORA, and the Cybersecurity Act 2. Yet the CRA marks a fundamental shift. While many existing frameworks focus primarily on securing the infrastructures and operations of regulated entities, the CRA extends cybersecurity obligations directly to digital products across their full lifecycle.

While Cyber Awareness Month 2026 highlights the need to stay ahead of evolving cyber risks, the CRA reinforces a fundamental principle: resilience starts with security built into digital products from the outset, and sustained throughout their lifecycle.

Its scope is broad. Manufacturers, importers, and distributors will all need to demonstrate that products with digital elements placed on the European market meet defined cybersecurity expectations, regardless of organizational size. From connected consumer devices to critical technologies such as smartphones, printers, VPNs, and firewalls, the CRA will shape a market representing several hundred billion euros.

The first obligations begin September 2026, including mandatory reporting of incidents and actively exploited vulnerabilities to the competent authorities. Non-compliance may lead to financial penalties of up to €15 million and, in the most severe cases, the withdrawal of non-compliant products from the market.

For organizations, the CRA is not a remote compliance topic. This is a strategic, operational, and commercial imperative. It requires companies to embed cybersecurity into product strategy, engineering practices, supplier governance, and post-market operations. Capgemini has identified five priority challenges that organizations should address now.

1. Turning a crowded cyber regulatory agenda into an integrated roadmap

The CRA adds another layer of complexity to an already demanding cybersecurity regulatory agenda. Organizations already mobilized around NIS 2, DORA, or sector-specific cyber obligations must now address cybersecurity not only at enterprise infrastructure level, but also at product level.

In a context of overlapping regulations, the challenge is to avoid fragmented compliance initiatives. Organizations need a coherent, sequenced roadmap that limits duplication, rationalizes investment, and creates synergies across regulatory programs. This requires strong alignment between Legal, IT, Business, Product, and Cybersecurity teams around a single integrated cyber compliance program.

2. Leveraging existing standards to accelerate CRA readiness

By applying cybersecurity requirements at product level, the CRA builds on an existing landscape of industrial standards and sector-specific frameworks. In many cases, products already designed in line with recognized standards may partially meet CRA expectations by design.

The first priority is therefore to map current standards, certifications, and regulatory obligations against CRA requirements. This allows organizations to identify genuine gaps, focus resources on the products and capabilities that require action, and build a pragmatic compliance trajectory rather than starting from a blank page.

3. Clarifying accountability across the value chain

CRA obligations vary according to the role performed in the value chain — manufacturer, importer, or distributor — and the criticality of the product concerned.

Manufacturers carry primary responsibility for secure-by-design development, risk assessment, vulnerability handling, security updates, and compliance documentation.

Importers must verify that products placed on the European market are compliant and cooperate with authorities when incidents or vulnerabilities arise.

Distributors are subject to due diligence obligations, particularly in relation to product conformity, vulnerability identification, and incident escalation.

This distinction becomes more complex when a single organization plays several roles at once. A detailed product portfolio analysis is essential to determine the applicable obligations, certification routes, responsible entities, and interactions with competent authorities.

4. Extending product cyber resilience across the supply chain

The CRA reinforces shared responsibility across the digital product supply chain. The definition of manufacturer may include organizations that design, develop, commission, or market products under their own name, including products made available free of charge.

Organizations must therefore establish mechanisms to:

Identify and manage risks arising from third-party suppliers, software components, and embedded technologies.

Monitor vulnerabilities continuously and ensure timely remediation across the product lifecycle.

Coordinate incident reporting, evidence collection, and information sharing across suppliers and partners.

This often requires a review of contractual frameworks to clarify cybersecurity responsibilities, notification duties, remediation expectations, and regulatory evidence requirements, as in other sectorial standards such as ISO 21434 in the automotive sector. Supply chain governance will increasingly become a core component of CRA compliance.

5. Industrializing vulnerability management as a product capability

Under the CRA, the ability to identify, assess, report, and remediate vulnerabilities within strict timeframes is a critical product capability. Organizations will need industrialized processes and tooling to centralize vulnerability detection, including code analysis, automated scanning, dependency monitoring, and Software Bills of Materials (SBOMs).

These capabilities must make it possible to assess business and security impact, prioritize remediation based on product criticality and exposure, and provide the evidence needed to demonstrate compliance.

Beyond detection, organizations must orchestrate patch deployment, maintain traceability, and integrate vulnerability management into DevSecOps and operational processes. Product cyber resilience will depend on the ability to move from periodic compliance controls to continuous, evidence-based risk management.

Anticipate rather than react

The Cyber Resilience Act is more than a new compliance framework because it signals a structural shift in how organizations must approach cybersecurity: not as a downstream control, but as an inherent attribute of digital products and the ecosystems that support them.

With the first milestones approaching and significant sanctions in view, organizations should act now to assess exposure, clarify accountability, mobilize product and security teams, and embed CRA requirements into their operating model. Those that anticipate the regulation will not only reduce compliance risk; they will strengthen trust, resilience, and competitiveness in the European digital market.

Authors

Laurianne Brua

Digital Trust & Security Senior Consultant, Capgemini Invent

Laurianne contributes to Capgemini Invent’s Compliance Compass offering. She helps organizations define and implement their cybersecurity and cyber compliance strategies.

Olivier Gellez

Strategy & GRC Squad Leader, Capgemini CIS

Olivier leads the Governance, Risk, and Compliance (GRC) practice within Capgemini CIS Cybersecurity. He is responsible for structuring service offerings, supporting pre-sales activities, and guiding clients across their governance, risk management, and compliance needs.

Nicolas Hory

Head of France Cyber Center of Excellence, Capgemini

Nicolas leads Capgemini France’s Cyber Center of Excellence (CoE) for connected products and connectivity security (4G/5G). He works closely with clients to identify and address their cybersecurity needs, supporting them across the entire cybersecurity lifecycle of their connected solutions.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
6d389bb90d5ca57b52bdbab5672de71a
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: HIGH. Flags: ['finance', 'legal']. Stichprobe: False
Source Name
Capgemini Newsroom
Original Summary

<p>The Cyber Resilience Act (CRA) is becoming a defining pillar of the European cybersecurity regulatory landscape, alongside NIS 2, DORA, and the Cybersecurity Act 2. </p>
<p>The post <a href="https://www.capgemini.com/insights/expert-perspectives/understanding-th… the Cyber Resilience Act: From regulatory compliance to product cyber resilience</a> appeared first on <a href="https://www.capgemini.com">Capgemini</a>.</p&gt;

Image URL
https://www.capgemini.com/wp-content/uploads/2026/10/Everest-leader-preview-banner-2025.jpg
Source Node
Content Hash (SHA-256, erste 32 hex)
c9b4711dd778b055f06d054d50d14882
Intelligent Finance Operations Hub: Building a unified finance intelligence platform for banking & insurance
Image File
Original HTML

Most banking and insurance organizations have successfully modernized their core financial processing platforms using solutions such as Oracle Fusion ERP, policy administration systems, claims platforms, payment systems, treasury platforms, and banking applications.

These systems effectively perform their intended role as systems of record, executing and recording financial transactions across:

General ledger

Accounts payable and receivable

Claims processing

Billing and collections

Payments and treasury

Lending and deposits

Regulatory reporting

However, the information required to manage finance operations does not reside in a single system. Critical financial and operational data often remains distributed across multiple platforms, data warehouses, documents, operational databases, and cloud environments.

As a result, finance teams often struggle to:

Gain a unified view of financial and operational performance

Reconcile transactions across multiple systems

Identify risks and exceptions before they impact the business

Operationalize AI within finance processes

Accelerate decision-making across finance, risk, and operations

The Intelligent Finance Operations Hub transforms fragmented finance operations into a continuously intelligent operating model that improves visibility, accelerates decisions, reduces manual effort, and operationalizes AI across finance, banking, and insurance; delivering quantifiable business outcomes, including:

20–40% improvement in finance productivity

30–60% faster reconciliation and exception resolution

30–50% reduction in financial close effort

5–15% reduction in claims leakage

Improved compliance, controls, and audit readiness

What prevents finance from becoming intelligent

The journey from financial processing to financial intelligence is often hindered by fragmented data, delayed visibility, inconsistent business definitions, and disconnected workflows. These challenges limit operational efficiency, auditability, and the ability to scale AI across finance operations. Combined, these challenges create an intelligence gap that prevents organizations from realizing the full benefits of automation, analytics, and AI.

Common roadblocks to financial intelligence include:

1. Data fragmentation

Financial information is scattered across ERP systems, banking systems, insurance platforms, payment systems, data lakes, and reporting environments. Assembling a complete financial view requires extensive integration, reconciliation, and manual analysis.

2. Operational data stagnation

Business-critical information often remains trapped within operational systems and moves through nightly batches, extracts, and reports before reaching analytics platforms. By the time data becomes available for decision-making, it is no longer real-time.

3. Semantic fragmentation

The same business entities often have different definitions across systems. This creates multiple versions of financial truth and reduces confidence in analytics and AI outputs.

4. Reactive finance operations

Most reconciliation, exception handling, fraud investigation, premium matching, and financial close processes remain heavily manual and event-driven. Rather than focusing on analysis and business outcomes, finance teams spend significant effort gathering information, matching transactions, investigating variances, resolving exceptions, and creating manual journal entries.

5. Limited AI adoption

AI initiatives struggle to scale because enterprise data lacks real-time accessibility, business context, unified semantics, end-to-end lineage, and process integration. As a result, AI remains confined to isolated use cases instead of becoming embedded in day-to-day finance operations.

A framework for intelligent finance operations

The Intelligent Finance Operations Hub creates a unified intelligence layer across finance, banking, and insurance operations, connecting systems of record, enterprise data, AI, and business processes into a single, continuously monitored operating model.

The operating model brings together four connected capabilities that transform enterprise data into intelligent business action:

1. Connect (system + data)

Unifies financial and operational information across finance, banking, insurance, treasury, payments, claims, risk, and regulatory systems into a trusted enterprise data foundation.

2. Understand (AI + insights)

Applies AI, predictive intelligence, semantic search, and business context to transform fragmented data into actionable insights.

3. Act (copilots + agents)

Embedded copilots and intelligent agents automate investigations, resolve exceptions, route approvals, and support operational decision-making.

4. Optimize (operations)

Continuously monitors performance, identifies risks, improves controls, and accelerates financial operations across the enterprise.

The core components of the Intelligent Finance Operations Hub

Rather than replacing existing investments, the Intelligent Finance Operations Hub overlays existing platforms such as Oracle Fusion, banking systems, claims platforms, billing, treasury, and risk solutions to provide real-time visibility, intelligent decision support, and agent-assisted execution.

The Intelligent Finance Operations Hub is built on five interconnected layers that combine transactional systems, trusted data, AI-driven intelligence, and operational execution into a single finance operating model:

1. Systems of record

Oracle Fusion, Banking, Insurance, Treasury, Payments, and Claims platforms remain the systems of transaction and execution.

2. Finance intelligence foundation

Oracle AI Data Platform (AIDP) and Lakehouse create a governed, unified view of financial and operational data.

3. AI and intelligence layer

Oracle AI Database, analytics, copilots, and agents provide intelligence, prediction, automation, and decision support.

Copilots and intelligent agents

Finance copilots and intelligent agents orchestrate actions, automate workflows, support decisions, and manage operational processes across reconciliation, claims, fraud, treasury, and collections functions.

5. Intelligent finance operations layer

Insights are converted directly into business actions across finance, treasury, claims, billing, and shared services operations.

Building a continuously intelligent finance function

The impact of the Intelligent Finance Operations Hub is measured less by technology adoption and more by how quickly organizations can move from information to action. By connecting financial systems, enterprise data, AI, and operational workflows within a single operating model, finance teams can reduce reconciliation and close-cycle effort, accelerate exception resolution, and improve productivity across core finance activities.

With the hub, organizations can achieve 30–60% faster reconciliation cycles, 30–50% reductions in financial close effort, and 20–40% reductions in manual finance operations effort. At the same time, embedded copilots and intelligent agents can reduce investigation and research activities by 40–60% while increasing finance team productivity by 2–3x.

Beyond operational efficiency, a unified intelligence layer provides continuous visibility across finance, treasury, payments, claims, risk, and customer operations. This can lead to 50–70% faster access to operational insights, improved forecast accuracy, and greater confidence in planning and decision-making.

The benefits also extend to governance and risk management. Real-time monitoring, policy-driven automation, and AI-powered anomaly detection can help identify fraud indicators earlier, reduce claims leakage by 5–15%, strengthen audit readiness, and improve financial control across the enterprise.

Making financial intelligence real with Capgemini and Oracle

Capgemini and Oracle help organizations unlock greater value from their existing investments by creating a unified finance intelligence layer across Oracle Fusion, banking, insurance, and operational platforms. Together, we enable organizations to operationalize AI, embed intelligent agents into finance workflows, and transform fragmented finance operations into a continuously monitored, data-driven operating model.

Rather than replacing core systems, the Intelligent Finance Operations Hub builds on existing technology investments to connect information, context, and execution across business processes. This enables continuous visibility into performance, stronger operational control, and faster, more informed decision-making.

While most organizations have already modernized their systems of financial record, the next opportunity is creating a system of financial intelligence that continuously connects data, decisions, and actions across the enterprise. The Intelligent Finance Operations Hub helps close this gap, enabling organizations to move from fragmented processes and reactive operations to intelligent, connected execution at scale.

Authors

Renjith Sreekumar

Head of Oracle Cloud & AI CoE, Financial Services

Renjith Sreekumar is a technology and transformation leader helping Financial Services organizations build AI-ready enterprises through data modernization, intelligent operations, cloud transformation, and agentic AI.

Vijay Shanbhag

Executive Vice President | Global Head – ERP Practice | Financial Services (FS) SBU at Capgemini

As FS ERP Practice leader, Vijay is focussed on building capabilities to sell and deliver ERP work in Financial Services sector (Banking & Capital markets and Insurance). The role includes building out the services and offers to help clients use ERP for Digital transformation driving business value.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
46e1788cd09214135c77f06e82849ca6
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['numbers']. Stichprobe: False
Source Name
Capgemini Newsroom
Original Summary

<p>Discover how the Intelligent Finance Operations Hub unifies data, AI, and workflows across banking and insurance to improve visibility, accelerate decisions, reduce manual effort, and create a continuously intelligent finance function.</p>
<p>The post <a href="https://www.capgemini.com/insights/expert-perspectives/intelligent-fina… Finance Operations Hub: Building a unified finance intelligence platform for banking &amp; insurance</a> appeared first on <a href="https://www.capgemini.com">Capgemini</a>.</p&gt;

Image URL
https://www.capgemini.com/wp-content/uploads/2022/11/Finance-Intelligence-banner.jpg
Source Node
Content Hash (SHA-256, erste 32 hex)
9697d6574d0524419589e24383ef0e1d