SK hynix Announces 3Q26 Financial Results
Original HTML

- Reports revenues of 104.6155 trillion won, operating profit of 83.3338 trillion won, net profit of 39.7756 trillion won; Quarterly sales surpass 100 trillion won for the first time

- Sales of HBM4 and high-value-added server products expanded; HBM4 expected to be the mainstream product from the fourth quarter

- Long-term agreements secured for more than 50% of 2027~2028 production capacity; A structure that reflects market conditions and ensures stable profitability

- Most of the gains from the Kioxia investment to be shared with shareholders, with approximately 100 trillion won in shareholder returns to be executed this year

SEOUL, South Korea, Oct. 27, 2026 /PRNewswire/ -- SK hynix Inc. (or "the company", www.skhynix.com) announced today that it has recorded 104.6155 trillion won in revenues, 83.3338 trillion won in operating profit (with an operating margin of 80%), and 39.7756 trillion won in net profit (with a net margin of 38%) in the third quarter.

- Record quarterly results in both revenue and operating profit and revenue surpasses 100 trillion won for the first time

In a market environment in which prices of key products have risen on the back of growing demand for AI memory, the company once again posted all-time-high quarterly results in both revenue and operating profit, underpinned by the competitiveness of its high-value-added products. In particular, revenue exceeded 100 trillion won for the first time in the company's history. Revenue and operating profit increased by 32% and 38%, from the previous quarter, respectively.

- Q2 2026: Revenue of 79.3187 trillion won, Operating Profit of 60.5426 trillion won

By product, DRAM results were driven by a significant increase in sales of server DDR5 while HBM4 shipments began in earnest. In NAND, sales of 321-layer TLC eSSD expanded, and high-value-added products for data centers continued to grow across the board.

The company's financial structure has also become significantly concrete. At the end of the third quarter, cash and cash equivalents stood at 114.5 trillion won, up 26.5 trillion won from the end of the previous quarter, while borrowings decreased by 2.8 trillion won to 15.8 trillion won. As a result, net cash increased to 98.7 trillion won.

- Memory supply shortage to persist through 2030

SK hynix analyzed that a virtuous cycle has taken hold in which AI-driven productivity gains and new revenue generation in areas such as software development, customer service, and search lead to greater AI adoption, which in turn drives increased investment in infrastructure. It also projected that, as the drivers of AI investment move beyond the early stage, when a small number of companies accounted for most of it, and broaden to include general enterprises and nation-level initiatives, the global AI data center infrastructure market will continue to grow steadily.

The company likewise expects the memory market to sustain its growth, led in the short term by enterprise and personal AI and, over the mid-to-long term, by physical AI such as autonomous driving and robotics.

The company assessed that supply, on the other hand, is not keeping pace with the growth of the market. Given technical difficulty of leading-edge processes and the long lead time required to build new production facilities, it expects the structure in which demand exceeds supply to persist through 2030.

- Expanding production capacity and strengthening product competitiveness to achieve a further step up in growth next year

Building on these favorable conditions, the company plans to accelerate the expansion of production capacity and the strengthening of product competitiveness in order to sustain the current growth momentum, and to scale up revenue and profit one step further next year.

First, the company plans to rapidly increase the portion of its 10nm-class 6th generation (1c) process technology and expand sales of DDR5 and LPDDR5 SOCAMM for AI servers, thereby further strengthening its DRAM portfolio centered on high-value-added products.

To respond to surging HBM demand, the company will ramp up M15X to maximum capacity by the end of the year to increase HBM4 production. Accordingly, the company expects HBM4 to surpass HBM3E in both shipment volume and revenue in the fourth quarter and to establish itself as a mainstream product.

In NAND, the company will raise the ratio of its 321-layer process to more than half of its domestic production capacity in the fourth quarter, and thereby increase the supply of high-performance, high-capacity eSSD. Over the mid-to-long term, the company intends to develop NAND into a core solution that enhances the throughput and economic efficiency of AI services, based on HBF and system optimization technologies.

- Long-term agreements secured for more than 50% of 2027~2028 production capacity and the company to drastically expand investment next year

To improve mid-to-long term demand visibility and solidify its growth foundation, SK hynix is expanding long-term agreements (LTAs) with customers. The company has currently signed LTAs with 14 major customers, including leading global cloud service providers (CSPs), and is also proactively discussing with a number of customers the possibility of extending the contract terms, which are typically five years.

The LTA volume secured to date corresponds to more than 50% of total production capacity for 2027 and 2028. In particular, by introducing a mechanism that reflects market conditions within a price range agreed upon with customers, the company has established a structure that secures stable profitability while allowing flexible responses to market changes.

Backed by the demand visibility, the company is also moving to expand its production capabilities. Next year, with the Yongin Phase 1 entering full-scale operation and domestic and overseas infrastructure investment gaining momentum, investment is expected to increase significantly. The company nevertheless plans to adjust the scale and timing of its investment flexibly, after carefully weighing customer demand, product competitiveness, profitability and investment efficiency.

- Most of the gains from the Kioxia investment to be shared with shareholders, with approximately 100 trillion won in shareholder returns to be executed this year

As previously indicated in August, SK hynix announced its additional shareholder return plan. For fiscal year 2026, the company will pursue shareholder returns totaling approximately 100 trillion won, comprising cash dividends of 30 trillion won or more and share repurchases and cancellations of 60 trillion won or more in total, including the 40 trillion won announced in August. Through this, the company intends to fulfill its commitment to return 50% or more of free cash flow (FCF). Of this, the 40 trillion won share repurchase announced in August was completed last week, and the shares will be cancelled shortly.

The company also set out its principles: the dividend amount will be determined on the basis of operating results; if significant investment gains arise, they will be returned additionally through special dividends; and share repurchases will continue every quarter.

At today's meeting, the Board of Directors resolved on a third-quarter cash dividend of 14 trillion won and a share repurchase of 20 trillion won. Of the shares to be repurchased, 10 trillion won, earmarked for shareholder returns, will be cancelled in full, while the remaining approximately 10 trillion won will be used for employee compensation and is not included in the shareholder return total.

The third-quarter dividend is 20,000 won per share, consisting of a 10,000-won dividend reflecting improved earnings and a 10,000 won special dividend that shares the gains from the Kioxia investment. The company has decided to return to shareholders most of the gains realized from its Kioxia investment this year.

SK hynix emphasized that it will deliver stable results based on robust memory demand growth and technological competitiveness and the company will consistently share financial achievements with our shareholders.

- 3Q26 Financial Results (K-IFRS)

*Unit: Billion KRW

* Financial information of the earnings is based on K-IFRS

* Please note that the financial results discussed herein are preliminary and speak only as of October 28, 2026. Readers should not assume that this information remains operative at a later time.

* Percentage changes are calculated on the basis of unrounded figures.

Disclaimer

This material has been prepared by the Company for informational purposes only, and the information contained herein has not undergone any separate, independent verification process. No representations or warranties are made regarding the fairness, accuracy, or completeness of the information contained in this material, and such information should not be relied upon. Neither the Company nor its employees bear any civil, criminal, or administrative liability for any damages arising from this material or from its use.

Review of the FY2026 Q3 financial results has not been finalized. Figures in this earnings release are subject to changes during the independent auditing process.

All financial information contained in this document is based on consolidated K-IFRS.

This material contains forward-looking statements, which involve risks and uncertainties. These statements are generally identified words such as "may," "will," "intend," "should," "believe," "expect," "anticipate," "project," "estimate" and similar expressions, or the negative of such expressions. Forward-looking statements are not guarantees of future performance and are subject to inherent risks, uncertainties, and other factors that could cause actual results to differ materially from those expressed or implied. Readers are cautioned not to place undue reliance on any of these forward-looking statements. These forward-looking statements speak only as of the date hereof.
Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
prn_302921407
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['finance', 'numbers']. Stichprobe: False
Source Name
Unknown Company
Original Summary

<p>Reports revenues of 104.6155 trillion won, operating profit of 83.3338 trillion won, net profit of 39.7756 trillion won; Quarterly sales surpass 100 trillion won for the first time Sales of HBM4 and high-value-added server products expanded; HBM4 expected to be the mainstream product from...</p>

Content Hash (SHA-256, erste 32 hex)
6f1c914fd633a7f8da9eb56dbba86b08
AMGEN ANNOUNCES 2026 FOURTH QUARTER DIVIDEND
Image File
Original HTML

THOUSAND OAKS, Calif., Oct. 27, 2026 /PRNewswire/ -- Amgen (NASDAQ: AMGN) today announced that its Board of Directors declared a $2.52 per share dividend for the fourth quarter of 2026. The dividend will be paid on December 11, 2026, to all stockholders of record as of the close of business on November 20, 2026.

About Amgen   

Amgen discovers, develops, manufactures and delivers innovative medicines to fight some of the world's toughest diseases. Harnessing the best of biology and technology, Amgen reaches millions of patients with its medicines. 

More than 45 years ago, Amgen helped establish the biotechnology industry at its U.S. headquarters in Thousand Oaks, California, and it remains at the cutting edge of innovation, using technology and human genetic data to push beyond what is known today. Amgen is advancing a broad and deep pipeline and portfolio of medicines to treat cancer, heart disease, inflammatory conditions, rare diseases and obesity and obesity-related conditions.

Amgen has been consistently recognized for innovation and workplace culture, including honors from Fast Company and Forbes. Amgen is one of the 30 companies that comprise the Dow Jones Industrial Average®, and it is also part of the Nasdaq-100 Index®, which includes the largest and most innovative non-financial companies listed on the Nasdaq Stock Market based on market capitalization.

For more information, visit Amgen.com and follow Amgen on X, LinkedIn, Instagram, YouTube, Facebook, TikTok and Threads.

Forward-Looking Statements

This news release contains forward-looking statements that are based on the current expectations and beliefs of Amgen. All statements, other than statements of historical fact, are statements that could be deemed forward-looking statements, including any statements on the outcome, benefits and synergies of collaborations, or potential collaborations, with any other company (including BeOne Medicines Ltd.), the performance of Otezla® (apremilast), our acquisitions of ChemoCentryx, Inc., Dark Blue Therapeutics, Ltd. or Horizon Therapeutics plc (including the prospective performance and outlook of Horizon's business, performance and opportunities, and any potential strategic benefits, synergies or opportunities expected as a result of such acquisition), as well as estimates of revenues, operating margins, capital expenditures, cash, other financial metrics, expected legal, arbitration, political, regulatory or clinical results or practices, customer and prescriber patterns or practices, reimbursement activities and outcomes, effects of pandemics or other widespread health problems on our business, outcomes, progress, and other such estimates and results. Forward-looking statements involve significant risks and uncertainties, including those discussed below and more fully described in the Securities and Exchange Commission reports filed by Amgen, including our most recent annual report on Form 10-K and any subsequent periodic reports on Form 10-Q and current reports on Form 8-K. Unless otherwise noted, Amgen is providing this information as of the date of this news release and does not undertake any obligation to update any forward-looking statements contained in this document as a result of new information, future events or otherwise.

No forward-looking statement can be guaranteed and actual results may differ materially from those we project. Our results may be affected by our ability to successfully market both new and existing products domestically and internationally, clinical and regulatory developments involving current and future products, sales growth of recently launched products, competition from other products including biosimilars, difficulties or delays in manufacturing our products and global economic conditions, including those resulting from geopolitical relations and government actions. In addition, sales of our products are affected by pricing pressure, political and public scrutiny and reimbursement policies imposed by third-party payers, including governments, private insurance plans and managed care providers and may be affected by regulatory, clinical and guideline developments and domestic and international trends toward managed care and healthcare cost containment. Furthermore, our research, testing, pricing, marketing and other operations are subject to extensive regulation by domestic and foreign government regulatory authorities. We or others could identify safety, side effects or manufacturing problems with our products, including our devices, after they are on the market. Our business may be impacted by government investigations, litigation and product liability claims. In addition, our business may be impacted by the adoption of new tax legislation or exposure to additional tax liabilities. Further, while we routinely obtain patents for our products and technology, the protection offered by our patents and patent applications may be challenged, invalidated or circumvented by our competitors, or we may fail to prevail in present and future intellectual property litigation. We perform a substantial amount of our commercial manufacturing activities at a few key facilities, including in Puerto Rico, and also depend on third parties for a portion of our manufacturing activities, and limits on supply may constrain sales of certain of our current products and product candidate development. An outbreak of disease or similar public health threat, and the public and governmental effort to mitigate against the spread of such disease, could have a significant adverse effect on the supply of materials for our manufacturing activities, the distribution of our products, the commercialization of our product candidates, and our clinical trial operations, and any such events may have a material adverse effect on our product development, product sales, business and results of operations. We rely on collaborations with third parties for the development of some of our product candidates and for the commercialization and sales of some of our commercial products. In addition, we compete with other companies with respect to many of our marketed products as well as for the discovery and development of new products. Discovery or identification of new product candidates or development of new indications for existing products cannot be guaranteed and movement from concept to product is uncertain; consequently, there can be no guarantee that any particular product candidate or development of a new indication for an existing product will be successful and become a commercial product. Further, some raw materials, medical devices and component parts for our products are supplied by sole third-party suppliers. Certain of our distributors, customers and payers have substantial purchasing leverage in their dealings with us. The discovery of significant problems with a product similar to one of our products that implicate an entire class of products could have a material adverse effect on sales of the affected products and on our business and results of operations. Our efforts to collaborate with or acquire other companies, products or technology, and to integrate the operations of companies or to support the products or technology we have acquired, may not be successful, and may result in unanticipated costs, delays or failures to realize the benefits of the transactions. A breakdown, cyberattack or information security breach of our information technology systems could compromise the confidentiality, integrity and availability of our systems and our data. Our stock price is volatile and may be affected by a number of events. Our business and operations may be negatively affected by the failure, or perceived failure, of achieving our sustainability objectives. The effects of global climate change and related natural disasters could negatively affect our business and operations. Global economic conditions may magnify certain risks that affect our business. Our business performance could affect or limit the ability of our Board of Directors to declare a dividend or our ability to pay a dividend or repurchase our common stock. We may not be able to access the capital and credit markets on terms that are favorable to us, or at all.

CONTACT: Amgen, Thousand Oaks

Elissa Adair, 609-251-1407 (media)

Casey Capparelli, 805-447-1746 (investors)

SOURCE Amgen

Share this article

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
prn_893860814
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['finance', 'numbers']. Stichprobe: False
Source Name
Unknown Company
Original Summary

<p>THOUSAND OAKS, Calif., Oct. 27, 2026 /PRNewswire/ -- Amgen (NASDAQ: AMGN) today announced that its Board of Directors declared a $2.52 per share dividend for the fourth quarter of 2026. The dividend will be paid on December 11, 2026, to all stockholders of record as of the close of...</p>

Image URL
https://mmx.prnewswire.com/media/MS352354/AMGEN-LOGO-V2.jpg?id=OA3042135&p=facebook
Content Hash (SHA-256, erste 32 hex)
6edd0fe1d2f5d7acbdb787fe93cff4f6
FAO Recognizes Chairwoman of Heifer-Supported Cooperative in Cambodia as an Agrifood Systems Hero
Image File
Original HTML

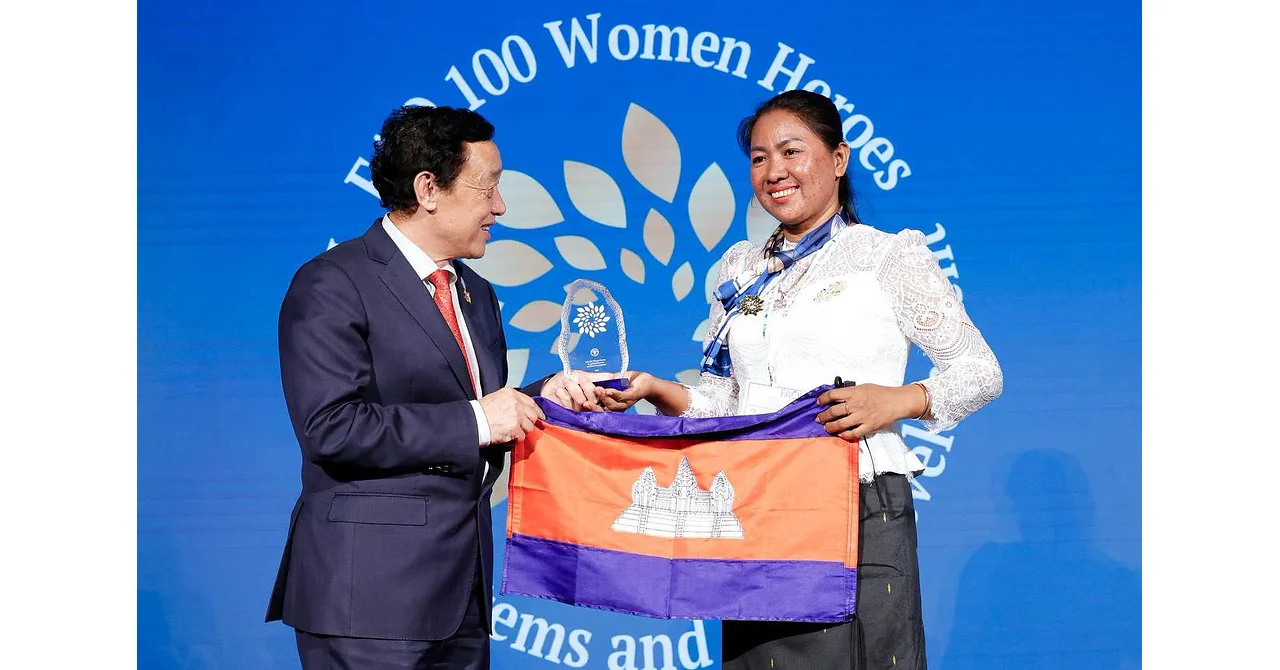
LITTLE ROCK, Ark., Oct. 26, 2026 /PRNewswire/ -- Heifer International is thrilled to congratulate Set Hach, chair of a Heifer-supported agricultural cooperative in Cambodia, for her inclusion by the UN Food and Agriculture Organization (FAO) in its 100 Women Heroes in Agrifood Systems for Rural Development.

Set Hach, chair of the Strey Phokphal Meanchey Agricultural Cooperative in Siem Reap Province, Cambodia, received the award from FAO Director-General Qu Dongyu during a ceremony at FAO headquarters in Rome, Italy on October 15, 2026, during the World Food Forum. The recognition, established in the spirit of the 2026 International Year of the Woman Farmer, celebrates women whose leadership and contributions are helping transform agrifood systems and rural communities.

"We are incredibly proud of Set Hach and her global recognition," said Siyonn Sothearith, Director of Programs at Heifer International Cambodia . "Her leadership demonstrates how one woman's resolve can empower hundreds of smallholder farmers, transform rural communities and strengthen food systems. Her achievement will inspire more women and young people to see themselves as leaders and changemakers."

In 2013, Set Hach joined a women's self-help group supported by Heifer International Cambodia and its partners. She began saving, attending financial literacy and leadership training, and taking part in community activities. She became a self-help group leader and later a volunteer literacy trainer. Encouraged by fellow cooperative members, she stood for election as deputy chair of the cooperative before becoming its chair in 2017.

The cooperative has grown significantly under her leadership. Established in 2016 with just 82 members, including 79 women, it expanded to 540 members, including 451 women, across 30 villages by 2025. Its capital increased from approximately US$2,275 to more than US$130,000, with 3,014 member shares. It also established 23 self-help groups with 556 members, including 487 women, mobilizing more than US$54,000 in savings.

Her journeyâfrom a rural homemaker and volunteer literacy teacher to a nationally respected cooperative leader receiving international recognitionâdemonstrates how access to knowledge, collective action, and leadership opportunities can empower women to drive meaningful change in their communities.

Learn more about Set Hach's journey in this video.

Visit Heifer's She Has a Story to Tell campaign portal, where we are bringing the voices of woman farmers like Set Hach to the fore during the International Year of the Woman Farmer.

ABOUT HEIFER INTERNATIONAL

Since 1944, Heifer International has worked with nearly 62 smallholder farming households in Africa, Asia and the Americas to help them sustainably address hunger and poverty in their communities while caring for the Earth. Through partnerships in multiple sectors, Heifer offers farmers integrated strategies to achieve thriving, resilient lives through better food systems. About two-thirds of Heifer's program participants are women.

For more information, visit https://www.heifer.org .

SOURCE Heifer International

Share this article

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
prn_302921343
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['numbers']. Stichprobe: False
Source Name
Unknown Company
Original Summary

<p>LITTLE ROCK, Ark., Oct. 26, 2026 /PRNewswire/ -- Heifer International is thrilled to congratulate Set Hach, chair of a Heifer-supported agricultural cooperative in Cambodia, for her inclusion by the UN Food and Agriculture Organization (FAO) in its 100 Women Heroes in Agrifood Systems for...</p>

Image URL
https://mmx.prnewswire.com/media/MS2019844/Heifer-International-Set-Hach-at-the-FAO-ceremony.jpg?id=OA3037173&p=facebook
Content Hash (SHA-256, erste 32 hex)
414bb563405f61d24bf56fb8c80c7c9f
FIU Cuba Poll: Cuban American support for Republicans holds despite opposition to deportations
Image File
Original HTML

Majority favors medicine and food sales, private sector aid and immigration relief alongside maximum pressure on the Cuban government

MIAMI, Oct. 27, 2026 /PRNewswire/ -- Seventy-six percent of Cuban Americans in South Florida disapprove of the Trump administration's increased deportations of Cubans with no criminal record, yet 68% still plan to vote for Republicans in November, according to the 2026 FIU Cuba Poll released today.

Poll results will be presented and discussed on Wednesday, Oct. 28, at 11 a.m.

Support for Republican candidates remained consistent at 68 percent, which was the all-time high mark recorded in the 2024 Cuba Poll.

In Florida's U.S. Senate race, Republican Ashley Moody leads Democrat Angela Nixon 51% to 26% among respondents who named a choice. 44% of the full sample was still undecided. In the gubernatorial race, Republican Byron Donalds holds a lead over Democrat David Jolly, 60% to 24% respectively.

Republicans continue to make up the largest share of registered Cuban American voters (53%), followed by Independents (27%) and Democrats (18%).

Among possible Republican candidates for the 2028 presidential nomination, Marco Rubio leads with 58%, followed by J.D. Vance at 8% and Ron DeSantis at 7%. Fifty-four percent would support no Democrat for president in 2028.

"Disappointment with the Trump administration has not moved Cuban Americans out of the Republican Party," said Guillermo J. Grenier, lead investigator on the Cuba Poll and a professor of sociology in the FIU Department of Global & Sociocultural Studies. "Republicans still make up 53% of registered voters, even as 63% of them disapprove of the administration's deportations and 50% are not pleased with its handling of the economy. Marco Rubio receives overwhelming support to carry the party standard in the next presidential election."

The FIU Cuba Poll is the longest-running research project surveying Cuban American sentiment in the country, tracking opinions since 1991. Conducted by the Institute for Cuban Studies (ICS) and the Department of Global & Sociocultural Studies at the Steven J. Green School of International & Public Affairs (Green School), the poll surveyed 1,004 Cuban American adults in Miami-Dade County between September 4 and 29, 2026. The maximum margin of error is plus or minus 3.1 percentage points at the 95% confidence level, after accounting for weighting.

Policy toward Cuba

Respondents favor maximum pressure on the Cuban government (77%) while backing unrestricted sales of medicine and food, aid to Cuba's private sector and the resumption of immigration benefits for Cubans in the United States.

"Cuban Americans want two things at once: a harder line on Havana and a softer life for the Cuban people," said Grenier. "The same respondents who back maximum pressure back medicine, food and aid to Cuba's private sector."

Seventy-three percent favor allowing companies to sell medicine to Cuba without restriction, and 70% favor the same for food. Seventy-four percent favor directing U.S. assistance to Cuba's private sector to relieve the humanitarian crisis. Support is strongest among Democrats and the most recent arrivals, but a majority of Republicans also back these measures (62% for medicine and 64% for private sector aid). Unrestricted travel by all Americans to Cuba divides the community, with 51% in favor and 49% opposed.

The same respondents who back help for the Cuban people also back pressure on its government. Sixty-five percent favor the blockade of oil imports to Cuba, and 69% believe maximum pressure will bring regime change. Seventy-three percent support U.S. military action to overthrow the government, including 87% of Republicans and 68% of Independents. Democrats oppose it. When asked what kind of action they would support, 43% chose a clandestine operation, 28% bombing of selected military targets and 14% a land invasion.

On immigration, 63% of Republicans join the overall majority in disapproving of the administration's increased deportations of Cuban nationals who lack legal status and have no criminal record. Eighty-seven percent say the government should resume processing immigration benefits for Cubans already in the United States, including 86% of Republicans, 90% of Democrats and 86% of Independents.

Cuban Americans want economic change tied to political change. Sixty-seven percent approve of easing sanctions in exchange for a free market economy within two years, but 80% reject a deal that leaves the current government in power in exchange for economic reforms alone. Respondents divide on process: 52% oppose the administration negotiating with members of Cuba's leadership, and 51% approve of a multiparty system with free elections in which the Communist Party may compete.

Lead investigators Guillermo Grenier and Qing Lai will present the data at the Green School International Pavillion (SIPA II Room 102) on Wednesday, Oct. 28, at 11 a.m. A panel discussion will immediately follow, featuring Green School faculty experts Eduardo Gamarra and Dario Moreno and moderated by Institute for Cuban Studies Director Sebastián Arcos. The event will be livestreamed on YouTube, and the full report is available at ics.fiu.edu.

Media Contact:

Daniel Zayas 

305-348-5360 

[email protected] 

news.fiu.edu

@FIU

SOURCE Florida International University

Share this article

Class (B2B/B2C)
Ignore
Ingest Status
Need Review
Dedupe hash
prn_302921348
Press Eligible
No
Press Eligible Reason
Irrelevant (need review): The article primarily reports voter preferences, elections, and political positions.
Source Name
FIU Cuba Poll
Original Summary

<p>Majority favors medicine and food sales, private sector aid and immigration relief alongside maximum pressure on the Cuban government MIAMI, Oct. 27, 2026 /PRNewswire/ -- Seventy-six percent of Cuban Americans in South Florida disapprove of the Trump administration's increased...</p>

Image URL
https://mmx.prnewswire.com/media/MS2022188/FIU-Cuba-Poll.jpg?id=OA3043376&p=facebook
Content Hash (SHA-256, erste 32 hex)
2049d24a5ffebefaca4c97c640d0dd4e
Lufax Reports Third Quarter 2026 Financial Results
Original HTML

Lufax Reports Third Quarter 2026 Financial Results

SHANGHAI, Oct. 27, 2026 /PRNewswire/ -- Lufax Holding Ltd ("Lufax" or the "Company") (NYSE: LU and HKEX: 6623), a leading financial services enabler for small business owners in China, today announced its unaudited financial results for the third quarter ended September 30, 2026.

Third Quarter 2026 Financial Highlights

- Total income was RMB6,180 million (US$922 million) in the third quarter of 2026, compared to RMB6,479 million in the same period of 2025.

- Net loss was RMB1,494 million (US$223 million) in the third quarter of 2026, compared to net loss of RMB380 million in the same period of 2025.

Third Quarter 2026 Operational Highlights

- Total outstanding balance of loans we enabled was RMB167.1 billion as of September 30, 2026, compared to RMB189.6 billion as of September 30, 2025, representing a decrease of 11.9%, among which the outstanding balance of consumer finance loans was RMB70.5 billion as of September 30, 2026, compared to RMB58.9 billion as of September 30, 2025, representing an increase of 19.8%.

- Total new loans enabled were RMB58.3 billion in the third quarter of 2026, representing an increase of 2.5% compared to RMB56.9 billion in the same period of 2025, among which new consumer finance loans were RMB39.7 billion in the third quarter of 2026, compared to RMB31.7 billion in the same period of 2025, representing an increase of 25.2%.

- Cumulative number of borrowers increased by 23.8% to approximately 35.3 million as of September 30, 2026 from approximately 28.5 million as of September 30, 2025.

- As of September 30, 2026, including the consumer finance subsidiary, the Company bore risk on 95.8% of its outstanding balance of loans enabled, up from 87.3% as of September 30, 2025.

- As of September 30, 2026, excluding the consumer finance subsidiary, the Company bore risk on 97.2% of its outstanding balance of loans enabled, up from 88.6% as of September 30, 2025.

- For the third quarter of 2026, the Company's retail credit enablement business take rate[1] based on loan balance was 14.0%, as compared to 13.0% for the third quarter of 2025.

- C-M3 flow rate[2] for the total loans the Company had enabled, excluding the consumer finance subsidiary, was 1.2% in the third quarter of 2026, compared to 1.0% in the second quarter of 2026. Flow rates for the general unsecured loans and secured loans the Company had enabled were 1.2% and 1.1% respectively in the third quarter of 2026, as compared to 1.0% and 0.9% respectively in the second quarter of 2026.

- Days past due ("DPD") 30+ delinquency rate[3] for the total loans the Company had enabled, excluding the consumer finance subsidiary, was 5.5% as of September 30, 2026, as compared to 5.8% as of June 30, 2026. DPD 30+ delinquency rate for general unsecured loans was 5.6% as of September 30, 2026, as compared to 6.1% as of June 30, 2026. DPD 30+ delinquency rate for secured loans remained flat at 5.0% as of September 30, 2026, as compared to 5.0% as of June 30, 2026.

- DPD 90+ delinquency rate[4] for total loans enabled, excluding the consumer finance subsidiary, was 3.2% as of September 30, 2026, as compared to 3.7% as of June 30, 2026. DPD 90+ delinquency rate for general unsecured loans was 3.3% as of September 30, 2026, as compared to 3.9% as of June 30, 2026. DPD 90+ delinquency rate for secured loans was 2.9% as of September 30, 2026, as compared to 3.1% as of June 30, 2026.

- As of September 30, 2026, the non-performing loan (NPL) ratio[5] for consumer finance loans was 1.3% as compared to 1.3% as of June 30, 2026.

"Trading in our ordinary shares on the Hong Kong Stock Exchange resumed on September 24, 2026, and we thank our shareholders and the broader investor community for their patience and support," said Mr. Xiang Ji, Chief Executive Officer of Lufax. "In response to the challenging environment, we continued to apply our selective customer strategy, exited certain high-risk customer segments, and adjusted our post-loan collection approach. Our DPD 30+ and DPD 90+ delinquency rates declined sequentially, while our C-M3 flow rate rose to 1.2%."

"Consumer finance remained our main growth driver, with new consumer finance loan sales up by 25.2% year over year, supporting overall new loan sales growth of 2.5% year over year to RMB58.3 billion. Going forward, we will remain prudent in our operations, focused on quality growth, and committed to delivering long-term value to our shareholders."

"Our net loss for the third quarter was RMB1,494 million, compared to RMB380 million in the same period of 2025," said Ms. Jia Liu, Chief Financial Officer of Lufax. "The increase reflected higher credit impairment losses and additional income tax expenses, primarily due to a reduction of deferred tax assets and recognition of additional withholding taxes in connection with the satisfaction of the funding needs of our Company and its overseas subsidiaries through dividend distribution from domestic subsidiaries. This was partially offset by continued cost discipline, with expenses excluding credit impairment losses, finance costs and other gains or losses down by 13.4% year over year. We remain focused on disciplined execution, strengthening our governance and controls, and building a sustainable, higher-quality growth path for Lufax."

Third Quarter 2026 Financial Results

TOTAL INCOME

Total income was RMB6,180 million (US$922 million) in the third quarter of 2026, compared to RMB6,479 million in the same period of 2025, representing a decrease of 4.6%.

- Technology platform-based income was RMB1,055 million (US$157 million) in the third quarter of 2026, compared to RMB1,390 million in the same period of 2025, representing a decrease of 24.1%. This decrease was primarily due to the decrease of retail credit and enablement service fees as a result of the decrease in the new loan sales and outstanding balance of off-balance sheet loans.

- Net interest income was RMB3,677 million (US$548 million) in the third quarter of 2026, compared to RMB3,334 million in the same period of 2025, representing an increase of 10.3%, mainly due to the expansion of our consumer finance and microloan lending business.

- Guarantee income was RMB1,020 million (US$152 million) in the third quarter of 2026, compared to RMB1,353 million in the same period of 2025, representing a decrease of 24.6%, primarily attributable to a decrease in the average balance of off-balance sheet loans and average fee rates.

- Other income was RMB167 million (US$25 million) in the third quarter of 2026, compared to other income of RMB268 million in the same period of 2025. This decrease was primarily due to a decrease in account management fees caused by decreased collections in the third quarter of 2026.

- Investment income was RMB261 million (US$39 million) in the third quarter of 2026, compared to RMB134 million in the same period of 2025. This increase was primarily attributable to the impact of changes in the valuations of certain assets.

TOTAL EXPENSES

Total expenses increased by 1.7% to RMB6,901 million (US$1,029 million) in the third quarter of 2026 from RMB6,785 million in the same period of 2025. This increase was mainly due to the increase in credit impairment losses by 10.3% to RMB4,511 million (US$673 million) in the third quarter of 2026 from RMB4,089 million in the same period of 2025, partially offset by the decrease in sales and marketing expenses by 13.7% to RMB842 million (US$126 million) in the third quarter of 2026 from RMB976 million in the same period of 2025 and the decrease in operation and servicing expenses by 16.1% to RMB774 million (US$115 million) in the third quarter of 2026 from RMB922 million in the same period of 2025. Total expenses excluding credit impairment losses, finance costs and other gains or losses â net decreased by 13.4% to RMB2,262 million (US$337 million) in the third quarter of 2026 from RMB2,613 million in the same period of 2025.

- Sales and marketing expenses decreased by 13.7% to RMB842 million (US$126 million) in the third quarter of 2026 from RMB976 million in the same period of 2025. The decrease was primarily due to the decreased outstanding balance of off-balance sheet loans.

- General and administrative expenses decreased by 12.1% to RMB420 million (US$63 million) in the third quarter of 2026 from RMB478 million in the same period of 2025. This decrease was primarily due to our continuous expense optimization and control measures.

- Operation and servicing expenses decreased by 16.1% to RMB774 million (US$115 million) in the third quarter of 2026 from RMB922 million in the same period of 2025, primarily due to our expense control measures and the decrease in the loan balance.

- Technology and analytics expenses decreased by 4.2% to RMB226 million (US$34 million) in the third quarter of 2026 from RMB236 million in the same period of 2025, primarily due to expense control measures we adopted.

- Credit impairment losses increased by 10.3% to RMB4,511 million (US$673 million) in the third quarter of 2026 from RMB4,089 million in the same period of 2025, primarily due to the increase in the actual losses and provision of loans and receivables.

- Finance costs increased by 67.1% to RMB122 million (US$18 million) in the third quarter of 2026 from RMB73 million in the same period of 2025, mainly due to the decrease in deposit interest income, partially offset by the decrease in loan interest expenses.

- Other losses were RMB5 million (US$1 million) in the third quarter of 2026, compared to other losses of RMB10 million in the same period of 2025. The change was primarily due to the combined effects of the increase in foreign exchange gains in 2026 and a decrease in government subsidies.

INCOME TAX EXPENSE

Income tax expenses increased by 946.5% from RMB74 million in the third quarter of 2025 to RMB773 million (US$115 million) in the third quarter of 2026.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
prn_302920830
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['finance', 'numbers']. Stichprobe: False
Source Name
Unknown Company
Original Summary

<p>SHANGHAI, Oct. 27, 2026 /PRNewswire/ -- Lufax Holding Ltd ("Lufax" or the "Company") (NYSE: LU and HKEX: 6623), a leading financial services enabler for small business owners in China, today announced its unaudited financial results for the third quarter ended September 30, 2026. Third...</p>

Content Hash (SHA-256, erste 32 hex)
54ba0e165cdf6cfb3cf418ccec15d271
The Chemours Company (CC) Investors: December 7, 2026, Deadline in Securities Fraud Class Action Lawsuit - Kessler Topaz Meltzer & Check, LLP
Image File
Original HTML

Did you buy CC securities between February 20, 2026 and August 4, 2026?

Affected CC Investor Summary

- Who: The Chemours Company (NYSE: CC)

- What: Securities fraud class action lawsuit filed

- Class Period: February 20, 2026 through August 4, 2026

- Deadline to Seek Lead Plaintiff Status: December 7, 2026

- Key Lawsuit Allegations: Material misstatements and/or omissions concerning the reliability of the company's financial guidance

- Investor Action: Contact Kessler Topaz Meltzer & Check, LLP (www.ktmc.com) for recovery options

RADNOR, Pa., Oct. 27, 2026 /PRNewswire/ -- Kessler Topaz Meltzer & Check, LLP (www.ktmc.com), a nationally recognized securities litigation law firm, informs investors that a securities fraud class action lawsuit has been filed against The Chemours Company ("Chemours") (NYSE: CC) on behalf of those who purchased or acquired Chemours securities between February 20, 2026 and August 4, 2026, inclusive. The lawsuit is filed in the United States District Court for the District of Delaware and is captioned Darcy v. The Chemours Company, No. 1:26-cv-01299 (D. Del.). Investors have until December 7, 2026, to file for lead plaintiff status.

CONTACT KTMC TO DISCUSS YOUR LEGAL RIGHTS:    

If you purchased or acquired Chemours securities and have lost money on your investment, please provide your information here: https://www.ktmc.com/cc-the-chemours-company-class-action-lawsuit?utm_source=PR_Newswire&utm_medium=pressrelease&utm_campaign=cc&mktm=PR 

You can also contact attorney Jonathan Naji, Esq. by calling (484) 270-1453 or by email at [email protected]. There is no cost or obligation to speak with an attorney.

To view the Chemours video on YouTube, click here: https://youtu.be/6N2AfSIuXgE

THE CHEMOURS COMPANY CLASS ACTION LAWSUIT - COMPLAINT ALLEGATION SUMMARY:

Chemours is an American chemical company that offers a range of industrial and specialty chemical products for markets including, but not limited to, refrigeration and air conditioning. Chemours's Thermal & Specialized Solutions ("TSS") segment sells its product OpteonTM, a set of refrigeration chemicals with a "near-zero ozone-depletion footprint."

The complaint alleges that, throughout the Class Period, Defendants made materially false and/or misleading statements, as well as failed to disclose material facts about the company's business, operations, and prospects. Specifically, Defendants misrepresented and/or failed to disclose that: (1) Defendants had materially overstated aftermarket demand for their Opteon products; (2) demand for such products was decreasing as a result of Defendants' overselling Opteon products in the preceding fiscal year; (3) as a result of these undisclosed issues, Defendants' financial guidance for the 2026 fiscal year was unreliable; and (4) as a result of the foregoing, Defendants' statements about the company's business, operations, and prospects were materially false and misleading and/or lacked a reasonable basis at all relevant times.

WHY DID CHEMOURS'S STOCK DROP?

After the market closed on August 4, 2026, Chemours announced its second quarter 2026 financial results, revealing, among other things, that the company reduced its adjusted EBITDA full year guidance to $775 million to $825 million, down from $800 million to $900 million previously. The company attributed this, and its year-over-year net sales decrease of approximately 1%, to a "4% decrease in volumes." Specifically, it stated that "[t]he volume decline was primarily driven by lower TSS Opteon⢠blends aftermarket refrigerant sales."

On this news, the price of Chemours stock fell $3.34 per share, or 18.63%, to close at $14.59 per share on August 5, 2026.

WHAT THE CHEMOURS COMPANY INVESTORS CAN DO NOW:

- File to be lead plaintiff by December 7, 2026.

- Contact KTMC for a free case evaluation. All representation is on a contingency fee basis, there is no cost to you.

- Retain counsel of choice or take no action.

THE LEAD PLAINTIFF PROCESS FOR THE CHEMOURS COMPANY INVESTORS:

Chemours investors may, no later than December 7, 2026, seek to be appointed as a lead plaintiff representative of the class through Kessler Topaz Meltzer & Check, LLP or other counsel, or may choose to do nothing and remain an absent class member. A lead plaintiff is a representative party who acts on behalf of all class members in directing the litigation.  The lead plaintiff is usually the investor or small group of investors who have the largest financial interest and who are also adequate and typical of the proposed class of investors. The lead plaintiff selects counsel to represent the lead plaintiff and the class and these attorneys, if approved by the court, are lead or class counsel. Your ability to share in any recovery is not affected by the decision of whether or not to serve as a lead plaintiff.

Kessler Topaz Meltzer & Check, LLP encourages Chemours investors to contact the firm for more information.

ABOUT KESSLER TOPAZ MELTZER & CHECK, LLP (KTMC):    

Kessler Topaz Meltzer & Check, LLP (KTMC) is a leading U.S. plaintiff-side law firm focused on securities-fraud class actions and global investor protection. The firm represents individual investors as well as institutions, such as major pension funds, asset managers, and international investors. KTMC has led some of the largest recoveries in securities litigation and has been recognized by peers and the legal media with numerous accolades, including being recognized in Chambers & Partners USA 2026 as a Band 1 Top Firm in Securities and Class Actions, Legal 500's Tier 1 Rankings for Securities and M&A Litigation, The National Law Journal's Plaintiff's Hot List and Trailblazers in Plaintiffs' Law, BTI Consulting Group's Honor Roll of Most Feared Law Firms, The Legal Intelligencer's Class Action Firm of the Year, Lawdragon's Leading Plaintiff Financial Lawyers, and Law360's Titans of the Plaintiffs Bar. The firm operates globally with offices in Pennsylvania and California. KTMC has recovered over $25 billion for our clients and the classes they represent.  The complaint in this matter was not filed by KTMC.

CONTACT:

Jonathan Naji, Esq.

(484) 270-1453

280 King of Prussia Road

Radnor, PA 19087

[email protected] 

May be considered attorney advertising in certain jurisdictions. Past results do not guarantee future outcomes.

SOURCE Kessler Topaz Meltzer & Check, LLP

Share this article

Class (B2B/B2C)
Ignore
Ingest Status
Need Review
Dedupe hash
prn_302918372
Press Eligible
No
Press Eligible Reason
Irrelevant (need review): Law firm alert promoting a securities fraud class action and soliciting investors.
Source Name
The Chemours Company (CC) Investors
Original Summary

<p>Did you buy CC securities between February 20, 2026 and August 4, 2026? Affected CC Investor Summary Who: The Chemours Company (NYSE: CC) What: Securities fraud class action lawsuit filed Class Period: February 20, 2026 through August 4, 2026 Deadline to Seek Lead Plaintiff Status:...</p>

Image URL
https://mmx.prnewswire.com/media/MS669377/Kessler-Topaz-Meltzer-and-Check-Logo.jpg?id=OA3037025&p=facebook
Content Hash (SHA-256, erste 32 hex)
ebe7f2690aab31899815371d97874a40
Cummings & Cummings Law Reports 12-Fold Surge in California Business Departures Ahead of Proposition 40 Vote
Original HTML

Cummings & Cummings Law Reports 12-Fold Surge in California Business Departures Ahead of Proposition 40 Vote

Companies are relocating from California to Florida, Texas, Wyoming, and Tennessee as owners reassess tax exposure, regulatory uncertainty, and the long-term costs of maintaining a California business domicile.

DALLAS, Oct. 27, 2026 /PRNewswire/ -- Cummings & Cummings Law, a multistate law firm specializing in interstate business redomestication, reports a 12-fold increase in California-origin companies relocating to Florida, Texas, Wyoming, and Tennessee through its practice as California approaches its November 3 vote on Proposition 40, the proposed billionaire wealth tax.

The increase reflects the firm's own redomestication activity, rather than a statewide count of California business departures. It comes amid heightened scrutiny of California's tax policies and growing interest among business owners in aligning their companies' legal domiciles with their personal residences and operations.

Proposition 40 would impose a one-time 5% tax on the covered net worth of qualifying billionaires who were California residents on January 1, 2026. Business ownership interests would be included among the assets subject to valuation. The measure, which voters will consider on November 3, is not currently law.

Although the proposed tax would apply to a narrow group of wealthy taxpayers rather than businesses generally, Cummings & Cummings Law reports growing interest in relocation among owners of privately held businesses evaluating their long-term exposure to California's broader tax and regulatory environment.

"What we are observing is not simply a change in where business owners want to live," said Chad D. Cummings, an attorney and Certified Public Accountant with Cummings & Cummings Law. "Business owners are examining whether it makes economic or legal sense to maintain a company under California law when its management, ownership, and operations have moved elsewhere. Proposition 40 has brought additional attention to those questions, but the underlying financial considerations extend well beyond any single ballot initiative."

Unlike dissolving a business and forming a replacement, redomestication can permit an existing LLC or corporation to change its state of legal domicile while preserving business continuity, subject to the procedures authorized by the originating and destination jurisdictions and applicable federal tax requirements. Redomestication remains the gold standard for transferring a company to a new state.

That distinction matters for established businesses with existing contracts, financing arrangements, federal tax elections, and other relationships that could be disrupted by an improperly designed relocation.

The firm emphasizes that corporate redomestication and individual tax residency are separate legal questions. Changing a company's state of organization does not automatically eliminate California tax obligations arising from continuing business activity. Nor would a relocation undertaken after January 1, 2026, by itself, eliminate potential liability under Proposition 40's proposed residency rules.

The observed increase does not establish that Proposition 40 caused every departure. Business owners may also be responding to operating costs, family relocation, administrative obligations, and differences among state business-law regimes.

"Moving a company is not the same thing as changing its mailing address," Cummings added. "The transaction must satisfy the laws of two states and the applicable federal tax rules. The objective is to change the company's legal home without sacrificing the business relationships and tax attributes its owners have spent years establishing."

With the November 3 election approaching, the firm's reported increase provides a practice-level indication of how some California business owners are reassessing their long-term corporate domicile.

About Cummings & Cummings Law

Cummings & Cummings Law is a multistate law firm providing business, tax, and commercial legal services, including interstate redomestication of limited liability companies and corporations. The firm advises business owners on changing their companies' states of legal domicile while addressing federal tax continuity, corporate governance, and related commercial obligations.

For additional information, visit https://www.cummings.law/redomestication/.

Media Contact

Cummings & Cummings Law

https://www.cummings.law/redomestication/

SOURCE Cummings & Cummings Law

Share this article

Class (B2B/B2C)
Ignore
Ingest Status
Need Review
Dedupe hash
prn_302921371
Press Eligible
No
Press Eligible Reason
Irrelevant (need review): Law firm press release promoting its legal services.
Source Name
Unknown Company
Original Summary

<p>Companies are relocating from California to Florida, Texas, Wyoming, and Tennessee as owners reassess tax exposure, regulatory uncertainty, and the long-term costs of maintaining a California business domicile. DALLAS, Oct. 27, 2026 /PRNewswire/ -- Cummings & Cummings Law, a multistate...</p>

Content Hash (SHA-256, erste 32 hex)
ec63e4039900786418c64ea0efbe6089
Horse Racing Picks Today at Churchill Downs for Wednesday, October 28
Image File
Original HTML

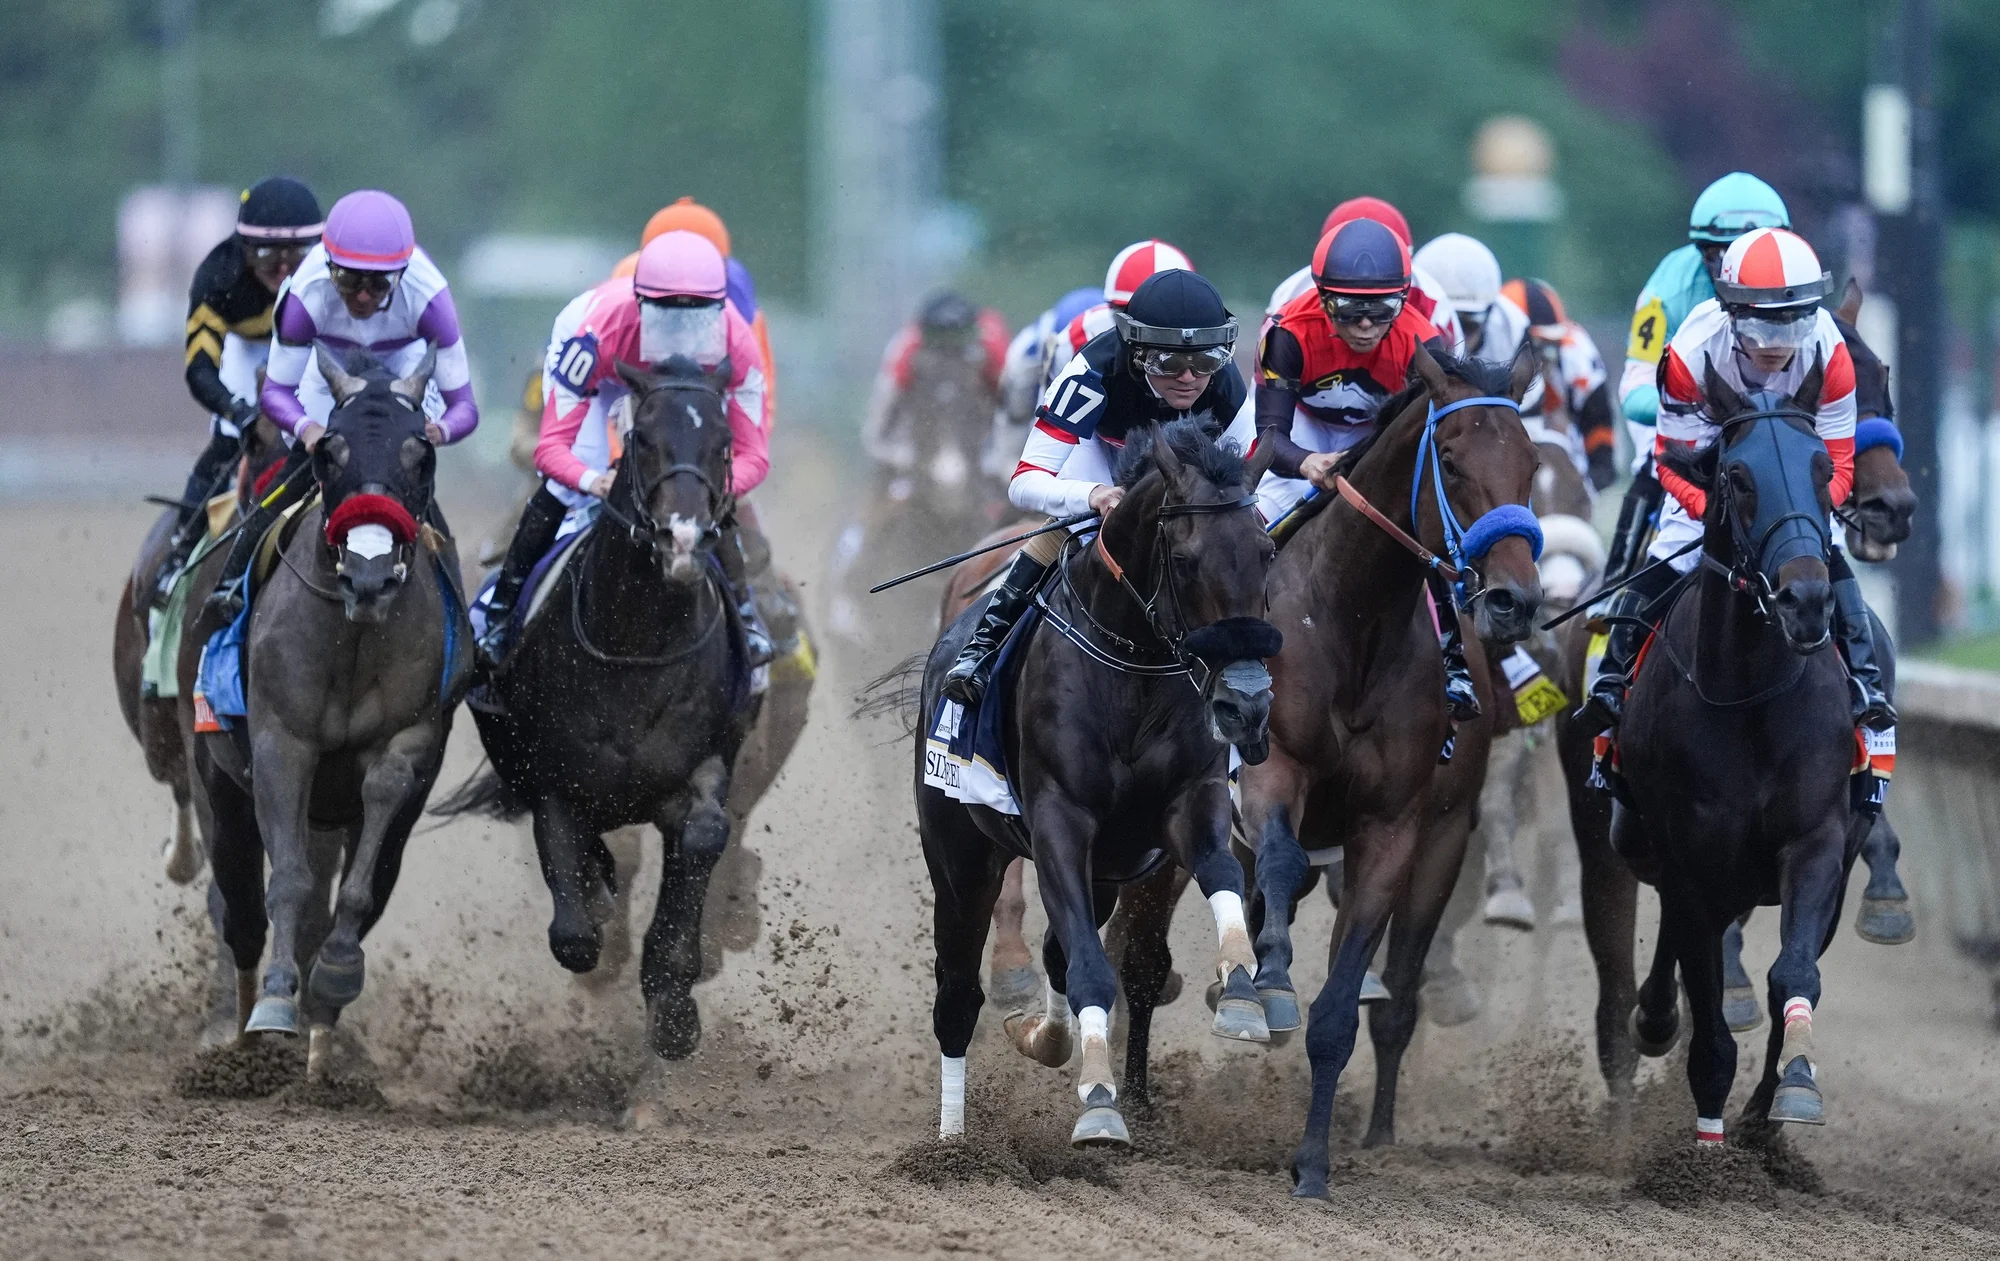
Daily Racing Form expert handicapper and analyst Scott Ehlers handicaps the Wednesday, October 28 racing card at Churchill Downs, including his projected 1-2-3 finishers. His best bet of the day comes from Race 8.

Also, view FREE DRF Past Performances for today’s Race of the Day.

BEST BET: Corona de Oro (8th Race)

Eighth Race

1. Corona de Oro

2. Ortley Avenue

3. Twilight Delight

CORONA DE ORO is by an 11% debut turf sire. His dam went 7-0-0-1 on the sod and earned a modest 10K. Lone grass sibling is 3-1-0-2 and earned 81K (won turf debut). Works continue sharp. What if this colt is better in a sprint? His distance Tommy is a nice 380. This colt ran well in his first three starts, and they were all sprints. Did you notice that he didn’t break sharp in any of those? Team Stewart are 14% with their debut turfers. If all stay in, then we count four speed horses in here. We are going to insist on a good price for this 3YO. ORTLEY AVENUE has had the lead at the first call in six of seven starts. Other speed to the inside and outside won’t matter if this guy can blitz them early. This colt is feeling great and now puts four races together. Yet to try the local sod, and he will have to break in a new jockey, but can’t fault anyone who circles his name. TWILIGHT DELIGHT broke 10th of 11 in his most recent but still beat over half the field home. With a better break, he would have run a Beyer top. He is bred to love a turf sprint with Tomlinsons of 340/392. Team Leitch have a flat bet profit in turf sprints, on the turf, and sprinting.

Here are Scott’s thoughts on the other eight races on Wednesday’s Churchill Downs card.

First Race

1. Feral

2. Attersee

3. Discotheque

FERAL might be the value. It took eight starts to break his maiden, but what if he got a taste for winning and liked it? He beat first-time winners just before the layoff. He has now run back-to-back Beyer tops. Team Tomlinson are 19% off this type of layoff. Race flow is more than fair, and we like that win rider keeps the call. ATTERSEE got an 88 Beyer the last time that he tried an elongated sprint. This guy has yet to miss the exacta going seven panels. A poor break proved costly in his most recent. New barn is 12% off the claim. This post is fine, and his trip should be the same. DISCOTHEQUE draws the attack post and loves this distance at 5-2-2-0. He didn’t get a ton of play in his most recent when sent off at 14-1 and then tired late. Front bandages were added in that race, so check to see if those are gone today. Class drop is easy to see, but a new jock will be summoned as Irad broke his left ankle and is out for a while. SIX STRING PRINCE exits a key race where 2 of 5 returned to win with figs of 77 and 82.

Second Race

1. Rapoport

2. Chanbersville

3. Catch the Breeze

RAPOPORT gets to save all the early ground with his rail draw, but added distance is what we like best. This gelding likes his new barn as he makes his fifth start for team Maker. Did this guy just not dig Kentucky Downs last out? Or was a mile too short? That race did come back key when 2 of 5 returned to win with figs of 91 and 90. CHAMBERSVILLE is an improving 3YO, and we love, love, love these types as we get late into the year. That was a Beyer top in his most recent. Team McPeek turns this colt around rather quickly, and we think that is a good sign. Tactical speed in a race with little pace is another plus. CATCH THE BREEZE is just feeling great. His last race came back key when 2 of 5 returned to win with figs of 60 and 86. Team McCarthy are 13% with their repeating winners. We like how this guy went from the West Coast to Kentucky and held his good form.

Third Race

1. Harbor Prince

2. Guns Allowed

3. Macchiato

HARBOR PRINCE tries two turns for only the second time, and his first was in start number two (solid second). Figs figure as this gelding puts three races together. Added distance might be the key as his sibs were best going long. Two of three siblings won routing while the outlier went 4-0-2-1. The best was a multiple route winner of 147K. Team Drury are a nice 20% going sprint to route. GUNS ALLOWED did get a 70 Beyer in his second start, and that was way back in March. This new gelding has to be more mature now, and that means faster. Works are solid for team Cox. MACCHIATO has some speed and could find the front end. Form cycle hints at better as this guy drops in class. A pace play first and foremost.

Fourth Race

1. Statutory

2. Spill the Sugar

3. Enticing Moves

STATUTORY only cost 10K, so the drop isn’t as big as it might look on paper. We spy four sibs that earned over 200K. Works are rock solid as this filly puts races together for the first time. Her distance Tomlinson of 421 screams sprint. Here comes a better effort with Arrieta up. SPILL THE SUGAR just ran a Beyer top and did so in only her second start on a fast track. In fact, this 3YO has gotten a Beyer top in both starts going this distance. A better start might help more than anything. ENTICING MOVES has beaten over half the field home in all three of her starts. She has improved her Beyer in all of her starts. Of course, we like this outside post when sprinting. Race flow is average at best, but that just means this 4YO won’t be that far off whoever finds the front end.

Fifth Race

1. Greystone

2. Lahainaluna

3. Caragogo

GREYSTONE can run all day, so 11 furlongs is no problem. Current form is sharp, while last race came back key when 2 of 7 returned to win with figs of 96 and 90 (two more finished 2nd with Beyers of 99 and 95). Those double layoff lines three back are water under the bridge as this 6YO strings three races together. Lasix is returned, while race flow is more than fair if all stay in. LAHAINALUNA was denied a clean trip last out. It is never easy to break your maiden going 12 furlongs, but that is what this colt did only two back. Win rider returns and is 24% for Team Sharp. This barn is on a roll this year. A pair of recent works is just right, and notice how fast they were. CARAGOGO is speed. If afforded an early breather, she could prove troublesome to run down. Is this colt a new route horse? A better price than our top two picks, we would think.

Sixth Race

1. Noroomformischief

2. Epic Prankster

3. She’s Not a Joke

NOROOMFORMISCHIEF gets class relief as she drops into starter foes. This filly cuts back a full furlong and did run a Beyer top two back going six panels. Race flow is fast as we spy three in here with early zip. EPIC PRANKSTER popped and stopped off the layoff, but seven furlongs is a tough task off a layoff. This filly has speed and draws outside main pace foes. She gets in light, and that will help her early zip. Wire please. SHE’S NOT A JOKE has some well-spaced works for her return. Is this the type of horse that has trouble versus allowance foes but just seems to click versus easier? Those races two and three back help our case. This mare wants to pass runners, and race flow is more than fair.

Seventh Race

1. Cartier Gold

2. Love Divine

3. Aegis

CARTIER GOLD catches a race light on pace and draws the attack post for the distance. This filly puts races together for the first time and goes second time seven panels. This filly did beat over half the field home in both starts. We like that Saez keeps the call. Lone knock is that team Servis are 0 for 13 second off this type of layoff. LOVE DIVINE was improving by the minute until her most recent when she broke 11th of 12. Out the window that goes. Tactical speed and outside draw go hand in hand all with team Asmussen in your corner. AEGIS exits a key race where 2 of 8 returned to win with figs of 84 and 78 (another finished 2nd with a 77 Beyer). Turfway works are well spaced, and this horse has never run poorly when sprinting. Is this filly the speed? GET INTO IT is by an 11% debut sire. Her dam went 20-5-3-3 and earned 226K. Two of four sibs won, and both beat winners (946K and 65K). M’S MABEE BABY exits a key race where 3 of 9 returned to win with figs of 70, 55, and 73.

Ninth Race

1. Perpetua

2. Yasmin

3. Sharp Mindset

PERPETUA ran evenly in her debut even though she broke last. That race came back key when 2 of 3 returned to win with figs of 69 and 64. Lone sibling is 25-1-3-4 and earned 66K. Local works are well spaced. How much has this filly matured since last being seen in July? YASMIN tried better in her first two starts at Oaklawn. Her turf debut two back was better than it looks, and she was right there with a furlong to go. Her most recent was poor, but it was also her first start at KD. She puts three races together and should love sprinting with a huge 453 distance Tomlinson. SHARP MINDSET ran OK in her first two starts. That wasn’t the case in her third start, so did something go awry, hence the time off? Nothing wrong with her return race at Horseshoe Indy, where the racing is improving by the minute. This filly gets in super light as she tries the dirt for the first time. Trainer stats are just good across the board. MO BISCUIT exits a key race where 3 of 7 returned to win with figs of 49, 62, and 63.

Daily Racing Form is the most trusted source for horse racing news and information. Get an edge when you play the races with DRF.com.

Get more Daily Racing Form horse racing picks on a daily basis on our VSiN Horse Racing page.

Get DRF’s Complete Breeders’ Cup Betting Package with Past Performances, Expert Picks, Clocker Reports and more.

Ingest Status
Rejected
Dedupe hash
9a9b0e885df6e271bfcef0b96aa6ce85
Press Eligible Reason
JSON nicht lesbar - manuelle Pruefung noetig: Inhalt konnte nicht als JSON geparst werden
Source Name
VSiN
Original Summary

<p>Daily Racing Form expert handicapper and analyst Scott Ehlers handicaps the Wednesday, October 28 racing card at Churchill Downs, including his projected 1-2-3 finishers. His best bet of the day comes from Race 8. Also, view FREE DRF Past Performances for today&#8217;s Race of the Day. BEST BET: Corona de Oro (8th Race) Eighth Race [&#8230;]</p>
<p>The post <a href="https://vsin.com/horse-racing/horse-racing-picks-today-at-churchill-dow… Racing Picks Today at Churchill Downs for Wednesday, October 28</a> appeared first on <a href="https://vsin.com">VSiN</a>.</p&gt;

Image URL
https://vsin.com/wp-content/uploads/2026/06/USATSI_28872557_168384654_lowres_1aaa2f.jpg
Source Node
Content Hash (SHA-256, erste 32 hex)
c5c6951153f7de861a7f87d27851d2c9
Ferrovial N.V. announces an interim scrip dividend
Image File
Original HTML

AMSTERDAM, Oct. 27, 2026 /PRNewswire/ -- Ferrovial N.V. ("Ferrovial", Ticker: "FER") declares an interim scrip dividend of in aggregate EUR 600 M, payable in cash or in Ferrovial shares at the election of Ferrovial's shareholders, against Ferrovial's reserves. The dividend per Ferrovial share will be determined based on the number of shares outstanding on the relevant ex-dividend date and is expected to be announced on 3 November 2026.

Ferrovial shares will trade ex-dividend as of 5 November 2026 (the "European Ex-Dividend Date") on the Madrid, Barcelona, Bilbao and Valencia stock exchanges (the "Spanish Stock Exchanges"), and as of 6 November 2026 (the "US Ex-Dividend Date") on Nasdaq's Global Select Market ("Nasdaq"). In compliance with applicable listing requirements, the dividend record date will be 6 November 2026.

The number of outstanding Ferrovial shares entitled to receive one additional Ferrovial share (the "Ratio") will be determined based on the volume weighted average price of all traded Ferrovial shares on the Spanish Stock Exchanges on 18, 19 and 20 November 2026. Ferrovial will calculate the Ratio such that the gross EUR value of dividend in shares will be approximately equal to the gross dividend in cash.

The Ratio and the number of Ferrovial shares to be delivered in connection with the scrip dividend are expected to be announced on 3 December 2026. Ferrovial may deliver treasury shares or newly issued Ferrovial shares, or a combination thereof, to the shareholders entitled to receive the dividend in Ferrovial shares.

Ferrovial shareholders are given the opportunity to indicate their election between cash and Ferrovial shares:

(1) from 9 November 2026 (9:00 am Central European Time, "CET") until 20 November 2026 (5:30 pm CET), in relation to Ferrovial shares held through a custodian as a participant in (i) Nederlands Centraal Instituut voor Giraal Effectenverkeer B.V. ("Euroclear Nederland"), or (ii) Sociedad de Gestión de los Sistemas de Registro, Compensación y Liquidación de Valores, S.A. Unipersonal ("Iberclear"); and

(2) from 9 November 2026 (9:00 am Eastern Time, "ET") until 20 November 2026 (5:00 pm ET), in relation to Ferrovial shares held through a custodian as a participant in The Depository Trust Company ("DTC"), or as a holder of shares in registered form directly on the share register of Ferrovial ("Registered Form").

If no election is made during the relevant election period, an election for a dividend in shares will be deemed to have been made and the dividend will consequently be paid in shares.

Banks and brokers may process the dividend in accordance with any applicable default option as agreed upon in their respective contractual arrangements with Ferrovial shareholders or may set an earlier deadline for the receipt of election instructions from their clients to those detailed above. Ferrovial shareholders should contact their bank or broker to check their default option and timings.

Distributions in cash, including settlement of share fractions in cash, where applicable, will be made in EUR, other than to Ferrovial shareholders who hold their shares (i) through custodians as participants directly in DTC, or (ii) in Registered Form, who will be paid in USD at the USD/EUR rate as per the BFIX: Bloomberg FX Fixings Frankfurt 2:00 pm CET fixing of 20 November 2026.

Dividends in cash, where applicable, are in principle subject to 15% Dutch dividend withholding tax, which will be deducted from the cash amount to be paid. Dividends in the form of Ferrovial shares, which will be paid up from Ferrovial's reserves, are in principle subject to Dutch dividend withholding tax, but only in respect of the nominal value of such Ferrovial shares (which value amounts to EUR 0.01 per share). Ferrovial will bear the Dutch dividend withholding tax in respect of such dividends in the form of Ferrovial shares, which will amount to 17.65% on EUR 0.01 per Ferrovial share. If you are entitled to an exemption from Dutch dividend withholding tax on the cash dividend, please contact your bank or broker to receive the full distribution on the dividend payment date as set out below.

In addition, local tax withholding may be applicable depending on the tax residency, or other tax status of the shareholders.

Additional information about the tax consequences of the scrip dividend can be found at https://www.ferrovial.com/en/ir-shareholders/stock-information/dividends/. Ferrovial shareholders are advised to consult their tax advisors regarding these tax consequences in any relevant jurisdictions, including whether they may be entitled to an exemption from Dutch dividend withholding tax or can credit such tax.

Ferrovial shares to be delivered as dividend will rank pari passu in all respects with Ferrovial's outstanding shares.

If relevant changes to the timetable are made, they will be announced to the market.

Election facilities will be made available via the bank or broker where Ferrovial shares are administered at the start of trading on 9 November 2026. Ferrovial shareholders are requested to indicate their choice within the election period set forth above, through their bank or broker, or directly as may be appropriate, to:

(1) ING Bank N.V., if you are a holder of shares through a custodian that is a participant in Euroclear Nederland or Iberclear;

(2) DTC, if you are a holder of shares through a custodian that is a participant in DTC; and

(3) Computershare Trust Company, N.A., in accordance with the election form issued, if you are a holder of shares in Registered Form.

Payment of the cash dividend and delivery of shares, with settlement of fractions in cash, if required, will take place from 10 December 2026 onwards on the basis of share entitlements on the dividend record date.

Settlement in cash of fractions, if required, will take place based on the volume weighted average price of all traded Ferrovial shares on the Spanish Stock Exchanges on 18, 19 and 20 November 2026.

This document is made available by publication on Ferrovial's website and is the document referred to in article 1 paragraph 4 sub h of the EU Prospectus Regulation (2017/1129). More information on the rights attached to Ferrovial shares can be found at Corporate Policies - Shareholders and Investors | Ferrovial and more information about Ferrovial can be found at www.ferrovial.com/en/ir-shareholders/.

Forward-Looking Statements

This announcement contains forward-looking statements, which include statements with respect to the timeline and main steps of the scrip dividend. Any express or implied statements contained in this announcement that are not statements of historical fact may be deemed to be forward-looking statements, including, without limitation, statements regarding estimates and projections provided by Ferrovial and certain other sources with respect to Ferrovial's financial position, business strategy, plans, and objectives of management for future operations, dividends, capital structure, as well as statements that include the words "expect," "aim," "intend," "plan," "believe," "project," "forecast," "estimate," "may," "will", "should," "target," "anticipate" and similar statements of a future or forward-looking nature, or the negative of these terms or other similar expressions, although not all forward-looking statements contain these words. Such statements may reflect various assumptions by Ferrovial concerning anticipated results and are subject to significant business, economic and competitive uncertainties and contingencies, and known and unknown risks, many of which are beyond Ferrovial's control and may be impossible to predict. Any forecast made or contained herein, and actual results, will likely vary and those variations may be material. Ferrovial makes no representation or warranty as to the accuracy or completeness of such statements, expectations, estimates and projections contained in this announcement or that any forecast made or contained herein will be achieved.

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
prn_302921335
Press Eligible
Yes
Press Eligible Reason
Manuelle Prüfung nötig. Risiko: MEDIUM. Flags: ['finance', 'numbers']. Stichprobe: False
Source Name
Unknown Company
Original Summary

<p>AMSTERDAM, Oct. 27, 2026 /PRNewswire/ -- Ferrovial N.V. ("Ferrovial", Ticker: "FER") declares an interim scrip dividend of in aggregate EUR 600 M, payable in cash or in Ferrovial shares at the election of Ferrovial's shareholders, against Ferrovial's reserves. The dividend per Ferrovial...</p>

Image URL
https://mmx.prnewswire.com/media/MS1549413/FER-BR-FERROVIAL-MAIN-RGB-Logo-Logo.jpg?id=OA3043167&p=facebook
Content Hash (SHA-256, erste 32 hex)
3ac442b09bef348bf8948ddeff442c6a
Western Microsurgical Announces Acquisitions of Q Surgical and Proficient Surgical
Original HTML

Western Microsurgical Announces Acquisitions of Q Surgical and Proficient Surgical

Partnerships expand surgical microscope service and sales across 18 states

DENVER, Oct. 27, 2026 /PRNewswire/ -- Western Microsurgical, LLC ("WMS"), a portfolio company of HealthEdge Investment Partners, LLC ("HealthEdge"), today announced the acquisitions of Q Surgical and Proficient Surgical. These partnerships bring together established regional businesses to expand WMS's platform as an independent service organization ("ISO") and provider of surgical microscopes, operating room products, and supplies to hospitals and ambulatory surgery centers ("ASCs").

Founded in 2009, Q Surgical serves hospitals and ASCs in Northern California and Nevada, while Proficient Surgical, founded in 1996, serves the Northeast. Both companies bring longstanding relationships with surgical teams and leading manufacturers, along with expertise in surgical microscopy and complementary operating room products.

WMS also expanded its territory through the transfer of the Leica Microsystems sales and service contract previously held by Shawnee Medical in two states. With these additions, the combined company provides surgical microscope sales and service across 18 states in the western and northeastern United States.

The owners of Q Surgical and Proficient Surgical have retained meaningful ownership in the combined company and remain actively involved in its operations. Their continued leadership will support longstanding relationships with hospitals, ASCs, and surgical teams while helping drive the combined company's next phase of growth.

"Q Surgical and Proficient Surgical have built strong reputations through deep product knowledge, longstanding relationships, and responsive service," said Brian Bedrick, founder and CEO of WMS. "We are excited to partner with their owners and teams to build on those strengths. Together, we can deliver broader equipment and service capabilities to hospitals and ASCs while preserving the personal attention and local expertise they value."

"Partnering with WMS is an exciting next step for Q Surgical," said Will Aarsheim, co-founder of Q Surgical. "We share a commitment to supporting surgeons and operating room teams with the right equipment and dependable service. We look forward to remaining involved as owners and helping build the combined company."

"We are proud of the business and relationships we have built at Proficient Surgical," said Steven Baum, founder of Proficient Surgical. "This partnership brings together complementary teams with a shared focus on quality and service. Remaining invested in the combined company allows us to help shape its future while continuing to support the hospitals and surgical teams we have served for many years."

The acquisitions advance WMS's strategy of building a national surgical microscopy platform through partnerships with experienced operators. Financial terms were not disclosed.

About Western Microsurgical

Based in Denver, Colorado, Western Microsurgical operates as an independent manufacturer's representative and independent service organization for Leica Microsystems, supporting surgical microscopy used in spine, neurological, and ophthalmic procedures at hospitals, ASCs, and specialty clinics. WMS also distributes surgical instruments, operating room products, and supplies from leading manufacturers.

About HealthEdge Investment Partners

Founded in 2005, HealthEdge Investment Partners is an operating-oriented private equity firm focused exclusively on healthcare. HealthEdge invests in businesses that can benefit from its partners' industry knowledge, experience, and relationships. Its partners collectively bring more than 100 years of healthcare experience as operators and investors.

Contact: Sandie Spangler, [email protected], 8134907105

SOURCE Western Microsurgical, LLC

Share this article

Class (B2B/B2C)
B2B
Ingest Status
Rewritten
Dedupe hash
prn_302921316
Press Eligible
Yes
Press Eligible Reason
Healthcare industry acquisition expands surgical microscope services across multiple states.
Source Name
Unknown Company
Original Summary

<p>Partnerships expand surgical microscope service and sales across 18 states DENVER, Oct. 27, 2026 /PRNewswire/ -- Western Microsurgical, LLC ("WMS"), a portfolio company of HealthEdge Investment Partners, LLC ("HealthEdge"), today announced the acquisitions of Q Surgical and Proficient...</p>

Content Hash (SHA-256, erste 32 hex)
479309adb2e77bd68a297810f4a774ae